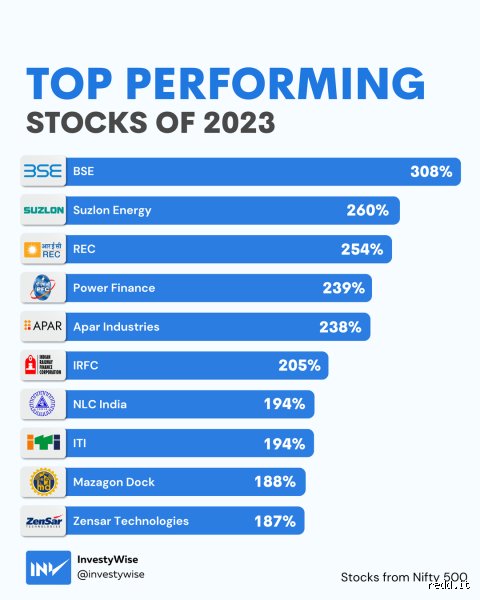
Decoding the anatomy of equity returns and asset classes
A stock is not just a digital ticket on a screen. It represents fractional ownership of an actual enterprise generating cash flows in a messy, unpredictable global economy. Yet, mainstream media loves pushing the narrative that finding the single best-performing asset is simple. Which share gives the highest return? That question completely misses the structural reality of market dynamics.
The illusion of guaranteed yields
Look at historical data from the New York Stock Exchange between 1926 and 2023. During this nearly century-long stretch, broad market indices delivered annualized nominal returns hovering around 10 percent. But individual equities behaved wildly differently. Because some firms went bankrupt while others minted billionaires, the distribution resembles a power law. Fat-tail events dominate financial outcomes. And it is unclear whether past equity premia will hold up over the next fifty years.
Dividends versus capital appreciation
Income-seeking investors often default to mature blue chips like Coca-Cola or Johnson & Johnson, pointing to steady quarterly payouts. But the issue remains: reinvested dividends tell only half the story. Total shareholder return factors in both price appreciation and cash distributions. If you bought shares of Nvidia back in January 2013, you witnessed a staggering surge driven by artificial intelligence tailwinds, transforming a modest stake into a fortune. That changes a lot about how we view growth versus value.
Unpacking volatility, beta, and the Risk-Reward tradeoff
Risk is not just standard deviation. It is the permanent loss of capital. Which share gives the highest return during a liquidity crunch? Usually, none, because liquidity dries up entirely. We are far from simple textbook models where higher risk automatically guarantees a predictable linear bump in profit. Take the collapse of Enron in 2001 or Lehman Brothers in 2008. Both boasted massive market caps before evaporating into thin air.
Small-Cap stocks and the size premium
Fama and French popularized the idea that smaller enterprises outperform large caps over extended horizons. Companies like Monster Beverage started as penny stocks before dominating supermarket shelves worldwide, delivering astronomical multi-thousand percent gains. The size factor rewards patience and stomach-churning drawdowns. But liquidity constraints and higher bankruptcy rates plague this segment, which explains why institutional money often hesitates.
Growth versus value through market cycles
Since the 2008 financial crisis, mega-cap tech stocks like Apple, Microsoft, and Amazon utterly crushed traditional value stocks in sectors like energy and finance. Which share gives the highest return shifted dramatically toward software and cloud infrastructure. Then inflation struck in 2022, causing painful corrections across Silicon Valley darling valuations. Markets are cyclical beasts.
Comparing direct equity picking versus indexing strategies
Picking individual equities feels exhilarating. You read the 10-K filings, analyze balance sheets, and place your bets. Yet, SPIVA data consistently shows that over 80 percent of professional active fund managers fail to beat the S&P 500 over a ten-year span. Passive indexing removes single-company blow-up risk entirely. If you owned the entire index during the dot-com bubble burst, you survived because resilient innovators like Amazon and Microsoft kept compounding value.
The hidden cost of behavioral biases
Loss aversion destroys portfolios faster than a bear market. Investors panic-sell at the absolute bottom, locking in catastrophic losses. Which share gives the highest return becomes an irrelevant academic exercise if you sell your holdings during a panic. Emotional discipline trumps stock selection every single time.
Common mistakes
Chasing past performance blindly
Many investors believe that a company's historical gains guarantee future riches, yet reality often proves otherwise. The problem is that markets constantly shift, which explains why last year's market star frequently becomes this year's laggard. Because human psychology craves simple patterns, retail buyers flood into inflated equities right before a correction hits. You must look beyond simple backward-looking metrics and evaluate the actual operational momentum instead. Historical returns do not predict future gains, no matter how shiny the chart looks.
Confusing high risk with guaranteed high returns
Another widespread error involves assuming that buying the most volatile asset automatically yields maximum profit. The trouble is that high volatility often leads straight to permanent capital destruction rather than wealth creation. (We have all seen speculative bubbles burst overnight.) As a result, blind speculation destroys more portfolios than calculated risk-taking. You need to distinguish between intelligent asset allocation and pure gambling on micro-cap stocks.
Ignoring the hidden drag of fees and taxes
Beginners frequently calculate their potential equity yield without factoring in transaction costs or capital gains taxes. Yet every brokerage fee chips away at your compounding engine. High turnover rates act as a silent portfolio killer. Minimizing unnecessary trading costs is mandatory for preserving long-term purchasing power.
What most people miss
The power of overlooked factor tilts
Most everyday market participants obsess over single stock picking, ignoring academic models that point toward more reliable wealth generators. The secret weapon of institutional funds involves factor investing, targeting specific characteristics like profitability and low volatility. This is why certain systematic portfolios outperform glamorous growth stocks over decades. Factor-based portfolio tilting captures market anomalies that standard index funds miss. You can harness these exact same mathematical edges by utilizing targeted exchange-traded funds rather than guessing individual ticker winners.
Frequently asked questions
Are penny stocks the best vehicle for maximum equity returns?
No, penny stocks rarely deliver sustainable high returns for the average investor. These micro-cap equities suffer from extreme manipulation, low liquidity, and abysmal financial transparency. Over 90 percent of pink-sheet companies eventually lose value or delist entirely. Therefore, chasing micro-cap hype is an easy way to lose your entire principal rather than secure wealth.
Does dividend reinvestment significantly boost long-term yield?
Yes, compounding through automatic dividend reinvestment accounts for a massive portion of historical stock market wealth creation. For instance, the S&P 500 generated a total return exceeding 300 percent over specific ten-year blocks when dividends were automatically plowed back in. Without this mechanism, cash sitting idle misses out on exponential growth curves. Consequently, treating dividends as active capital rather than spending money transforms your portfolio trajectory.
How many individual equities should I own to optimize performance?
Diversification limits catastrophic losses, but holding too many equities dilutes your potential upside. Modern portfolio theory suggests that holding between 15 and 25 carefully selected equities across distinct sectors eliminates most unsystematic risk. Exceeding 30 stocks often leads to closet indexing, where your returns merely mimic the broader market average. Striking this precise balance gives you optimal exposure without unmanageable tracking error.
The short version
The pursuit of the single equity delivering the absolute highest return is ultimately an illusion that misleads smart capital. Markets reward disciplined patience and structural advantages far more reliably than they reward blind luck or reckless speculation. You must accept that optimizing your portfolio requires balancing calculated growth with sensible risk management instead of hunting for mythical unicorn stocks. The single greatest investment you can make is mastering your own emotional discipline during market panics. Building lasting wealth is a marathon of strategic choices rather than a single explosive sprint.