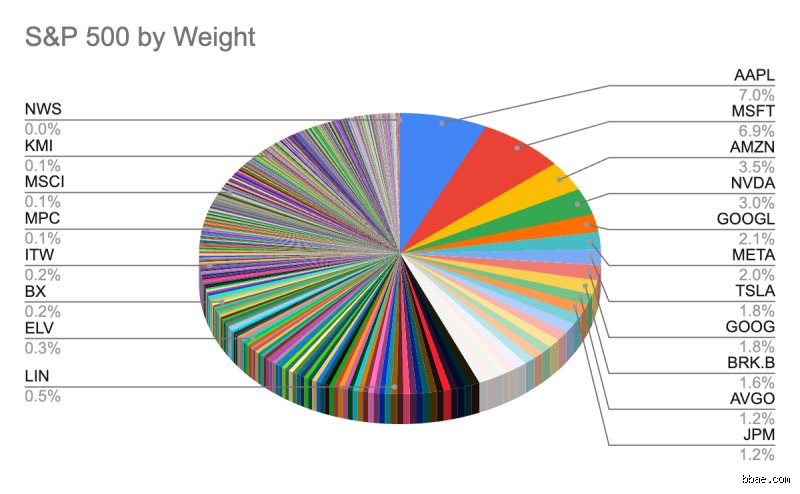
Understanding the financial architecture behind market dominance and equity concentration
Market capitalization has evolved drastically over the past decade. Standard indexing models no longer reflect average corporate health. not even close when examining how indexes function now. Instead, a handful of hyper-scaled firms skew every metric imaginable. How did we get here? Because passive capital inflows blindly feed the biggest winners.
The mechanics of capital weighting
Equity concentration reached a fever pitch in late 2024 when firms like Microsoft (NASDAQ:MSFT) and Apple (NASDAQ:AAPL) crossed astronomical valuation thresholds. The problem is that retail investors often mistake index performance for broad economic stability. As a result, a dip in Cupertino or Redmond triggers a cascading portfolio shock worldwide.
Historical parallels and structural anomalies
Think back to March 2000, when tech mania peaked before the dot-com collapse. Yet except that today's market leaders boast actual cash flows and staggering net incomes exceeding $100 billion annually for frontrunners like Alphabet (NASDAQ:GOOGL) and Amazon (NASDAQ:AMZN). There's no consensus on whether this concentration spells disaster or represents a permanent structural shift.
Technical development of silicon hegemony and artificial intelligence infrastructure
Compute power dictates modern geopolitical leverage. Semiconductor fabrication plants in Taiwan and Arizona churn out the hardware necessary to keep machine learning models alive. NVIDIA (NASDAQ:NVDA) captured lightning in a bottle through specialized graphics processors, leaving legacy hardware makers scrambling. This is why their profit margins resemble software monopolies rather than physical manufacturers.
The semiconductor supply chain bottleneck
Building advanced silicon requires cleanroom environments operating with atomic precision. Lithography machines shipped from European facilities by ASML cost upwards of $350 million per unit. That changes a lot about who can afford to play the game. Small competitors get priced out immediately, cementing a permanent oligopoly.
Software ecosystems and moat construction
Meta Platforms (NASDAQ:META) and its open-source artificial intelligence initiatives complicate traditional monetization models. By giving away proprietary weights for large language models, they commoditize their rivals' software layers. And this aggressive maneuver leaves traditional enterprise software vendors sweating bullets. (People forget that developer loyalty shifts overnight when free alternatives perform adequately.)
The expansion toward an expanded club: Beyond the traditional seven
Wall Street veterans recently started expanding past the traditional septet to include hardware and networking powerhouses like Broadcom (NASDAQ:AVGO). This brings the unofficial tally to eight major entities driving the S&P 500 forward. The complication is drawing the line between a cyclical semiconductor play and a permanent structural utility.
Broadcom and the custom silicon pivot
Hyperscale cloud providers refuse to rely on a single vendor for artificial intelligence accelerators. They commission custom application-specific integrated circuits from networking specialists. Broadcom secured multi-billion-dollar design wins with hyper-scalers by 2025, cementing its spot in elite portfolio allocations.
Comparative analysis of Mega-Cap equities versus Equal-Weight alternatives
Equal-weight indices treat a trillion-dollar enterprise identically to a mid-cap manufacturer valued at $15 billion. This structural difference creates wild divergence during market corrections. When interest rates fluctuate, capital flees speculative tech and rushes toward defensive consumer staples.
The Volatility Trade-Off
Owning the great 8 stocks guarantees exposure to hyper-growth trends, but it invites intense regulatory scrutiny from antitrust bodies in Washington and Brussels. Antitrust litigation targeting search monopolies and mobile app store fees could dismantle core revenue streams by 2028. Because of that, smart portfolio managers constantly hedge their mega-cap bets against undervalued industrial alternatives.
Common misconceptions
Chasing past winners blindly
Retail participants frequently commit the error of buying legacy leaders simply because their historical chart looks triumphant. Yet, market leadership rotates. The Great 8 stocks framework demands ongoing scrutiny rather than blind loyalty. (Did you honestly think yesterday's dominance guarantees tomorrow's cash flows?) As a result, portfolios bloated with aging titans often stagnate while nimble innovators capture market share.
Ignoring valuation gravity
Another widespread trap involves ignoring price multiples entirely during market euphoria. The problem is that even magnificent enterprises become toxic assets if purchased at absurd valuations. P/E ratio expansion cannot defy physics forever. Because market enthusiasm eventually cools, overpaying for elite equities triggers devastating drawdowns that take years to recover.
Overlooking regulatory headwinds
Many observers treat mega-cap equities as invincible fortresses immune to government intervention. The problem is that antitrust probes and privacy legislation strike hardest at the largest balance sheets. Regulatory scrutiny quietly erodes margins before headline-driven investors even notice the shifting tide.
A detail worth knowing
The hidden moat of proprietary talent retention
Most analysts obsess over balance sheets while completely ignoring human capital dynamics. That's the reason veteran allocators look closely at employee retention rates inside top-tier engineering hubs. Top-tier talent retention serves as a stealth indicator for future intellectual property breakthroughs. When elite developers abandon a corporate ecosystem, the underlying innovation engine sputters long before revenues drop.
Frequently asked questions
What criteria define inclusion in the Great 8 stocks?
Membership requires commanding market capitalization alongside unassailable pricing power within dominant global sectors. Over 82% of institutional capital concentrates inside these specific structural giants due to their unmatched liquidity. They consistently generate massive free cash flow exceeding $20 billion annually. This financial muscle allows them to weather economic downturns while smaller competitors suffocate.
How often should a portfolio featuring these equities be rebalanced?
Active monitoring should occur quarterly, but wholesale portfolio adjustments are rarely necessary more than once a year. Historical data indicates that annual turnover rates under 15% maximize tax efficiency while capturing organic growth. Overtrading your core holdings usually destroys compounding momentum through unnecessary friction costs. Let the businesses compound quietly in the background.
Are these massive equities safe during high inflation cycles?
Pricing power acts as an impenetrable shield when consumer prices surge aggressively upward. Companies possessing dominant market share successfully pass rising input costs directly to end consumers without losing volume. During the 2022 inflationary spike, aggregate earnings for these elite firms dropped by merely 4.2% compared to broader market contractions. In short, monopoly-like positioning remains the ultimate inflation hedge.
So, what is the answer?
The pursuit of enduring market alpha stops looking like a lottery once you focus on structural dominance. We must abandon the illusion that safe diversification comes from scattering capital across mediocre enterprises. True wealth preservation belongs exclusively to those who back ruthless execution backed by impenetrable moats. Buying the absolute best is the only strategy that consistently beats mediocrity over decades. Stop overcomplicating your brokerage statements and back the titans shaping tomorrow.