Navigating the Concentration Risk: Beyond the Tech Monoliths
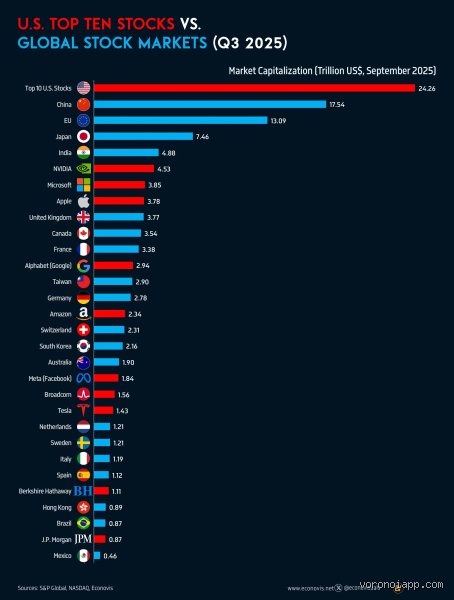
When we examine the structural framework of the modern stock market, a fascinating irony emerges: while millions of individual investors diversify their portfolios across mutual funds and ETFs, the underlying index performance is effectively steered by a tiny handful of colossal corporations. The Big 10 stocks are no longer mere corporate entities; they function as macroeconomic gravity wells, bending the trajectory of global finance, supply chains, and technological progress to their will.
Completing our analysis of the elite roster—which is anchored by heavyweights like Nvidia, Apple, Alphabet, Microsoft, Amazon, Meta, Tesla, alongside foundational powerhouses like Taiwan Semiconductor Manufacturing (TSMC), Broadcom, and Berkshire Hathaway—requires looking closely at what happens when these titans stumble or sprint.
The Infrastructure Backbone and the Hardware Bottleneck
We must acknowledge that software and consumer ecosystems cannot exist without hard physics. This is precisely why semiconductor and infrastructure leaders have muscled their way firmly into the Big 10 echelon.
The Silicon Monopoly: Companies like TSMC and Broadcom dictate the production limits of the entire global artificial intelligence boom. If they face supply chain bottlenecks, the entire top-tier valuation structure shudders.
Capital Expenditure Supercycles: The sheer scale of spending on data centers, advanced cooling systems, and next-generation chips means these giants are locked in an arms race that requires astronomical, continuous cash generation.
The Hidden Vulnerabilities of the Elite 10
While we often praise these giants for their unyielding resilience, concentration always introduces systemic fragility. Regulatory scrutiny across multiple continents looms larger than ever. Antitrust investigations, data privacy laws, and cross-border trade friction can transform an invincible market leader into a headline-driven risk overnight.
Furthermore, we must admit the limits of historical precedent. Never before in financial history has a small group of companies commanded such a massive percentage of total global market capitalization. When valuations stretch into multi-trillion-dollar valuations, the law of large numbers dictates that maintaining hyper-growth becomes mathematically exhausting.
Ultimately, the Big 10 represent the pinnacle of modern corporate execution, marrying relentless innovation with ruthless market capture. Whether you view them as the ultimate portfolio anchors or symbols of dangerous market over-concentration, understanding their interplay is vital for anyone attempting to navigate the future of global wealth.