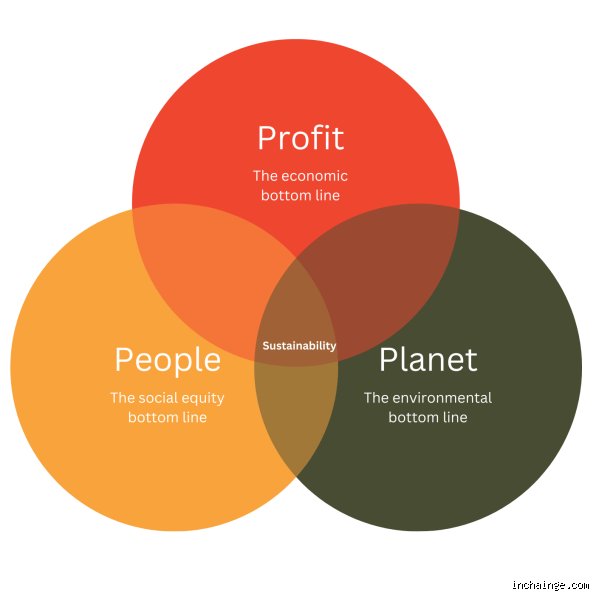
Enter the framework of the Triple Bottom Line, commonly known as the 3Ps: People, Planet, and Profit. Coined by sustainability pioneer John Elkington in 1994, this framework fundamentally challenges traditional accounting models by expanding a company's reporting obligations beyond financial gains to encompass environmental stewardship and social impact. This opening segment explores the foundational mechanics of the 3Ps, examining why modern enterprises must balance human well-being and ecological preservation alongside economic viability to achieve long-term survival.
The evolution of commercial purpose
To fully understand the weight of the 3Ps, we must examine the historical trajectory of corporate responsibility. Throughout the twentieth century, prevailing economic theories—most notably associated with Milton Friedman—argued that the sole social responsibility of a business was to increase its profits, provided it stayed within the rules of the game. Under this philosophy, addressing societal or environmental challenges was the exclusive domain of governments or philanthropic organizations, while businesses focused entirely on generating returns for capital owners.
As the twenty-first century unfolded, structural changes in technology, communication, and climate science rendered this separation untenable. Consumers gained unprecedented access to supply chain data, allowing them to scrutinize the labor practices behind their apparel, the carbon footprints embedded in their electronics, and the sourcing methods behind their food. Investors began recognizing that environmental degradation and social unrest posed material risks to corporate balance sheets. Climate change introduced severe supply chain disruptions, regulatory fines, and stranded assets. Concurrently, a growing workforce of younger generations demanded higher ethical standards from their employers, linking their professional contributions to organizational values.
Faced with these realities, corporate leaders realized that financial capital depends entirely on human and natural capital. Depleting natural resources or alienating communities eventually destroys the very foundation upon which commercial operations stand. The 3Ps framework emerged as a practical response to this complex reality, offering a structured method for organizations to measure success across three distinct dimensions rather than a single financial ledger.
The first p: People (Social capital and human impact)
The first component of the framework, People, centers on the human element of commerce. Every commercial entity interacts with a vast network of human beings, ranging from the employees who build products to the communities that host facilities and the end-users who purchase goods. Measuring performance through the lens of People requires organizations to evaluate how their operations affect human well-being, dignity, equity, and health across these groups.
Evaluating internal stakeholders begins with workplace culture and operational safety. Progressive organizations look far beyond basic regulatory compliance regarding labor laws. They invest heavily in ergonomic working conditions, mental health resources, fair compensation structures, and robust professional development programs. Employee turnover rates, retention metrics, pay equity audits, and safety incident tracking serve as quantifiable indicators of social performance internally. When an organization treats its workforce as an invaluable asset rather than an expendable cost center, it fosters institutional knowledge, innovation, and loyalty.
Externally, the People pillar extends to supply chain transparency and community relations. Global corporations often operate sprawling supply chains spanning dozens of countries with vastly different legal frameworks. A commitment to the People pillar means ensuring that raw material extraction, manufacturing, and distribution do not involve forced labor, child labor, or unsafe conditions. Companies audit tier-one, tier-two, and tier-three suppliers, establishing codes of conduct and providing economic support to elevate supplier standards.
At the local community level, businesses impact housing markets, infrastructure, and public health. Responsible enterprises engage in active dialogue with local residents before building facilities, invest in local educational initiatives, support public health programs, and minimize noise or traffic congestion. By treating the community as a stakeholder rather than a passive backdrop, businesses build social license, an intangible yet critical asset that protects them against regulatory pushback and community opposition.
The second p: Planet (Environmental stewardship and ecological integrity)
The second component, Planet, addresses the ecological footprint generated by commercial activities. Traditional accounting treated natural resources, water, air, fertile soil, and minerals, as free or limitless inputs. Externalities such as pollution, carbon emissions, and biodiversity loss were absorbed by society at large, remaining unaccounted for on corporate income statements. The Planet pillar corrects this oversight by integrating environmental impact into the core evaluation of business health.
Environmental stewardship begins with climate impact and energy management. Organizations measure their greenhouse gas emissions across scopes one, two, and three, tracking direct emissions from owned facilities, indirect emissions from purchased electricity, and the extensive emissions generated throughout the supply chain and product lifecycle. Setting science-based targets to transition toward renewable energy sources, electrifying fleets, and optimizing facility efficiency are foundational steps in minimizing atmospheric harm.
Beyond carbon, the Planet pillar demands a fundamental rethinking of resource utilization through circular economy principles. Linear economic models follow a take-make-dispose trajectory, extracting finite resources, manufacturing products, and sending them to landfills. In contrast, circular models design waste out of systems entirely. Organizations committed to the Planet pillar prioritize recycled inputs, biodegradable materials, product modularity, repairability, and closed-loop recycling systems where old products become raw materials for new ones.
Water stewardship represents another critical dimension. Manufacturing, agriculture, and processing industries consume vast quantities of freshwater, often returning polluted effluent to local watersheds. Responsible firms measure water intensity, implement closed-loop cooling and filtration systems, and restore local ecosystems to ensure that their operations do not deplete community water supplies or damage aquatic biodiversity. Similarly, land use practices, deforestation prevention, and regenerative agriculture initiatives ensure that agricultural supply chains enhance soil health rather than degrading arable land into barren dust.
By internalizing environmental costs and proactively regenerating ecosystems, businesses safeguard their own operational continuity. A manufacturer that depends on specific agricultural inputs cannot survive if continuous soil erosion destroys crop yields. Thus, environmental responsibility ceases to be an act of mere philanthropy and becomes a strict prerequisite for long-term economic survival.
Bridging to Profit and integration
While People and Planet address critical social and environmental dimensions, the third P, Profit, remains the engine that powers sustainable enterprise. Far from rejecting financial returns, the triple bottom line redefines profit as the ultimate validator of economic viability, innovation scalability, and long-term resource allocation. However, profit under this framework is earned without compromising human welfare or ecological stability. In the subsequent sections of this analysis, we will explore the intricate dynamics of the Profit pillar, the synergies and tensions among the three components, and the practical methodologies executives use to implement this framework across global operations.
Quantifying the Triple Bottom Line
Transitioning the 3Ps framework from a philosophical mission statement into an operational model requires rigorous methodology. Historically, businesses mastered financial accounting because currency provides a universal unit of measurement. However, standardizing metrics for social impact (People) and ecological footprint (Planet) has historically posed a complex technical hurdle for corporate strategists.
To resolve this, modern enterprises employ advanced accounting architectures, such as Integrated Reporting () and environmental lifecycle assessments (LCAs). These tools translate qualitative values into actionable quantitative data, enabling data-driven decision-making across all three dimensions.
Social Metrics (People): Organizations track Key Performance Indicators (KPIs) extending far beyond mandatory payroll data. These include living-wage gap analyses, employee turnover associated with burnout, total hours of professional upskilling, Occupational Safety and Health Administration (OSHA) incident rates, and supply chain human rights audits.
Environmental Metrics (Planet): Technical accounting utilizes Scope 1, 2, and 3 greenhouse gas inventories, water withdrawal intensity per unit of output, toxic waste diversion rates, and biodiversity impact indicators. Life-cycle assessments evaluate the total ecological footprint of a product from raw material extraction to end-of-life disposal or recycling.
Economic Metrics (Profit): Beyond standard net income and EBITDA, economic value added (EVA) is calculated by subtracting the cost of capital from operating profits, ensuring that capital is deployed efficiently while respecting social and ecological boundaries.
Little-Known aspect: The friction of Trade-Offs and greenwashing risks
While the synergy of People, Planet, and Profit sounds frictionless in theory, day-to-day execution frequently introduces severe strategic dilemmas. A common misconception is that all three Ps naturally grow in tandem. In practice, executives often face high-stakes zero-sum trade-offs.
For instance, sourcing raw materials from local, fair-trade cooperatives (supporting People and reducing transport emissions for the Planet) might significantly increase production costs, temporarily suppressing short-term Profit. Conversely, cutting labor expenses to maximize margins directly violates the social compact of the framework.
The lack of a single, universally mandated global standard for non-financial reporting has historically left the door open for "greenwashing", where marketing departments exaggerate a company's eco-friendly or social contributions without substantive operational changes. To combat this, regulatory shifts, such as the European Union’s Corporate Sustainability Reporting Directive (CSRD), are forcing organizations to treat non-financial data with the exact same auditing rigor as financial statements. Under modern frameworks, vague corporate claims are rapidly being replaced by legally verifiable accountability.
Final Verdict
The 3Ps framework, People, Planet, and Profit, marks a permanent evolution in modern corporate philosophy. Moving far beyond short-term shareholder primacy, the Triple Bottom Line recognizes that authentic, enduring business value cannot be extracted at the expense of society or the environment.
Integrating the 3Ps is no longer viewed merely as an act of corporate philanthropy or compliance. Instead, it functions as a core engine of enterprise risk management, brand loyalty, and long-term economic resilience. Companies that successfully balance social equity, environmental stewardship, and financial viability position themselves to lead markets in a resource-constrained world, proving that sustainable growth and profitability are fundamentally interdependent.