The foundational role of auditing in modern governance: Ensuring accuracy, Accountability, and trust
The evolution and imperative of financial scrutiny
The importance of this practice cannot be overstated. As businesses scale and market dynamics grow increasingly intricate, the asymmetry of information between corporate management and external stakeholders—such as shareholders, creditors, regulators, and the general public—widens significantly. Management possesses direct insight into the daily operations and financial positioning of the entity, whereas external parties must rely on reported figures to make capital allocation decisions. Auditing bridges this critical trust deficit. By providing an independent, professional opinion on whether financial statements present a true and fair view in accordance with established accounting standards, auditors validate the reliability of corporate reporting.
The scope of auditing has expanded dramatically over the past few decades. While traditional financial audits remain foundational, modern organizations increasingly subject themselves to operational audits, compliance audits, IT system audits, and sustainability or environmental, social, and governance (ESG) verifications. This broadening of scope reflects a fundamental shift in how business value is perceived. Stakeholders no longer care solely about bottom-line profitability; they demand transparency regarding risk management, ethical governance, operational efficiency, and sustainable practices. Consequently, a comprehensive auditing framework acts as both a shield against financial misstatement and a compass guiding strategic resilience.
To fully grasp the multifaceted impact of this discipline, one must examine the specific dimensions through which auditing delivers value to an enterprise and the wider economic ecosystem. The following analysis explores the first two critical pillars of auditing importance, detailing how rigorous examination safeguards financial accuracy and fortifies internal governance.
1. Ensuring financial accuracy and reliability in corporate reporting
The primary and most historically recognized significance of auditing lies in its capacity to ensure the absolute accuracy and reliability of financial statements. Every day, trillions of dollars change hands based on balance sheets, income statements, and cash flow reports. If these documents are flawed, distorted, or intentionally manipulated, the consequences can cascade through global markets with devastating velocity.
Financial reporting is inherently complex. It requires management to make numerous estimates, judgments, and accounting policy choices, ranging from the valuation of intangible assets and long-term provisions to the recognition of revenue under evolving international standards. These estimates introduce a degree of subjectivity, creating fertile ground for unintentional errors or aggressive financial positioning. An independent audit introduces a vital layer of rigorous scrutiny. Trained external auditors test underlying transactions, verify account balances with third-party confirmations, evaluate management's assumptions, and assess whether the chosen accounting policies align with frameworks such as GAAP or IFRS.
Through this meticulous testing process, auditing achieves three distinct objectives regarding financial accuracy:
Error Detection and Correction: Routine operational errors, such as duplicate entries, misclassifications, or mathematical miscalculations, are systematically identified and rectified before financial statements are published.
Fraud Prevention and Detection: While the primary responsibility for preventing and detecting fraud rests with management and those charged with governance, the presence of an active, unpredictable audit schedule acts as a powerful deterrent against fraudulent activities like asset misappropriation or fraudulent financial reporting.
Standardization and Comparability: By ensuring that financial statements strictly adhere to recognized accounting standards, auditing guarantees that investors can accurately compare the financial health of one company against another within the same industry.
When an independent auditor issues an unqualified (or "clean") audit opinion, they provide the market with a reasoned assurance that the financial data is free from material misstatement. This validation is what allows capital to flow efficiently across global markets, ensuring that investors are rewarding genuinely performing enterprises rather than accounting illusions.
2. Strengthening internal controls and Operational efficiency
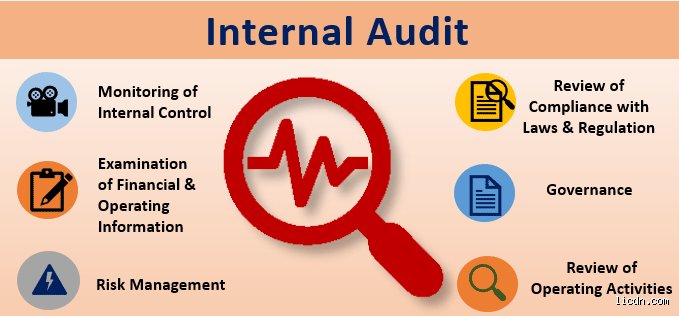
Beyond the validation of historical financial statements, auditing plays a transformative role in evaluating and strengthening an organization's internal control environment. Internal controls encompass the policies, procedures, physical security measures, and IT access restrictions put in place by management to safeguard assets, ensure accurate record-keeping, and promote operational efficiency.
When conducting an audit, professionals do not merely look at the final numbers; they examine the machinery that produces those numbers. This involves mapping out business processes, testing whether control mechanisms are operating effectively, and identifying vulnerabilities or systemic weaknesses. For example, an auditor might discover that the same employee who approves vendor invoices also has the authority to disburse payments, a classic segregation-of-duties flaw that creates a severe risk of unauthorized transactions.
By highlighting these control deficiencies through formal management letters and audit committee reports, auditors provide organizations with actionable insights that extend far beyond compliance. The operational benefits derived from this process include:
Mitigating Operational Risks: Identifying procedural bottlenecks and systemic vulnerabilities allows organizations to patch security holes before they can be exploited by malicious actors or lead to costly operational failures.
Optimizing Resource Allocation: Operational audits evaluate whether resources are being utilized efficiently across departments, often uncovering redundancies, wasteful expenditures, or opportunities for process automation.
Enhancing Accountability: The knowledge that internal processes are subject to regular, independent review instills a culture of discipline and responsibility among employees at all organizational levels.
When internal controls are robust and continually refined through audit feedback, companies experience fewer surprises, greater operational resilience, and a significantly reduced risk of catastrophic loss, laying a solid foundation for sustainable growth.
Common auditing pitfalls and missteps
Auditing is designed to bring precision and clarity to financial oversight, yet the execution frequently falls victim to human error and flawed methodologies. When practitioners rely on rushed timelines or outdated frameworks, the resulting evaluations often miss critical misstatements. Understanding these vulnerabilities helps organizations tighten their internal controls and safeguard their financial integrity.
Overlooking substantive testing in favor of analytical procedures
Many audit teams place excessive trust in high-level analytical reviews while neglecting detailed substantive testing of individual transactions. Analytical procedures are helpful for spotting broad trends, but they can easily mask localized anomalies or deliberate fraud hidden deep within ledger entries.
The Risk: Routine fluctuations can camouflage illicit transfers if auditors fail to verify source documents.
The Prevention: Teams must pair trend analysis with rigorous sample-based verification of invoices, receipts, and bank statements.
The Reality: Skipping granular checks creates dangerous blind spots that leave organizations vulnerable to unexpected deficits.
Failing to maintain professional skepticism
A primary hazard in any review process is accepting management representations at face value without adequate independent corroboration. Auditors sometimes develop overly cozy relationships with client executives, which dulls their critical edge and encourages unwarranted complacency.
The Trap: Trusting verbal explanations from department heads instead of demanding verifiable physical or digital proof.
The Consequence: Material misstatements sail past inspection simply because nobody questioned the initial premise.
The Solution: Maintaining an objective, questioning mindset ensures that every financial assertion is backed by undeniable evidence.
Navigating complex regulatory shifts and emerging challenges
As financial reporting standards continue to evolve across global markets, compliance requirements demand constant vigilance from internal and external audit teams. Navigating these shifting guidelines requires more than a basic checklist; it calls for adaptive strategies that account for modern technological integrations.
Adapting to automated financial systems
The rapid adoption of enterprise resource planning software and automated ledger systems has transformed how transactions are recorded and tracked. Auditors who cling to legacy auditing techniques often struggle to evaluate complex digital workflows and automated control environments effectively.
The Challenge: Algorithms execute thousands of transactions per second, making manual sampling practically obsolete.
The Response: Professionals must master data analytics tools to interrogate entire populations of data rather than tiny random subsets.
The Outcome: Modernized testing uncovers systemic software errors and unauthorized access points that traditional reviews consistently miss.
Managing Resource constraints and tight deadlines
Budget limitations and aggressive reporting schedules frequently force audit teams to cut corners during critical phases of the review cycle. Rushing through inventory counts or peer reviews drastically increases the likelihood of overlooking vital compliance red flags.
The Impact: Superficial testing yields clean audit reports that fail to reflect the true financial health of the enterprise.
The Fix: Organizations must allocate sufficient time and specialized talent to ensure every high-risk area receives proper scrutiny.
The Bottom Line: Quality assurance suffers immensely when speed takes precedence over thoroughness and analytical depth.