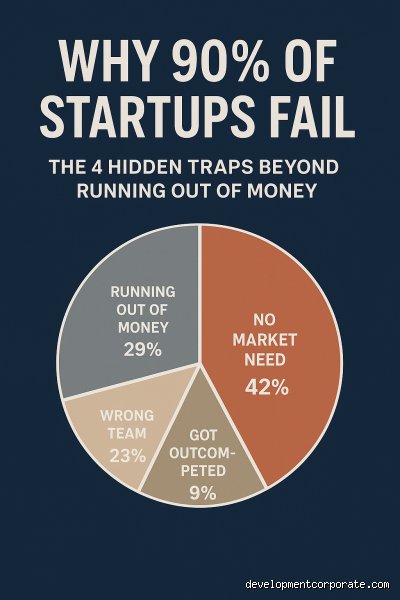
Every year, thousands of optimistic entrepreneurs watch their bank balances dwindle to nothing. Why? Because the math of growth is unforgiving. When you look at the landscape of modern tech ventures, cash is the oxygen that feeds the engine, and once that oxygen cuts out, the brain death of the organization happens in seconds. Yet, understanding this failure requires looking past the superficial explanations.
Beyond the burn rate: Defining what it means when the capital well runs dry
Let us strip away the Silicon Valley romanticism. When we analyze why do startups run out of money, we are talking about structural insolvency masked by temporary investor enthusiasm. It is not just about spending more than you make—almost every pre-revenue company does that. Operational burn rate must be weighed against the time it takes to hit the next valuation inflection point. If your runway is twelve months, but your product development cycle requires eighteen to yield any testable data, you are already technically dead; you just haven’t stopped breathing yet.
The dangerous illusion of the Post-Seed honeymoon
Congratulations, you raised 3 million dollars in San Francisco or London. What happens next? Historically, a dangerous complacency sets in. Founders look at a seven-figure bank balance and mistake a temporary capital cushion for permanent product-market fit. They scale the sales team before the product actually works smoothly. According to data tracking thousands of post-seed entities, over-hiring during this specific window increases the probability of terminal cash depletion by 60 percent. A massive bank account frequently degrades operational discipline, leading to a state where the company spends cash on vanity metrics rather than core survival.
The real meaning of Zero Date engineering
The tricky part is calculating the exact "Zero Date"—the precise calendar day the bank balance hits absolute zero. It sounds simple, right? Still, revenues are volatile and expenses have a weird way of compounding unexpectedly. Founders often map out linear projections on spreadsheets, assuming their SaaS subscriptions or e-commerce transactions will grow by a predictable 15% month-over-month. But real life is lumpy. A single delayed enterprise contract or a sudden spike in cloud infrastructure costs can pull that Zero Date forward by an entire quarter, catching the board completely off guard.
The false promised land of Product-Market fit and scalability traps
Here is my sharp opinion on this whole mess: most startups do not die from starvation; they die from indigestion. They try to swallow a massive market before they can even chew their local niche. The traditional playbook tells you to move fast and break things, which is fine, until you break your own balance sheet. But wait, is fast scaling always a trap? There's no consensus on the exact threshold, and it's unclear where the line between bold expansion and reckless spending truly lies. Some companies pull off massive customer acquisition gambles, while others sink beneath the weight of unoptimized unit economics.
Premature scaling: The silent company killer
Look at the spectacular collapse of Fast, the online checkout startup that shut down in April 2022. They were burning through an estimated 10 million dollars a month while bringing in mere fractions of that in actual revenue. They hired hundreds of engineers. For what? To build a product that the market wasn’t ready to adopt at that scale. That matters most when you realize that your customer acquisition cost outpaces the lifetime value of that customer by a factor of five. When capital was practically free back in 2021, you could hide those flaws. Today, the market demands efficiency, and premature scaling is an instant ticket to the corporate graveyard.
The misleading signals of early pilot traction
We’ve all seen it happen. A enterprise software company lands two pilot projects with Fortune 500 brands in New York. The founders celebrate, assuming this means global validation. They immediately lease a fancier office and bump up executive salaries. Huge mistake. Those pilots were likely funded by innovation budgets, money large corporations throw away just to look progressive. Because these pilots rarely convert into recurring, multi-year production contracts, the startup is left with massive overhead and zero sustainable cash flow. The problem is that a warm introduction is not a signed invoice.
Customer acquisition cost versus Long-Term value disconnect
The math behind why do startups run out of money often boils down to a broken unit economic ratio. If it costs you 150 dollars in Google Ads to acquire a subscriber who drops off after three months, yielding only 45 dollars in total revenue, your business model is essentially an expensive charity. You are subsidizing your users' lives with venture capital. And as a result: the faster you grow, the more money you lose. This dynamic creates a terrifying spiral where scaling up actually accelerates the date of bankruptcy rather than deferring it.
The sudden death of external financing and the term sheet mirage
Relying on the next funding round to save your skin is a statistical form of Russian roulette. The funding environment can shift overnight, driven by interest rate hikes or geopolitical instability far outside your control. When the venture capital spigot turns off, the companies that treated fundraising as a milestone rather than a bridge find themselves stranded without a life jacket.
The myth of the guaranteed Follow-On round
Many founders operate under the delusion that their existing investors will always bail them out with an emergency bridge loan. That is rarely how VC psychology works. If an investment firm senses that a portfolio company is a sinking ship with bad internal metrics, they will ruthlessly cut their losses to protect their remaining fund capital. In 2023, insider-led down rounds and flat extensions plummeted as institutional backers chose to let underperforming bets dissolve entirely. Your cap table is full of allies during a bull market, yet those allies vanish when the numbers turn ugly.
The anatomy of a collapsed Series a bridge
Consider a tech venture that needs to raise its Series A within four months. They have sixty days of cash left. They are deep in talks with three venture funds, and things look promising. But then, a macroeconomic tremor hits, or one of the fund's major limited partners defaults on a capital call. Suddenly, those verbal commitments evaporate. Because the founders didn't maintain a six-month emergency cash buffer, they have no time to pivot, no leverage to negotiate, and absolutely no way to make next month's payroll. Because of that, the company folds despite having an innovative product and genuine user love.
Monetization delays vs. Capital accumulation dynamics
To truly grasp why do startups run out of money, we have to look at the structural differences between business models. Some industries are inherently more capital-intensive, meaning their relationship with cash is fundamentally different from a standard software venture. It is a game of managing cash conversion cycles, and some sectors play it on hardest difficulty.
Biotech and deep tech: The Multi-Year Pre-Revenue desert
Take a hard tech venture developing advanced robotics in Boston or a biotech firm working on gene therapies. Unlike a mobile app developer who can launch a buggy MVP in two weeks, these deep tech firms must spend millions of dollars on lab space, regulatory compliance, and specialized hardware before making a single dime. Their capital runway isn't just a safety net; it is the entire runway required to launch the rocket. If a clinical trial gets delayed by six months due to a bureaucratic hiccup, millions in capital evaporate without any corresponding progress, forcing the company into liquidation before the science can even prove itself.
SaaS and marketplaces: The illusion of low capital requirements
Conversely, look at software-as-a-service or digital marketplace platforms. On paper, they look cheap to run. No factories, no heavy machinery, just code and servers. But the modern software landscape is incredibly crowded. To stand out above the noise, these companies must spend fortunes on performance marketing and engineering talent. We're far from the days when a couple of kids in a garage could scale a global software platform for pennies. The hidden capital drain here is churn; if your monthly user cancellation rate hovers above 5%, you are constantly pouring expensive fuel into a leaky bucket, leading to a slow-motion financial collapse that sneaks up on management.
Common mistakes and dangerous misconceptions
The premise fallacy: Building before validating
You think your genius blueprint guarantees a line of eager buyers outside your digital storefront. It does not. The problem is that founders conflate enthusiastic feedback from friends with genuine market demand. They pour their initial capital into engineering a polished, flawless product before securing a single dollar of committed revenue.
Coding a complex feature set costs real cash, while assumptions cost nothing until they break your business model. We witnessed this exact catastrophe with the high-profile failure of Quibi, which burned through 1.75 billion dollars because the leadership assumed premium short-form content was what mobile users craved. It was a massive hallucination. They built a cathedral in the desert, and nobody showed up to pray.
The scaling trap: Growing painfully early
Premature scaling will suffocate your venture faster than a bad pitch deck. Why do startups run out of money? Because they hire bloated enterprise sales teams and launch massive marketing campaigns before achieving true product-market fit. Startup Genome data reveals that 74% of high-growth internet startups fail due to premature scaling, making it the absolute number one cause of premature death in the ecosystem. You cannot solve a retention problem by shoving more expensive, acquired users into a leaky bucket. The unit economics simply collapse. Yet founders keep buying Super Bowl ads and renting glass offices in San Francisco when they should be hyper-focused on fixing their core product retention metrics.The infinite runway delusion
We frequently talk to founders who treat their seed round like an infinite piggy bank. They calculate their runway mathematically by dividing their total bank balance by their current monthly burn rate, arriving at a comforting eighteen-month window. Still, this calculation completely ignores the reality of variable operational spikes and the massive time lag required to close a subsequent venture round.
Fundraising does not happen over a long weekend. It is a grueling four-to-six-month distraction that completely paralyzes the operational velocity of the executive team. If your bank account says you have six months of oxygen left, the reality is that your business is already on life support.
The hidden cash bleed: Cap table negligence
The phantom costs of improper equity architecture
Everyone worries about AWS bills and marketing spend. But have you ever analyzed the devastating financial drag of a broken cap table? When early founders hand out 20% of their equity to a co-founder who leaves after six months without a vesting schedule, they create a toxic corporate structure.
Future institutional investors will look at that dead equity weight and simply walk away from the deal. The upshot: the company becomes completely un-investable. You are then forced to use precious operational cash to buy back those shares or execute a messy, expensive corporate recapitalization. Legal fees for fixing a botched corporate structure can easily climb past 50,000 dollars, money that should have been spent on acquiring customers.
The dangerous illusion of venture debt
Venture debt looks incredibly attractive to founders who want to avoid diluting their ownership stakes. It feels like cheap capital, right? It is a trap for the unprepared.
Venture debt providers include strict material adverse change clauses and aggressive repayment schedules that trigger the moment your growth slows down even slightly. When your revenue misses projections for two consecutive quarters, these lenders can instantly seize your bank accounts. It turns a temporary operational bump into a sudden, catastrophic liquidation event.
Frequently Asked Questions about startup insolvency
What percentage of new ventures collapse due to capital depletion?
The statistical landscape for early-stage companies is notoriously brutal. According to extensive research conducted by CB Insights across hundreds of post-mortem essays, 38% of failing startups explicitly cite running out of cash as the primary reason for their ultimate demise. This makes capital depletion the single most common cause of corporate mortality, surpassing even the failure to find market need which sits at 35%. The remaining cohort typically succumbs to fierce competition, flawed team dynamics, or unoptimized pricing strategies. In short, nearly four out of ten entrepreneurs will watch their dreams vanish simply because the bank account hit zero before the business model could successfully scale.How do macroeconomic shifts impact early-stage funding availability?
When central banks aggressively raise interest rates, the entire venture capital landscape undergoes a dramatic paradigm shift. Limited partners pull their capital out of risky tech funds and relocate it into safer, high-yielding fixed-income assets. This shift explains why global venture funding plummeted by 42% in a recent cyclical downturn, forcing companies to survive on whatever cash they had on hand. Investors suddenly stop prioritizing raw user growth and instead demand immediate profitability and sustainable unit economics from founders. Consequently, businesses that rely on continuous external capital injections to fund their daily operations find themselves completely stranded in a frozen funding environment.
When should a founder realistically begin planning their next fundraising round?
You must initiate the fundraising process at least six months before your current cash reserves are projected to hit zero. This timeline accounts for the two months required to build a comprehensive investor pipeline, another two months for rigorous due diligence, and a final sixty days for legal documentation and wire transfers. Waiting until you have ninety days of runway remaining signals desperation to seasoned investors, which completely destroys your negotiating leverage. But what happens if you cannot secure commitments within that window? You are forced to accept highly predatory terms, structured bridge notes, or face immediate liquidation.
A brutal reality check for the modern entrepreneur
Building a venture-backed company is an exercise in managing a ticking time bomb, not an open-ended invitation to romanticize the hustle. The ecosystem is littered with the corpses of brilliant products that simply ran out of time because the leadership confused fundraising milestones with actual business validation. Capital is not validation; it is merely high-octane fuel for an engine you are still actively building in mid-air. If your core unit economics do not make sense at a small scale, multiplying your user base with venture dollars will only accelerate your demise. Stop obsessing over your valuation and start obsessing over your net cash flow. Survival is the ultimate metric in this game, and the winners are simply the ones who refuse to let their bank accounts hit zero before reality catches up to their vision.