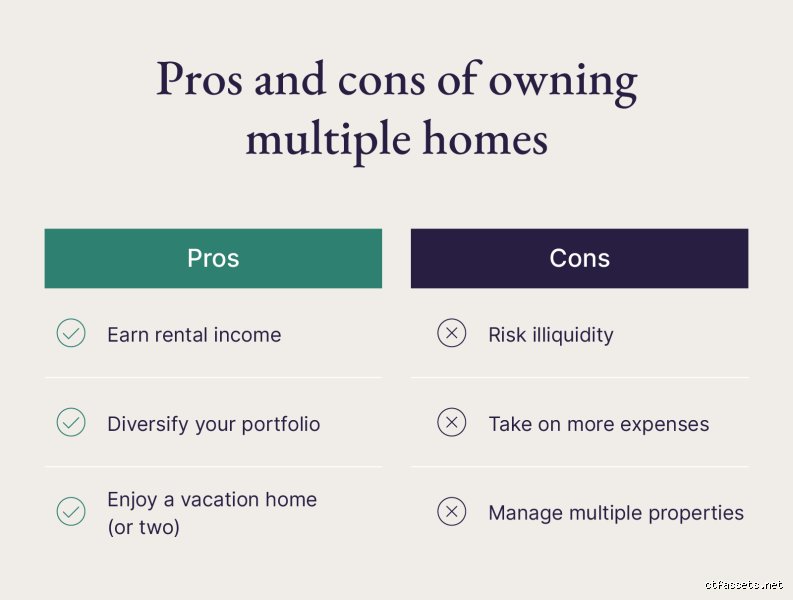
The legal and structural reality of multiple property ownership
Let's clear up the foundational landscape first because people tend to overlook this before browsing listing sites. In jurisdictions like the United States, Canada, and the United Kingdom, the state does not care if you own one house or a portfolio of fifty-two distinct residential units. Property rights protect your freedom to accumulate assets, provided you have the capital to back it up. Yet, the distinction between owning a primary residence and acquiring a secondary asset is where everything shifts on its axis.
The critical line between secondary homes and investment assets
Lenders view a second home—say, a quiet cabin in Aspen where you spend your winter holidays, very differently than a duplex in downtown Chicago meant to generate monthly rental checks. Occupancy intent dictates your underwriting rules, which matters a lot. If you lie on a mortgage application, claiming a property is a personal vacation home when you actually plan to list it on short-term rental platforms immediately, you are committing bank fraud. It is that simple. I have seen amateur investors get blacklisted by major financial institutions because they thought they could outsmart underwriting teams with a wink and a nod. It's unclear why so many online gurus still preach these shortcuts when the legal risks are so catastrophically high.
Localized barriers and hidden municipal roadblocks
But what about municipal pushback? Cities worldwide are fighting severe housing shortages, and their primary weapon is aggressive local legislation. If you are eyeing a seaside condo in Miami or a historic townhouse in New Orleans, you have to look beyond federal laws. Local ordinances might completely ban short-term rentals, or perhaps they slap a 10% annual surcharge on vacant properties. You might technically have the legal right to purchase the deed, yet the municipality can make it functionally impossible to operate the home profitably.
The financing maze: How banks grade Multiple-Property borrowers
This is where things get complicated for the average buyer. Getting a mortgage for your first home is a relatively predictable process involving your credit score and standard debt-to-income ratios. But when you walk into a bank asking for loan number two, three, or four? The scrutiny intensifies exponentially.
The escalating Debt-to-Income challenge
Banks do not just look at your income; they obsess over your liquidity and risk exposure. For a primary residence, you might slip by with a 3.5% down payment via an FHA loan. Try that on an investment property, and the loan officer will laugh you out of the room. You will need a minimum of 20% to 25% down for a second property, and that cash must be fully seasoned in your account. Why? Because lenders know that when a financial crisis hits, individuals protect their primary roof first and let their investment properties slide into foreclosure.
The 75% rental Income rule and cash reserve mandates
Can you use projected rent to qualify for the new mortgage? Yes, but with a massive catch. Most conventional guidelines, including those from Fannie Mae, only allow you to count 75% of the projected rental income toward your qualifying debt ratios to account for inevitable vacancies and maintenance. The bank will likely demand that you hold six months of principal, interest, taxes, and insurance reserves for *each* property you own. If you have four homes, that is twenty-four months of housing payments sitting idle in a savings account. That requirement drains your liquid capital faster than most people anticipate.
The hard wall: When conventional financing cuts you off
And then you hit the structural ceiling. Conventional lenders typically max out at ten financed properties per individual borrower. Once you reach that eleventh property, you enter the shadow realm of portfolio lenders, commercial financing, and blanket mortgages. These products come with higher interest rates, often 1.5% to 3% above standard residential rates, and shorter amortization windows, which radically alters your cash flow calculations.
Tax implications that can make or break a portfolio
Governments love to tax real estate, but they love taxing multiple property owners even more. The moment you step outside your primary residence, the tax code transforms from a supportive friend into a ruthless auditor.
The loss of capital gains protections
Consider the Section 121 exclusion in the United States. It allows an individual to exclude up to $250,000 of capital gains ($500,000 for married couples) when selling a primary home, provided they lived there for two of the last five years. But for an investment property? You get zero exclusion. If you bought a rental property in Austin back in 2018 for $300,000 and sell it today for $600,000, you owe capital gains tax on that entire $300,000 profit, unless you execute a complex 1031 exchange to defer the hit.
The nightmare of depreciation recapture
But wait, it gets worse. While you own an investment property, the IRS forces you to write off the structure's value over a 27.5-year lifespan. This depreciation deduction is great for reducing your annual income tax liability. The catch: when you sell, the government executes what is known as depreciation recapture at a flat 25% rate. They essentially claw back the tax breaks they gave you over the years, which catches unprepared investors completely off guard.
Strategic alternatives to direct scaling
Is buying individual houses one by one actually the smartest way to scale your wealth? Experts disagree on this point constantly. Some investors swear by residential accumulation, while others argue that owning ten separate single-family homes is an operational nightmare compared to consolidated commercial real estate.
The Single-Family scatter versus multifamily consolidation
Imagine managing ten roofs, ten separate HVAC systems, and ten different sets of neighbors spread across a metro area. The logistical friction is immense. Contrast that with purchasing a single 10-unit apartment building. You have one roof to maintain, one commercial loan to service, and a centralized location for property managers. The problem is that multifamily assets require a completely different underwriting process based on the building’s Net Operating Income rather than your personal salary, which means the barrier to entry is significantly higher for beginners.
Common mistakes and dangerous blind spots
The illusion of passive income
Many novice investors buy into the myth of effortless wealth. You purchase a second home, find a tenant, and watch the cash roll in, right? Wrong. The problem is that property management is practically a second job. Maintenance costs invariably eat into your margins, typically devouring 15% of your gross rental income annually. Roofs leak. Water heaters fail at 3 a.m. If you fail to account for these unavoidable outlays, your profitable venture quickly mutates into a cash-draining nightmare.
The geometric trap of leverage
Debt is a magnificent amplifier, yet it cuts both ways. Buyers frequently assume that securing a second mortgage is identical to getting the first. Lenders view multiple liabilities through a magnifying glass of skepticism. They will scrutinize your debt-to-income ratio, demanding that your total monthly obligations consume less than 43% of your gross earnings. If a tenant vacates, you are suddenly saddled with two mortgages. Can you sustain that financial bleeding for six months? Most cannot, which explains the sudden spikes in forced liquidations during economic downturns.
Neglecting the entity structure
Purchasing multiple assets in your personal name is a structural blunder. Why risk your personal savings because a tenant tripped on a loose floorboard? Failing to utilize a Limited Liability Company (LLC) or a specialized trust leaves your entire net worth exposed to litigation. And let's face it, human beings love to sue when they perceive deep pockets.
The hidden structural arbitrage: Cross-collateralization
Turning existing brick into liquid leverage
Can I own more than one property without deploying massive mountains of cold cash? This is where seasoned investors separate themselves from the amateurs. Instead of saving for years to secure a traditional 20% down payment, you can leverage the dormant equity in your primary residence.
The mechanics of the equity bridge
If your current home is valued at $500,000 and your remaining mortgage is only $200,000, you are sitting on a goldmine of $300,000 in raw equity. Lenders will readily allow you to borrow up to 80% of that appraised value via a home equity line of credit (HELOC). This becomes your liquidity engine. You deploy that borrowed equity as a down payment on a duplex, effectively expanding your portfolio using money that only existed on paper. But what happens if the broader market takes a 10% dip? Your leverage can trap you underwater, a reality that aggressive gurus conveniently forget to mention in their glossy seminars.
Frequently asked questions
Is there a hard legal limit on how many mortgages one person can hold?
No statutory law restricts the absolute number of titles you can hold, but conventional financing structures impose rigid boundaries. Fannie Mae and Freddie Mac cap the maximum number of financed properties at exactly ten loans per individual investor. Once you cross this specific double-digit threshold, traditional banks will summarily reject your applications regardless of your pristine credit score. You must then pivot to commercial portfolio lenders or private money networks, which typically demand steeper interest rates hovering 2% to 3% above standard market averages. Consequently, expanding your footprint beyond this ceiling requires a total overhaul of your capital acquisition strategy.How does buying a second property impact my annual tax obligations?
The tax landscape shifts dramatically the moment you sign the deed on a secondary asset. If the property functions strictly as a rental, the IRS obligates you to declare all rental revenues, yet it simultaneously unlocks powerful depreciation deductions over a 27.5-year schedule. However, if you purchase a personal vacation home that you occupy for more than 14 days annually, you lose the ability to deduct standard rental operating losses against your ordinary income. Local municipalities frequently impose a surcharge on non-primary residences, sometimes inflating your annual property tax bill by an astonishing 50% compared to your primary home.Can I use projected rental income to qualify for a new acquisition mortgage?
Lenders are surprisingly accommodating here, though they will never take your optimistic word at face value. You can absolutely utilize the anticipated rent from the target property to bolster your qualifying income, but underwriters will automatically apply a standard 25% vacancy haircut to the projected figures. This means if a certified appraiser estimates the market rent at $2,000 per month, the bank will only credit $1,500 toward your debt-to-income calculations. Because of this strict discounting mechanism, you cannot rely entirely on the future tenant to bail out a weak personal financial profile during the rigorous underwriting process.The reality of scaling your portfolio
Amassing multiple pieces of real estate is not a game of simple addition; it is an exercise in complex compounding risk. We live in an era where everyone craves the status symbol of a vast portfolio, but the ultimate victor is the investor who prioritizes cash flow velocity over raw square footage. Yield is king, whereas mere asset accumulation is nothing more than an expensive vanity project. Do you actually possess the psychological fortitude to manage multiple volatile assets when the macroeconomic indicators turn sour? If you do, the rewards are unmatched. Invest aggressively, structure defensively, and never let your ambition outpace your liquid reserves.