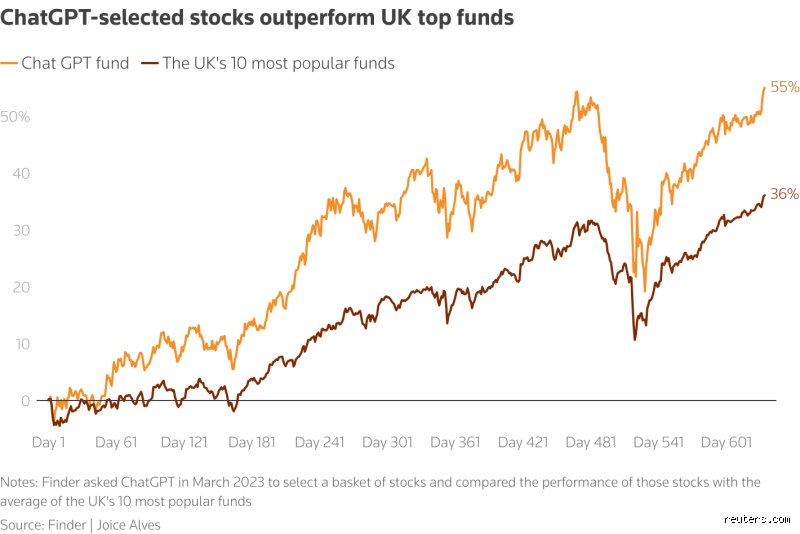
For decades, stock selection was considered the exclusive domain of human portfolio managers, Wall Street analysts, and complex proprietary algorithms running behind closed doors at elite hedge funds. Yet, recent academic studies, live experimental portfolios, and backtesting contests have consistently thrown a wrench into traditional assumptions. While some controlled experiments show language models capturing unexpected market sentiment and generating positive alpha, others warn that treating a text-generation engine as an oracle is a dangerous financial gamble.
To understand whether ChatGPT can pick stocks, we must look past the viral headlines and examine the architecture of large language models, the nature of market efficiency, and what the data actually reveals about AI-driven portfolio performance.
1. The core mechanism: How language models "analyze" Markets
To evaluate whether a chatbot can pick stocks, it is essential to first understand what ChatGPT is—and just as importantly, what it is not. ChatGPT is fundamentally a probabilistic language model trained to predict the next token in a sequence based on vast amounts of text data. It does not possess consciousness, financial intuition, or proprietary economic foresight.
So, how does it process a financial statement or earnings report?
Pattern Recognition over Computational Modeling: Traditional algorithmic trading relies on quantitative formulas, regression models, and direct mathematical inputs. In contrast, an LLM ingests text—ranging from SEC filings and earnings call transcripts to financial news articles and macroeconomic commentary, and identifies linguistic patterns.
Sentiment Synthesis at Scale: One of ChatGPT’s strongest capabilities is qualitative aggregation. If a company's earnings release contains subtle shifts in executive tone, or if thousands of news pieces express growing anxiety over a supply chain disruption, an LLM can parse that unstructured text far faster than a human reader.
Top-Down and Bottom-Up Prompting: When tasked with building a portfolio, models typically adopt a structured framework. They often begin with a top-down macroeconomic assessment (evaluating interest rates, inflation trends, and sector rotations) before narrowing down to specific corporate balance sheets and qualitative market positioning.
However, this text-based foundation introduces a structural vulnerability: language models optimize for plausible coherence, not verified numerical ground truth.
2. What the empirical research shows
Academic inquiry into LLM stock-picking capabilities has evolved rapidly. Early experiments focused on headline sentiment analysis. For instance, landmark academic papers tested whether ChatGPT could determine if Federal Reserve announcements or corporate news headlines implied "good" or "bad" news for specific equities.
The findings were striking:
Statistical Predictive Power: Researchers found that ChatGPT exhibited statistically significant predictive power regarding short-term daily stock price movements based on news sentiment alone, frequently outperforming traditional, rigid lexicon-based sentiment analysis tools.
Earnings Surprise Adaptation: Subsequent studies analyzing performance around quarterly earnings announcements revealed that models could adjust their "attractiveness ratings" for specific stocks in a timely fashion when fed fresh earnings data, leading to positive returns in controlled subsets.
Simulated Portfolio Contests: In various long-term public tracking experiments, simulated portfolios curated by LLMs have occasionally posted eye-catching gains, sometimes outpacing broad benchmarks like the S&P 500 over short-to-medium horizons. These portfolios frequently lean heavily into high-momentum sectors, such as semiconductor infrastructure and artificial intelligence hardware suppliers, riding structural bull trends.
Yet, financial researchers are quick to urge caution. Outperforming a benchmark over a few months or quarters during a secular bull market does not prove a robust, repeatable investment methodology.
3. The structural limitations of using general AI for finance
Despite impressive demonstrations, relying on a general-purpose conversational chatbot for investment decisions runs headfirst into severe structural hurdles:
| Limitation | Why It Matters in Markets |
|---|---|
| The Knowledge Cutoff vs. Real-Time Reality | Financial markets update by the millisecond. A model relying on static training data or delayed web retrieval may base multi-thousand-dollar decisions on stale metrics. |
| Hallucination and Fabrication | LLMs are structurally prone to generating fluent falsehoods. If a model misquotes a company's Price-to-Earnings (P/E) ratio or invents a fictional debt figure with absolute confidence, an unwary investor could base a trade on corrupted data. |
| The Absence of Fiduciary Risk Management | ChatGPT does not feel the sting of a loss. It lacks built-in risk modeling, stop-loss discipline, or portfolio rebalancing math unless explicitly constrained by human-coded rules and parameters. |
As financial analysts frequently note, a model that is "fluent first and factual second" is fundamentally misaligned with an industry where precision and verification dictate survival.
Synthesizing AI-Driven asset allocation: Backtests, behavioral biases, and Real-World limitations
To truly understand whether large language models can deal with stock selection, we must look beyond academic text-prediction benchmarks and examine how these systems behave when tasked with executing systematic multi-factor portfolios. While early headline-sentiment experiments demonstrated that models like GPT-4 could capture immediate market underreactions to news items, long-horizon empirical testing reveals a far more nuanced reality.
Quantitative performance and empirical realities
When researchers subject automated language model portfolios to rigorous backtesting frameworks over multi-year windows and diversified stock universes, several distinct patterns emerge:
The Large-Growth Bias: Language models consistently tilt toward mega-cap technology and healthcare equities. Because these companies generate massive volumes of financial news, research reports, and digital commentary, they occupy an oversized footprint in the model's training data. Consequently, AI portfolios often mimic a momentum-heavy growth index rather than uncovering hidden value.
Regime Vulnerability: Market regime analyses highlight that AI investment strategies can be overly conservative during blistering bull markets, lagging passive indexing benchmarks, while occasionally failing to implement dynamic, risk-off liquidity preservation during severe market contractions.
Absence of Proprietary Edge: Factor regressions against standard asset-pricing models (such as the Fama-French multi-factor frameworks) indicate that returns generated by general-purpose language models rarely exhibit statistically significant alpha on a risk-adjusted basis. The returns are largely explained by traditional risk exposures (size, value, and market beta) rather than superior predictive insight.
The structural pitfalls of automated stock picking
| Limitation | Impact on Portfolio Construction | Why It Occurs |
|---|---|---|
| Context Window & Memory Constraints | Inability to track a holistic, evolving portfolio history across dozens of equities without manual re-entry. | Stateless architecture requires explicit context reloading, leading to fragmented asset oversight. |
| Hallucination of Financial Metrics | Generating plausible-sounding numeric targets, P/E ratios, or cash flows that bear no resemblance to audited filings. | Autoregressive models optimize for token plausibility rather than mathematical truth. |
| Lack of Liquidity & Slippage Awareness | Recommending positions in thinly traded small-cap stocks where entering or exiting a position would trigger massive market impact. | Text models process company descriptions textually without modeling order-book depth or execution friction. |
The verdict: Tool vs. Oracle
Treating ChatGPT or any general-purpose language model as an autonomous oracle for stock picking misunderstands both the mechanics of modern market pricing and the architecture of neural networks. Markets are hyper-efficient discounting mechanisms shaped by institutional liquidity, macroeconomic shocks, and game-theoretic competition.
An LLM does not possess an internal economic agent capable of feeling fear, assessing geopolitical tail risks, or executing due diligence. Instead, it functions as a high-speed linguistic aggregator, capable of summarizing dense 10-K filings, outlining competitive landscapes, and structuring pro-and-con lists in seconds.
For individual investors, the winning strategy is not handing the keys of a portfolio over to a prompt box, but rather utilizing AI as a cognitive assistant: an instrument to parse unstructured financial data, accelerate fundamental research, and stress-test investment theses against blind spots.
Where would you like to explore next?