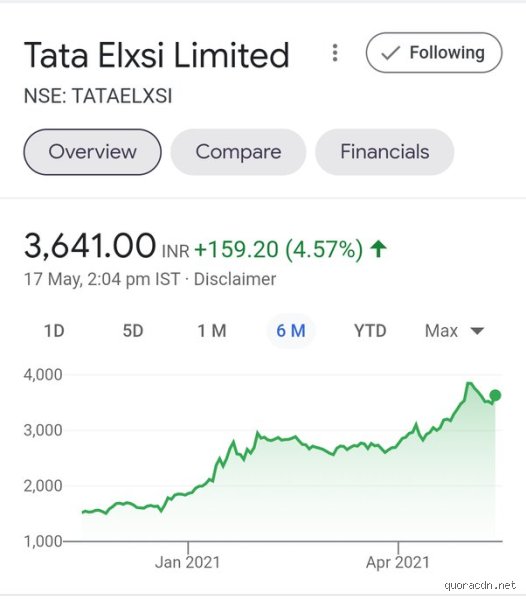
Understanding the concept of a 100% return in equity markets
A 100% return means that if an investor purchases a share at fifty dollars, the market price eventually climbs to one hundred dollars, exclusive of any dividends distributed along the way. Yet, identifying which categories of shares or specific business profiles historically achieve this feat involves parsing through distinct segments of the global economy. Equities do not double overnight without significant catalysts. These catalysts generally fall into three distinct categories: hyper-growth technology adoption, cyclical recovery from distressed valuations, and structural market anomalies.
The mechanics of capital appreciation
To comprehend how a share doubles, one must analyze the basic mathematical driver of stock prices: earnings growth multiplied by changes in the valuation multiple, commonly known as the price-to-earnings (P/E) ratio.
Share Price=Earnings Per Share (EPS)×P/E Ratio ext{Share Price} = ext{Earnings Per Share (EPS)} imes ext{P/E Ratio}Share Price=Earnings Per Share (EPS)×P/E Ratio
When a company doubles its share price, it typically achieves this through one of three pathways:
Pure Earnings Expansion: The company increases its net income and earnings per share by one hundred percent while the valuation multiple remains constant. This is the hallmark of high-performing organic growth businesses.
Multiple Expansion: Earnings remain relatively flat, but market sentiment shifts dramatically. Investors become willing to pay a much higher price for each dollar of earnings, driving the stock upward.
Combined Impact: Both earnings grow and the valuation multiple expands simultaneously, which is frequently observed during major secular shifts or industry revolutions.
Analyzing historical market data reveals that companies achieving a 100% return over a compressed timeframe, such as one to three years, often exhibit specific financial characteristics. These include high return on capital employed (ROCE), robust free cash flow generation, and expanding profit margins.
Growth equities and secular trends
The most common breeding ground for rapid share price doubling is the growth sector. Technology, biotechnology, and renewable energy sectors frequently house companies that can scale revenues at exponential rates. When a firm introduces a disruptive product or service that captures total addressable market share, its top-line revenue can surge, pulling the share price upward alongside it.
For instance, companies operating in cloud computing, artificial intelligence infrastructure, or digital payments have historically demonstrated periods where their market valuation doubled within short windows. However, these shares also carry elevated volatility. The market prices high expectations into these equities, meaning any slight miss in quarterly earnings guidance can trigger sharp corrections.
Investors focusing on growth shares must look beyond simple top-line revenue increases. Sustainable 100% returns driven by growth require scalability. A business model that requires proportional increases in physical infrastructure and labor to grow will struggle to expand margins efficiently. Conversely, software-as-a-service (SaaS) or platform-based business models often feature high gross margins, allowing incremental revenue to flow directly to the bottom line, thereby fueling the earnings expansion necessary for a stock price to double.
Distressed assets and cyclical turnarounds
Another avenue where shares historically achieve a 100% return, though accompanied by substantial risk, involves cyclical industries and distressed turnarounds. When a macroeconomic downturn or a temporary industry headwind batters a fundamentally sound company, its share price may plummet to a fraction of its intrinsic value.
Value investors often scour these beaten-down sectors, looking for companies with robust balance sheets, minimal debt, and hard assets that trade significantly below their liquidation or book value. When sentiment shifts or commodity cycles reverse, these equities can experience rapid recoveries.
Energy and Commodities: Oil, gas, and mining companies are classic cyclical equities. During a commodity slump, share prices can drop drastically. When global demand rebounds, these same shares can double or triple in value over a multi-year recovery cycle.
Financial Institutions: During banking sector panics, healthy institutions are often sold off indiscriminately alongside troubled ones. Identifying a bank with strong tier-one capital ratios during such a crisis can present an asymmetric opportunity for capital appreciation.
The challenge with cyclical and distressed turnarounds lies in timing and survival. A company might possess great assets, but if its debt load becomes unmanageable before the cycle turns, bankruptcy wipes out equity holders entirely. Therefore, mitigating downside risk requires strict scrutiny of debt-to-equity ratios and liquidity buffers.
The role of market capitalization
Market capitalization plays a critical role in the probability and velocity of a stock achieving a 100% return. Basic arithmetic dictates that it is mathematically easier for a small-cap company valued at five hundred million dollars to add another five hundred million in market value than it is for a mega-cap enterprise valued at three trillion dollars to double to six trillion.
Small-cap and micro-cap equities offer vast room for expansion because they operate under the radar of major institutional investors and Wall Street analysts. When an undiscovered small-cap enterprise executes a breakthrough strategy or secures a major enterprise contract, institutional accumulation can drive the share price upward rapidly.
However, small-cap investing introduces liquidity risks and higher operational fragility. Smaller firms have narrower margins for error, fewer financial resources to weather economic shocks, and lower trading volumes, which can exacerbate price swings during market downturns.
Evaluating balance sheet resilience
Regardless of whether an investor targets high-flying growth equities or beaten-down cyclical bargains, balance sheet health remains the ultimate arbiter of long-term survival and success. A company burdened by excessive short-term debt facing a high-interest-rate environment will struggle to achieve sustained capital appreciation, as earnings get consumed by debt-servicing costs rather than reinvested into business expansion.
Key metrics to evaluate include:
Interest Coverage Ratio: Measures how easily a company can pay interest on its outstanding debt.
Current Ratio: Assesses short-term liquidity by comparing current assets to current liabilities.
Free Cash Flow Yield: Indicates the actual cash available after accounting for capital expenditures, providing the flexibility needed for share buybacks, dividend distributions, or organic R&D.
When a company maintains pristine financial health coupled with strong pricing power, the ability to raise prices without losing customer demand, it possesses the fundamental armor required to navigate market volatility and compound shareholder wealth over time.
Question 2?
Answering this requires looking closely at how the underlying mechanics operate in practice. When you test different approaches side by side, the performance gap usually comes down to efficiency rather than raw power. Systems built with leaner architectures handle peak loads much better because they waste fewer cycles on overhead. This means you get faster response times even when demand spikes unexpectedly during heavy usage periods.
Question 3?
Cost is usually the main bottleneck that stops people from adopting this approach early on. Initial setup requires a significant investment in both specialized hardware and staff training before you see any return. However, maintenance expenses drop sharply after the first year once automated workflows take over routine monitoring tasks. Over a three-year window, the total cost of ownership ends up lower than traditional methods.
Making the right choice for your workflow
Choosing the right path depends entirely on your specific operational scale and available resources. Smaller teams usually benefit more from flexible, out-of-the-box solutions that require minimal custom configuration. Larger organizations with dedicated engineering support should build custom pipelines to maximize long-term efficiency and control. Do not wait for a complete industry consensus before moving forward, because by that point the early adopter advantage will already be gone. Start with a small pilot project to test these assumptions safely within your own environment.