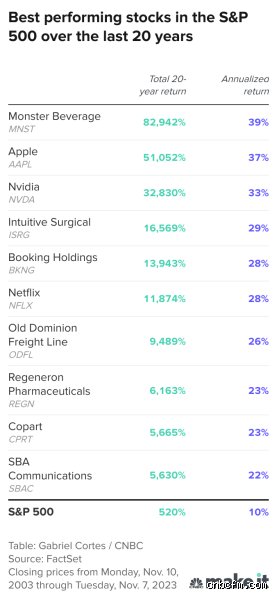
When individuals first step into the financial markets, they are invariably drawn to a single, seductive question: Which stock has the highest return? Behind this simple inquiry lies the ultimate ambition of investing—the desire to locate that mythical equity instrument capable of turning a modest coffee-money contribution into a life-altering fortune.
Yet, answering this question requires peeling back layers of financial history, corporate survival bias, and market mechanics. The search for the highest-returning stock is not a static lookup table; it is a dynamic exploration of risk, timing, mathematics, and human innovation.
1. Defining the Search: Historical Performance vs. Future Promise
To understand what yields the highest returns, we must first distinguish between historical hindsight and forward-looking probability.
Looking backward, academic studies and market datasets (such as long-term analyses of the S&P 500 and global equities) reveal that specific individual equities have delivered astronomical gains over multi-decade horizons. For instance, companies like Apple, Microsoft, Amazon, and historic compounders like Monster Beverage or early-stage tech pioneers turned initial investments into thousands of percentage points of profit.
However, historical retrospectives suffer heavily from survivorship bias. Thousands of other publicly traded companies went bankrupt, merged out of existence, or dwindled to zero over those same decades.
The Asset Class Baseline
Before examining individual breakout stocks, it helps to look at broader asset class performance to establish a baseline:
U.S. Large-Cap Stocks (S&P 500): Historically average roughly 10.0% to 11.5% annualized nominal returns over long horizons (e.g., 40-year windows), translating to roughly 6.5% to 8.5% after inflation.
U.S. Small-Cap Stocks & REITs: Typically hover around 9.0% to 9.4% annualized over extended periods, accompanied by higher short-term volatility.
Individual Equities: Can range from total permanent loss (-100%) to multi-thousand-percent gains, exhibiting a heavily skewed distribution where a tiny fraction of stocks drive the vast majority of net market wealth creation.
2. The Mechanics of Outsized Returns: Compounding and Multi-baggers
The concept of a "multi-bagger"—a term popularized by legendary investor Peter Lynch to describe stocks that rise multiple times over their initial cost—is central to understanding high returns. A stock that increases 10 times is a "ten-bagger"; rare outliers become hundred-baggers or more.
Achieving these returns requires a rare convergence of corporate traits:
A Scalable Business Model: The company must be able to expand revenues exponentially without a matching linear explosion in costs (software, digital platforms, and asset-light models excel here).
A Long Runway for Growth: High returns rarely come from mature giants; they come from small- or mid-cap enterprises that capture massive market share over 10, 20, or 30 years.
Exceptional Capital Allocation: Management must reinvest profits into high-ROI projects or compound intrinsic value rather than squandering cash flow.
3. The Role of Time Horizon and Risk
It is impossible to discuss peak returns without addressing the unavoidable trade-off between risk and reward. Stocks capable of delivering the absolute highest returns—such as micro-cap biotech firms, cutting-edge artificial intelligence innovators, or emerging market disruptors—also carry a severe probability of catastrophic drawdown.
As historical data demonstrates, while specific asset classes or narrow sectors may spike dramatically in a single year (such as technology sectors or episodic commodity surges), sustaining a high compound annual growth rate (CAGR) demands an investor psychology capable of enduring 50% to 80% drawdowns along the way.
This concludes the first part of our comprehensive exploration into the drivers, historical context, and structural mechanics behind the highest-returning stocks.
Evaluating historical market winners reveals that identifying the single highest returning stock requires distinguishing between absolute cumulative wealth creation and annualized percentage velocity. Academic research by financial economists demonstrates that long-horizon stock market wealth is heavily concentrated in a very small fraction of outlier firms.
Altria Group stands as the historic champion of cumulative lifetime wealth creation, delivering a staggering total return exceeding 265,000,000% since its inception era. A modest investment of one thousand dollars into Altria decades ago transformed into billions of dollars when accounting for continuous dividend reinvestment.
Consumer staple corporations frequently dominate long-term compound return lists due to the miraculous compounding power of steady dividend reinvestment. Companies like Coca-Cola and Procter and Gamble generated multifold millions for early shareholders by maintaining consistent payout policies across multiple generations.
Technology giants entered the high-return conversation more recently through aggressive operational expansion and digital transformation. Monster Beverage outperformed nearly every modern equity over a twenty-five-year evaluation window, turning a ten-thousand-dollar stake into over twenty-two million dollars.
Apple and NVIDIA followed close behind, driven by secular shifts toward mobile computing and artificial intelligence infrastructure. NVIDIA expanded by more than 100,000% over twenty-five years, leveraging graphics processing units into the backbone of global machine learning operations.
Micro-cap enterprises that successfully scaled into multinational conglomerates routinely achieved the highest annualized growth rates. Texas Pacific Land Corporation leveraged unique land and water rights in the Permian Basin to deliver exceptional multi-decade returns without traditional corporate overhead.
The mechanics behind these legendary returns rely entirely on sustained revenue growth coupled with expanding profit margins. Businesses that maintain high return on invested capital over decades allow earnings to compound internally at extraordinary rates.
Dividend reinvestment plans act as the hidden engine driving total shareholder return past simple capital appreciation metrics. Reinvesting quarterly payouts during market downturns purchases additional equity units at discounted valuations, dramatically accelerating total share accumulation.
Survivorship bias plays a massive role when analyzing historical market outliers because thousands of competing firms went bankrupt during the exact same timeframes. Investors attempting to isolate the next legendary stock must navigate extreme volatility and high operational uncertainty.
Venture-stage enterprises face immense failure rates before ever achieving the stable cash flows required for sustained stock appreciation. Market participants hunting for extreme returns often mistake short-term speculative bubbles for fundamental long-term value creation.
Meme stocks and speculative trading manias periodically generate temporary percentage spikes that dwarf historical corporate growth figures. These sudden surges rarely sustain long-term wealth because underlying business fundamentals frequently fail to support inflated valuations.
Portfolio diversification remains the primary defense against the inherent volatility associated with high-growth equity investing. Concentrating capital into a single anticipated winner frequently results in permanent capital loss if the underlying thesis fails to materialize.
Institutional research proves that passive indexing captures the vast majority of market gains without exposing portfolios to individual company bankruptcy risk. Trying to pick the exact security that will achieve the highest return resembles finding a microscopic needle in an expanding global haystack.
Future market leaders will likely emerge from emerging sectors such as biotechnology, renewable energy infrastructure, or advanced automation technology. Identifying these future titans requires rigorous fundamental analysis rather than emotional speculation or chasing past performance trends.
Prudent wealth management dictates prioritizing consistent savings rates and asset allocation over speculative searches for outlier stocks. Understanding the mathematical reality of long-term compounding transforms how investors approach risk, time horizons, and portfolio construction.
Every investor must ultimately weigh the allure of astronomical historical returns against the probability of severe capital drawdown. Patience, discipline, and systematic execution remain the definitive hallmarks of successful long-term equity investing.