The statistical illusion of Canadian Upper-Class thresholds
Slicing the percentiles on paper
A top-tier income status looks incredibly impressive on a Statistics Canada spreadsheet but feels surprisingly modest when deposited into a Vancouver or Toronto bank account. If you cross the line of $125,942 annually, you technically clear the barrier into the top 10 percent of Canadian earners. Push that further to $162,210 per year, and you are officially sitting in the top 5 percent of the country's population. It sounds like a massive victory, yet the issue remains that these federal metrics group a corporate executive living in downtown Toronto with a specialized medical professional practicing in rural New Brunswick. The real-world purchasing power of those two salaries could not be more polarized.
The real price of the one percent
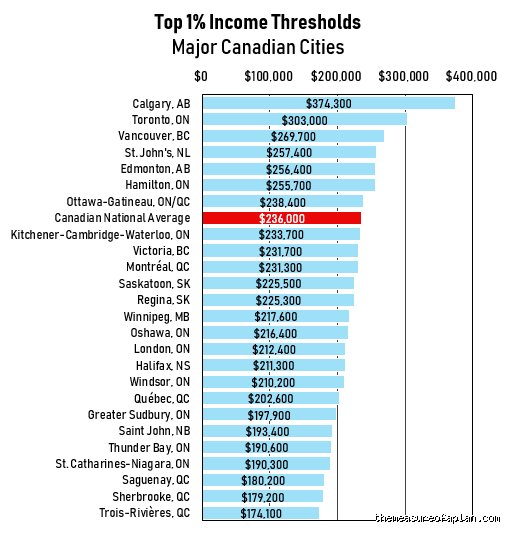
The complication is looking at the actual peak of the compensation mountain. To cross the threshold into the elite 1 percent nationwide, your personal tax return needs to show at least $315,911 in annual compensation. But if you look closely at the average earnings within that specific group, the numbers skyrocket to $586,900 per year due to the massive bonuses and equity packages given to corporate executives. It is a staggering amount of money, yet we are far from the astronomical wealth seen south of the border. It's unclear to many global professionals why Canadian salaries lag so far behind American corporate hubs, but the reality on the ground forces a completely different strategy for preserving wealth.
Taxation dynamics and the reality of net income
The illusion of gross compensation
Let us look at a brutal truth: a high gross salary in Canada is essentially an accounting fiction until the provincial and federal governments take their massive shares. When you finally climb into the upper class, you are immediately met with a progressive tax system that acts as a financial brick wall. Take a corporate vice president based in Ontario who successfully negotiates a $300,000 baseline salary. On paper, they are an undeniable success story. But after the Canada Revenue Agency and the provincial ministry extract their combined cuts, that impressive sum shrinks down to roughly $172,000 in take-home pay. That is a big deal because you are suddenly trying to fund a luxury lifestyle with just over half of what your employer actually pays you.
Marginal rates as a wealth anchor
The system is specifically engineered to make accumulating massive cash reserves through a standard T4 employment slip incredibly difficult. Once your taxable earnings cross the top federal bracket, every extra dollar you bring in faces a combined marginal tax rate that hovers around 53.53 percent in Ontario and peaks at an astonishing 54.8 percent in Quebec. Think about that for a moment. You are doing the high-stress work, putting in the eighty-hour weeks, and taking on massive corporate liability, yet the government becomes the majority partner in your career success. The upshot: reliance on a traditional salary alone is a deeply flawed strategy if your goal is true, generation-defining wealth.
The geographic great divide in modern purchasing power
The cost of metropolitan existence
Location is the ultimate variable that completely breaks traditional definitions of financial success. Earning $200,000 as a software architect in Calgary allows you to purchase a sprawling detached home, park two premium vehicles in the driveway, and build a substantial investment portfolio without checking your bank account. Take that identical salary to Vancouver, and you are suddenly looking at a hyper-competitive real estate market where a standard, unrenovated bungalow requires a multi-million-dollar commitment. I have watched high-earning couples bring in a combined $350,000 household income in the Greater Toronto Area who still feel intense financial anxiety because a basic mortgage eats up $6,500 of their after-tax cash flow every single month. Can you genuinely call someone wealthy when they are struggling to outbid twenty other buyers for a semi-detached house built in the 1970s?
The regional disparities of tax filers
Statistics Canada confirms this geographic polarization with undeniable data. The median income of the top 1 percent in Alberta sits at a robust $495,300, heavily driven by the resource sector and a flat provincial tax legacy that kept margins higher. Meanwhile, Ontario's top earners average $534,800, but that capital is concentrated in a hyper-inflated real estate ecosystem that aggressively erodes its actual utility. But if you look at Prince Edward Island, the entry point for the top 1 percent drops significantly to $386,500. It is a completely different economic universe, which explains why smart professionals are increasingly abandoning the old urban centers for provinces where their dollars aren't instantly vaporized by local living costs.
Salary wealth versus generational capital assets
The High-Earner, Not Rich Yet dilemma
We must make a sharp distinction between a high salary and genuine net worth. A massive income stream can stop instantly due to corporate restructuring, illness, or market downturns—making a high-earning employee surprisingly fragile. This brings us to the rise of the HENRY demographic: High Earners, Not Rich Yet. These are professionals earning $250,000 to $400,000 annually who look wealthy from the outside because they drive German sedans and live in desirable postal codes, but their balance sheets are completely hollow. They are running on a high-speed treadmill, spending nearly everything they earn to maintain an elite social image while saving very little. Yet opinions are split on whether this lifestyle is sustainable in an era of persistent structural inflation.
The true power of asset ownership
The real divide in Canada isn't actually between people who make $80,000 and those who make $180,000; it is between those who rely solely on a salary and those who own appreciating assets. To comfortably join the wealthiest 1 percent of citizens by net worth, you need to control at least $9,963,458 in total assets. A massive portion of that wealth pays zero attention to traditional income brackets because it grows through capital gains, corporate structures, and primary real estate exemptions. In short, a wealthy salary is merely a temporary tool used to buy freedom, not the destination itself.
The mirage of the gross figure: Common misconceptions
The Six-Figure Fallacy
We obsess over arbitrary milestones. Hitting a $100,000 income feels like arriving at financial maturity, except that inflation and aggressive taxation quickly dismantle that dream in places like Toronto or Vancouver. If you pull six figures but hand over a massive chunk to the Canada Revenue Agency, your purchasing power shrivels. A single person earning this amount takes home vastly less than a dual-income couple making the exact same total. Why do we ignore this reality? It remains a bizarre psychological blind spot.
Geography erases equity
What is a wealthy salary in Canada? The answer changes completely when you cross a provincial border. Earning $150,000 in rural Manitoba grants you a palatial lifestyle, complete with sprawling acreage and effortless savings. Put that exact same salary into the hyper-inflated market of downtown Vancouver, and you are suddenly struggling to qualify for a cramped two-bedroom condo. The national average is a completely useless metric for individual financial planning.The Debt-Fueled illusion of affluence
Many individuals who appear incredibly affluent are actually drowning in liabilities. A pristine driveway boasting two brand-new European SUVs frequently signals crushing monthly financing obligations rather than genuine wealth. True affluence lies in liquid assets and cash flow, yet we consistently mistake high-interest consumer debt for disposable income. Luxury assets do not equal net worth.
The velocity of capital: Expert advice on true wealth
Shifting from income to asset generation
Chasing a higher paycheck is a treadmill that never actually stops. To truly master what is a wealthy salary in Canada, you must pivot your focus toward capital accumulation and tax-sheltered investment growth. High earners who fail to maximize their Registered Retirement Savings Plan (RRSP) and Tax-Free Savings Account (TFSA) allotments are essentially volunteering to subsidize the state.
Structuring corporate subsidies
If you operate as a salaried employee, your fiscal optimization options remain strictly limited. Incorporating yourself or negotiating performance-based equity compensation completely alters the financial landscape. Wealthy Canadians rarely rely on a standard T4 slip; they utilize corporate structures to retain earnings at much lower small-business tax rates. This strategic maneuver permits them to reinvest capital efficiently, which explains why true financial freedom often requires stepping outside the traditional employment paradigm.
Frequently asked questions
What is a wealthy salary in Canada when accounting for family size?
A single individual can live luxuriously on a gross income of $160,000 in most metropolitan areas, but a family of four requires a radically different baseline. Statistical data from major urban centers suggests that a household needs at least $250,000 combined to maintain an affluent lifestyle that includes private schooling, annual international travel, and robust retirement contributions. This reality stems from the compounding costs of childcare, larger real estate footprints, and the immediate loss of various government family tax benefits. Consequently, a salary that looks magnificent on paper can feel remarkably ordinary when divided among multiple dependents.
How do provincial tax brackets impact what is considered a wealthy salary in Canada?
The fiscal landscape varies dramatically depending on your specific geographic coordinates. An individual earning $200,000 in Alberta enjoys a significantly higher take-home pay than an identical earner residing in Quebec, thanks to Alberta's lack of a provincial sales tax and its flatter income tax structure. In fact, the net difference between these two scenarios can amount to more than $10,000 annually in disposable income. The problem is that federal tax brackets apply universally, but provincial levies dictate the actual boundaries of your local purchasing power.
Can you achieve wealthy status solely through a high T4 employment income?
Relying exclusively on a traditional paycheck is the slowest path to genuine financial independence due to Canada’s highly progressive taxation system. When your marginal tax rate pushes past 50 percent in provinces like Ontario or Nova Scotia, every additional dollar you earn is effectively cut in half by the government. True affluence requires transitioning your earnings into capital gains or dividend income, which enjoy far more favorable tax treatment than standard employment wages. As a result, relying solely on a high salary without building an investment portfolio keeps you perpetually dependent on your employer.
Revisiting the Canadian wealth paradigm
We must stop equating a high salary with definitive financial victory. The traditional Canadian dream of climbing the corporate ladder to secure a massive paycheck is fundamentally flawed because it ignores the relentless erosion of taxation and living costs. Genuine wealth is never measured by the arbitrary number stamped on your employment contract, but rather by the autonomy your capital provides. If your high income demands sixty hours of grueling labor every week just to service a massive mortgage, you are merely a highly compensated occupant of a gilded cage. True financial sovereignty belongs exclusively to those who convert temporary high wages into permanent, income-generating assets. We must change the conversation entirely from what we earn to what we keep and control.