The uncomfortable truth of equity Markets
The short, unvarnished answer is an emphatic yes. While public equity markets offer unprecedented opportunities for capital appreciation, they also carry the ultimate risk of total capital loss. Unlike government bonds or guaranteed savings vehicles, common stocks represent fractional ownership in a commercial enterprise. If that enterprise fails entirely, the fractional ownership it grants can become completely worthless.
Understanding how and why a stock can plummet to absolute zero is not merely an academic exercise; it is an essential pillar of risk management. Beginners often assume that established companies listed on major exchanges like the New York Stock Exchange or NASDAQ are immune to total extinction. History, however, tells a different story. Giants of industry, household names with decades of operating history, have occasionally seen their equity valuations completely wiped out, leaving shareholders with nothing but a hard-learned lesson.
Deconstructing share price: What do you actually own?
To comprehend how a stock can reach a value of zero, one must first dissect the fundamental mechanics of what a share price represents. A common stock is not just a digital token that fluctuates on a computer screen; it is a legal claim on a portion of a corporation's assets, earnings, and future cash flows.
The interaction of supply and demand
At any given second, the price of a stock is determined by the intersection of supply and demand. When market participants believe a company’s future is bright, they are willing to pay higher prices to acquire shares, driving the valuation upward. Conversely, if sentiment sours, buyers retreat, and sellers flood the market.
A stock's price relies entirely on the existence of a bid—a price that a prospective buyer is willing to pay. As long as there is a functioning market with active participants placing bids, a stock will trade at some numerical value, even if it falls to fractions of a cent. However, when catastrophic events unfold, the psychological and financial appetite for a company's shares can evaporate entirely. When all bids vanish and no rational market participant is willing to exchange capital for a slice of the enterprise, the effective trading price collapses to zero.
Equity as a residual claim
As a common shareholder, you hold a residual claim on the company. This means you stand at the very back of the line when it comes to financial distributions. If a company generates profits, senior debt holders, bondholders, suppliers, and preferred stockholders must be satisfied first. Only after all liabilities and obligations are fully cleared do common shareholders have a right to the remaining value. If a company's debts outstrip its total asset liquidation value, the residual value for common equity is mathematically zero.
The anatomy of corporate collapse
A stock does not typically drop to zero overnight without a compelling catalyst, barring sudden, catastrophic fraud. Instead, the descent is usually a prolonged, multi-stage deterioration driven by structural vulnerabilities, managerial missteps, or disruptive macroeconomic forces.
1. Fundamental business decay
The primary engine of stock value is operational performance. When a company consistently fails to generate adequate revenues, loses market share to agile competitors, or operates with a fundamentally flawed business model, its financial health deteriorates. Profit margins shrink, cash reserves dwindle, and the company is eventually forced to rely on external debt just to keep the lights on.
2. The debt trap and insolvency
As operating cash flows turn negative, management often resorts to borrowing money to bridge the gap. While debt can fuel growth during prosperous periods, it becomes an existential anchor during downturns. High interest obligations compounded by falling sales create a vicious cycle. Once a company's liabilities exceed the total fair market value of its assets, the firm is technically insolvent.
3. Investor flight and liquidity crises
As financial distress becomes public knowledge, institutional investors and retail traders begin to exit their positions. This selling pressure depresses the share price, triggering margin calls and automated stop-loss orders. Lower share prices severely impair the company's ability to raise fresh equity capital through secondary offerings, deepening the liquidity crisis. The company enters a death spiral where weak financials depress the stock price, and a depressed stock price restricts operational recovery.
Legal realities: Bankruptcy and the liquidity wipeout
When a company can no longer service its debt obligations or meet payroll, it must seek legal protection through the court system. This process fundamentally alters the status of public equity and is the primary mechanism by which stocks reach zero.
Chapter 7 vs. Chapter 11 Bankruptcy
In the United States, corporate bankruptcies generally fall into two main categories:
Chapter 7 Bankruptcy (Liquidation): The corporation ceases all active business operations immediately. A court-appointed trustee takes control of the remaining assets, sells them off piecemeal, and distributes the proceeds to creditors in a strict order of statutory priority. Common shareholders are at the absolute bottom of this hierarchy. By the time secured lenders, bondholders, tax authorities, and legal fees are paid, virtually nothing remains for equity holders. The stock is permanently delisted, and the shares officially become worthless.
Chapter 11 Bankruptcy (Reorganization): The company continues operating while it attempts to restructure its debts and renegotiate contracts under court supervision. In some rare reorganizations, existing common stock may retain a tiny fraction of value or be converted into new shares of a reorganized entity. However, in the vast majority of severe Chapter 11 cases, the existing equity is entirely canceled to clear the balance sheet, wiping out common stockholders completely.
Stock Exchange Delisting
Before a company officially liquidates, its shares often face delisting from major exchanges like the NYSE or NASDAQ. Exchanges enforce strict listing compliance rules regarding minimum share prices (such as maintaining a price above $1.00) and minimum market capitalization thresholds. When a stock persistently trades as a distressed penny stock, the exchange issues a delisting warning. Once a stock is removed from major exchanges, it is relegated to over-the-counter (OTC) pink sheets, where liquidity dries up entirely, accelerating the slide toward absolute zero.
Historical precedents: When giants fall
To truly grasp how a stock reaches zero, examining historical case studies provides undeniable context. These examples demonstrate that market capitalization is never permanent.
Enron Corporation (2001)
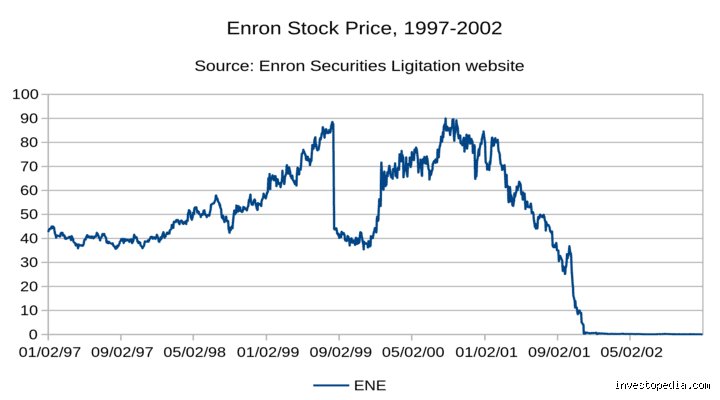
At its peak in the year 2000, Enron was celebrated as an innovative titan of the energy and commodities sector, with its shares trading above $90. Behind the corporate facade, however, executives engaged in widespread accounting fraud, using complex off-the-books special purpose entities to conceal billions in toxic debt and inflated earnings. Once investigative journalism and regulatory scrutiny exposed the malfeasance, investor confidence vanished instantly. Enron filed for bankruptcy in December 2001, and its equity value crashed to fractions of a dollar, utterly wiping out institutional portfolios and employee retirement accounts alike.
Blockbuster Inc. (2010)
Blockbuster serves as a textbook example of technological disruption meeting strategic complacency. For decades, the video rental giant dominated neighborhood strip malls across the globe. However, management failed to adapt swiftly enough to the digital streaming revolution and the mail-order subscription model pioneered by competitors like Netflix. Burdened by heavy debt loads and declining retail foot traffic, Blockbuster’s revenues plummeted. The company filed for bankruptcy in 2010, and its common stock was completely extinguished, demonstrating that even a dominant brand name can be rendered obsolete.
The mechanics of collapse and Delisting
To fully understand how a stock reaches absolute zero, we must examine the precise mechanical and legal steps that accompany corporate insolvency. When a company experiences a catastrophic failure of its underlying business model, mounting debt obligations, or catastrophic legal liabilities, it typically initiates a formal legal restructuring process through bankruptcy protection—most commonly under Chapter 11 or Chapter 7 of the United States Bankruptcy Code (or equivalent international frameworks).
Chapter 11 (Reorganization): In a Chapter 11 bankruptcy, the company continues operating while attempting to restructure its debts. During this period, the stock often continues to trade over-the-counter (OTC) or on major exchanges under a temporary ticker symbol appended with a "Q" (e.g., former companies like Lehman Brothers or General Motors during their historic filings). However, under the absolute priority rule of bankruptcy law, senior creditors, bondholders, and secured lenders must be made whole before equity holders receive a single penny. Consequently, in the vast majority of Chapter 11 restructurings, existing common shares are completely canceled and extinguished, leaving common shareholders with zero value.
Chapter 7 (Liquidation): Under Chapter 7, operations cease entirely. A court-appointed trustee liquidates all remaining physical assets, inventory, real estate, and intellectual property to pay off creditors. Once again, common stock sits at the absolute bottom of the capital structure. By the time administrative expenses, secured debt, unsecured debt, and preferred stock claims are satisfied, the residual pool of capital is virtually always empty.
Exchange Delisting: Long before a formal court liquidation concludes, major stock exchanges like the New York Stock Exchange (NYSE) or NASDAQ will suspend and delist a stock if its market capitalization or average share price falls below mandatory minimum thresholds (such as trading below $1.00 for an extended period or failing to file required SEC reports). Once delisted, liquidity dries up rapidly, forcing the equity into decentralized over-the-counter (OTC) pink sheets where price discovery becomes erratic and execution spreads widen dramatically.
A Little-Known aspect: The bizarre afterlife of "zombie stocks" and the Expert Market
A fascinating and often misunderstood phenomenon in financial markets is what happens after a stock technically goes to zero or gets delisted. Many retail investors assume that once a company declares bankruptcy and its stock is removed from major exchanges, the shares simply vanish from their brokerage accounts. In reality, dead equities sometimes enter a surreal afterlife governed by specialized market rules.
The OTC Pink Sheets and "Expert Markets": Regulatory changes, such as SEC Rule 15c2-11, overhauled how defunct or "dark" companies trade. Many bankrupt stocks are relegated to the "Expert Market," where only sophisticated or institutional investors can buy and sell shares, severely restricting retail access.
The Speculative Resurgence: Paradoxically, defunct stocks can occasionally experience bizarre, short-lived speculative surges. During the meme-stock craze, defunct or bankrupt retailers saw massive, irrational spikes in volume as retail traders coordinated online, buying up shares of companies that had zero underlying operating business. These trades are driven purely by momentum, algorithmic feedback loops, and pure speculation rather than fundamental valuation.
Tax Loss Harvesting Reality: From a practical standpoint, holding a worthless stock until it is officially canceled or sold for pennies allows investors to claim a capital loss for tax purposes. However, brokers often charge a reorganization fee to remove dead certificates or worthless positions from an account, meaning the cost of administrative cleanup can sometimes exceed the residual value of the asset.
Managing downside risk and psychological biases
Recognizing that any individual equity can, and occasionally does, go to zero fundamentally shifts how prudent investors approach portfolio construction and risk management. Mitigating this catastrophic risk requires a blend of structural portfolio safeguards and psychological discipline.
Diversification as a Shield: No matter how thorough your fundamental analysis is, "black swan" events, accounting fraud, or sudden technological obsolescence can blindsside even blue-chip companies. Holding a concentrated portfolio of two or three stocks exposes an investor to ruin. Broad-based index funds or a well-diversified basket of 20 to 30 uncorrelated assets ensures that the complete collapse of a single holding will not devastate your overall financial future.
The Fallacy of Averaging Down: A common behavioral trap is the urge to "average down" on a falling stock, rationalizing that because a share is cheaper now, buying more is a bargain. If the underlying thesis of the business is broken, such as secular demand destruction or terminal debt distress, adding capital to a sinking ship only increases your total exposure to absolute zero.
Stop-Loss Orders vs. Gap Downs: While stop-loss orders are useful risk-management tools, they are not foolproof defenses against going to zero. If a company releases devastating news overnight or files for bankruptcy before the market opens, the stock can "gap down" past your specified stop-loss price, executing at a much lower valuation or failing to execute entirely until liquidity evaporates.
Embracing Reality in modern portfolio construction
Can a stock go to zero? Yes, absolutely. Whether driven by excessive leverage, fraudulent accounting, technological disruption, or catastrophic legal liabilities, the permanent loss of 100% of an equity's value is an inescapable risk of public market investing.
Understanding this reality should not breed paralysis or fear; rather, it should instill a healthy respect for risk management, thorough due diligence, and portfolio diversification. Equities represent fractional ownership in living, breathing business enterprises subject to economic mortality. By acknowledging that zero is a very real destination for poorly managed or unlucky companies, investors can better protect their capital, avoid speculative traps, and build resilient, long-term wealth strategies designed to weather the inevitable storms of the financial markets.