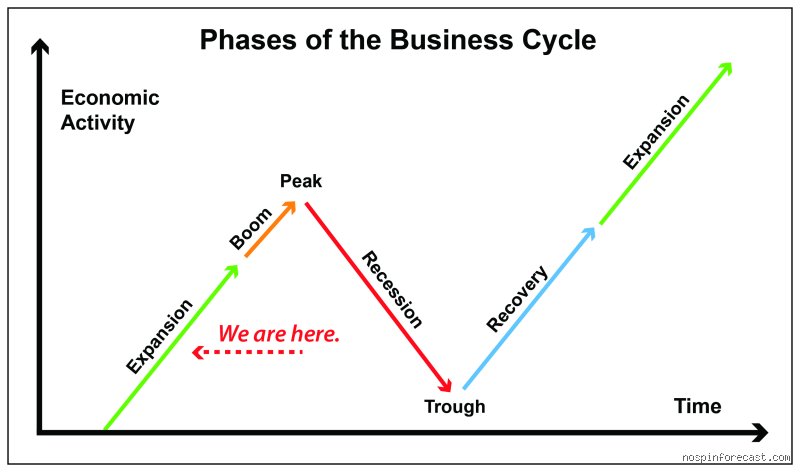
Defining the Post-Recession landscape
Understanding what typically happens after a recession is crucial for policymakers, institutional investors, business leaders, and everyday citizens alike. The post-recession landscape is rarely a mirror image of the expansion that preceded it; rather, it is a dynamic, highly regulated, and structurally altered environment. The transition from a downturn to a sustained expansion is characterized by a complex interplay of monetary policy recalibration, fiscal stimulus hangover, shifting consumer behavior, industrial reorganization, and labor market recalibration.
This comprehensive first part of our expert analysis explores the foundational dynamics of the immediate post-recession environment, examining how central banks lay the groundwork for revival, how financial systems heal from systemic stress, and the immediate psychological and behavioral shifts that define consumer and corporate sentiment as the clouds of economic uncertainty begin to part.
The monetary pivot: Interest rates, liquidity, and Central Bank intervention
The single most immediate and influential catalyst for post-recession recovery is the monetary policy pivot executed by central banks, most notably the United States Federal Reserve, the European Central Bank, the Bank of England, and other global monetary authorities.
During the depths of a recession, central banks aggressively slash benchmark interest rates to near-zero or even negative territory to lower borrowing costs, stimulate credit creation, and incentivize spending over saving. As the economy touches its cyclical trough, these emergency measures are typically maintained for an extended period to ensure that green shoots of recovery are not prematurely crushed by rising capital costs.
1. The prolonged Low-Rate environment and Yield curve dynamics
In the immediate aftermath of a contraction, central banks prioritize economic stability over inflation targeting, often keeping short-term interest rates low long after growth has resumed. This creates a distinct yield curve environment:
Steep Yield Curves: Short-term rates remain anchored near zero by central bank policy, while long-term yields begin to edge upward as investors demand higher premiums for long-term lending amid anticipated future economic growth and moderate inflation expectations.
Credit Availability: Low borrowing costs encourage commercial banks to start extending credit again. After months of stringent lending standards (often termed a "credit crunch"), financial institutions gradually ease underwriting criteria, allowing solvent businesses and consumers to refinance high-cost debt and fund capital expenditures.
2. Quantitative Easing (QE) and asset price inflation
Beyond benchmark rates, modern post-recession environments are heavily influenced by unconventional monetary policies. Central banks often maintain bloated balance sheets resulting from asset purchase programs (Quantitative Easing).
The excess liquidity injected into the financial system during the recession does not immediately translate into consumer price inflation; instead, it frequently finds its way into capital markets and real estate.
Consequently, one of the hallmark features of the post-recession recovery is a "financial asset recovery", where stock markets and property values often rebound significantly faster and more aggressively than broader macroeconomic indicators like employment and median wage growth.
Fiscal stimulus, sovereign debt, and the public sector hangover
While monetary policy provides the grease for the economic engine, fiscal policy, government spending and taxation, serves as the heavy machinery deployed to pull an economy out of a ditch. However, the legacy of aggressive fiscal intervention during a recession creates profound structural consequences for the post-recession period.
1. The multiplier effect and infrastructure investment
To counteract plunging private demand during a downturn, governments routinely run massive fiscal deficits, funding infrastructure projects, direct stimulus checks, unemployment insurance enhancements, and corporate bailouts.
As the economy exits the recession, these fiscal injections continue to ripple through the economy via the Keynesian multiplier effect.
Construction projects commissioned during the downturn reach operational phases, manufacturing supply chains receive a steady stream of government-backed orders, and public-sector employment stabilizes.
2. The debt burden and fiscal cliff risks
The inevitable byproduct of massive crisis-era spending is a historic surge in national debt-to-GDP ratios. In the post-recession phase, governments frequently face a difficult policy dilemma:
Austerity vs. Stimulus: If a government withdraws fiscal support too quickly (fearing bond market vigilantism, inflation, or sovereign debt downgrades), it risks triggering a double-dip recession. Conversely, maintaining high spending levels can crowd out private investment and saddle future generations with high debt servicing costs.
Tax Policy Shifts: To manage ballooning deficits, post-recession governments often pivot from tax cuts to tax reform, potentially raising corporate tax rates, introducing wealth taxes, or closing loopholes. Businesses must factor these changing fiscal regimes into their long-term capital allocation strategies.
Financial sector repair: Deleveraging, recapitalization, and risk reappraisal
A recession frequently originates within or severely damages the financial sector. Whether triggered by subprime mortgage defaults, over-leveraged corporate debt, or liquidity crunches, the banking system requires a rigorous healing process before a true economic expansion can take root.
1. Balance sheet Clean-Up and Non-Performing loans (NPLs)
In the immediate post-recession phase, financial institutions must confront the wreckage of bad loans accumulated during the downturn.
Banks engage in aggressive balance sheet repair, writing off toxic assets, provisioning for loan losses, and raising fresh equity capital through secondary stock offerings or retained earnings.
Regulatory bodies play a central role here, often enforcing stricter capital adequacy requirements (such as Basel III frameworks) and conducting rigorous stress tests to ensure that the banking sector can withstand subsequent shocks. This regulatory tightening, while essential for systemic stability, can temporarily create a "quiet credit" environment where banks are hyper-cautious, favoring ultra-safe assets like government bonds over riskier entrepreneurial lending.
2. M&A activity and Industry consolidation
Recessions weed out weak competitors, leaving behind a landscape ripe for consolidation. In the post-recession period, merger and acquisition (M&A) activity surges significantly.
Distressed Assets: Well-capitalized corporations and private equity firms armed with "dry powder" (unallocated capital) acquire distressed competitors, intellectual property, and real estate at significant discounts.
Industry Monopolization: While consolidation increases corporate efficiency in the short term, it can also lead to reduced market competition and higher concentration ratios across technology, healthcare, finance, and industrial sectors, shaping market dynamics for the duration of the ensuing economic expansion.
Psychological Shifts and consumer behavior transformation
Economic data tells only half the story; the other half is driven by human psychology, sentiment, and behavioral adaptation. A severe recession leaves psychological scars on consumers, investors, and business leaders, permanently altering spending and saving patterns.
1. The precautionary savings phenomenon
During a recession, the fear of job loss and asset depreciation causes households to dramatically cut discretionary spending and boost their savings rates. Surprisingly, this cautious behavior often persists well into the early stages of the recovery.
Delayed Gratification: Consumers prioritize debt reduction over consumption, paying down credit cards, auto loans, and mortgages.
Structural Thrift: Entire generations marked by economic trauma (such as those who lived through the 2008 Global Financial Crisis or pandemic-era disruptions) often exhibit long-term increases in baseline savings rates, favoring value-based consumption, durability, and financial security over conspicuous consumption.
2. Business confidence and cautious capital expenditure (CapEx)
Corporate executives experience a similar psychological lag. Exiting a recession, businesses are naturally gun-shy. Having witnessed sudden demand destruction, CFOs and CEOs are reluctant to commit immediately to large-scale capital investments or aggressive hiring sprees.
Instead of expanding physical footprints, firms initially focus on operational efficiency, automation, and lean inventory management.
Capital expenditure rebounds sequentially: first in software, technology upgrades, and maintenance, and only later in long-term physical infrastructure, commercial real estate, and major plant expansions.
Conclusion of part one
The aftermath of a recession is a period of profound transition, defined by the delicate choreography of monetary easing, fiscal reckoning, financial sector healing, and behavioral recalibration. Central banks work tirelessly to maintain liquidity and nurse asset markets back to health, while governments grapple with the long-term implications of elevated debt loads. Simultaneously, businesses and consumers navigate a changed world with heightened risk awareness and altered priorities.
In the second part of this expert analysis, we will delve deeper into the labor market dynamics of the post-recession recovery, examining the phenomenon of jobless recoveries, structural shifts in employment, wage growth trajectories, and the rise of new industries that ultimately drive the next great economic expansion.
Explore related economic concepts and market analyses:
Navigating the trough: The anatomy of an Economic recovery
When a recession officially ends, the economy does not instantly snap back to a state of robust prosperity. Instead, it enters a delicate, highly nuanced phase known as the trough and the early recovery. Understanding what usually happens after a contraction requires looking beyond headline figures like Gross Domestic Product (GDP) and examining how labor markets, monetary policy, consumer behavior, and financial asset classes fundamentally shift as the macroeconomic climate thaws.
1. The lagging reality of the labor market
One of the most misunderstood phenomena of the post-recession landscape is the behavior of employment. While economic output (GDP) may begin pointing upward, the job market notoriously lags behind.
During a recession, businesses lean out, automating tasks, cutting waste, and forcing remaining employees to shoulder heavier workloads. When demand finally returns, companies are initially hesitant to hire. Burned by the volatility of the downturn, management prefers to maximize the productivity of their existing workforce through increased hours or overtime before taking on the fixed costs and risks of onboarding new staff.
Consequently, the unemployment rate often continues to rise, or remains stubbornly high, months after a recession has technically ended. This creates the psychological sensation of a "jobless recovery," where structural adjustments and cautious corporate spending mask the underlying macro-level healing. Only when demand becomes sustained and unshakeable do firms open the floodgates to widespread hiring, driving wages back up.
2. Monetary Policy, interest rates, and liquidity Shifts
Central banks matter a lot in dictating the post-recession environment. To cushion the fall during a contraction, monetary authorities typically slash benchmark interest rates and inject liquidity into the financial system.
As the recovery takes root, these emergency measures begin to transform. Initially, interest rates remain low to encourage borrowing, stimulate corporate investment, and revitalize the housing market. However, as economic momentum accelerates, the central bank’s focus shifts from rescue to restraint. To prevent the budding expansion from overheating and triggering runaway inflation, monetary policymakers gradually normalize interest rates.
For consumers and businesses, this transition period offers a crucial window of opportunity. Low borrowing costs early in the recovery allow households to refinance high-interest debt, while corporations lock in favorable long-term bond yields before monetary tightening takes full effect.
3. Sector rotation and Financial market dynamics
Financial markets rarely wait for concrete economic data to confirm a turnaround; they act as forward-looking mechanisms, bottoming out and rallying well before Main Street feels the relief.
The Early-Cycle Surge: As recovery begins, cyclically sensitive sectors, such as consumer discretionary, industrials, real estate, and technology, historically outperform. Investors transition away from defensive safe havens (like utilities and consumer staples, which dominated the recessionary phase) and pivot aggressively toward risk assets.
Corporate Earnings Rebound: Corporate balance sheets, having been aggressively restructured during the downturn, begin to yield high operating leverage. Even modest increases in sales translate into disproportionate jumps in net income, sparking a broad-based revival in equity valuations.
4. Structural evolution and innovation
Recessions act as economic filters. While they inflict widespread pain, they also sweep away unsustainable business models, bloated cost structures, and over-leveraged entities.
What emerges on the other side is often a leaner, more resilient corporate ecosystem. Necessity forces invention: history shows that some of the world’s most disruptive companies, products, and operational frameworks were conceptualized or launched during or immediately following severe economic downturns. Supply chains are re-engineered to be more robust, and labor forces adopt new digital proficiencies born out of the crisis period.
Preparing for the next cycle
What happens after a recession is the laying of the groundwork for the next expansionary phase. The recovery transitions into a steady expansion, characterized by rising consumer confidence, normalized employment, and peak corporate growth, before the business cycle inevitably matures and restarts its eternal pendulum swing. Recognizing these predictable post-recession patterns allows individuals, businesses, and investors to position themselves not just to survive the contraction, but to capitalize on the renewal that follows.