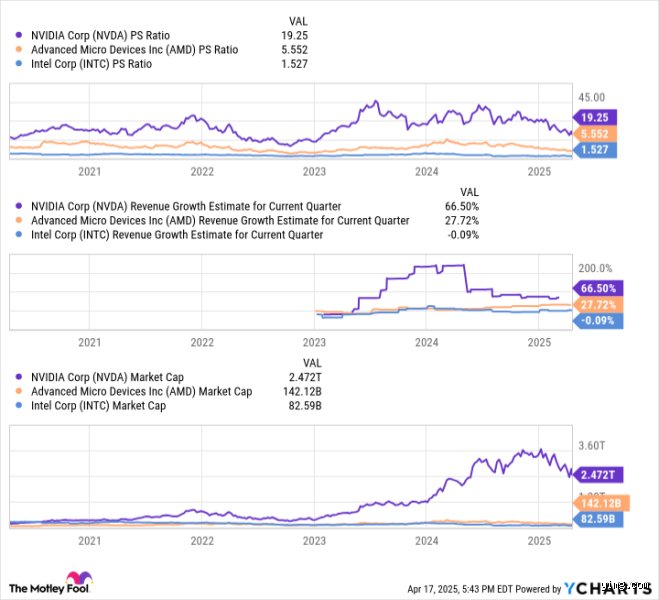
Nvidia is the stock most often mentioned as having the potential to approach an $80 trillion valuation by 2030, though such a figure remains speculative and far beyond current global economic benchmarks. This idea stems from its central role in artificial intelligence computing, where its hardware and software ecosystems are deeply embedded in global tech infrastructure. While no company today comes close to that scale, Nvidia’s trajectory in AI and data centers fuels the discussion.
The role of AI in reshaping market valuations
Traditional market capitalization models rely on steady revenue growth and predictable industries. Nvidia operates in a different realm—one where demand for computing power is growing exponentially due to AI training, cloud services, and automation. The shift from human-driven software to AI-generated code increases the need for powerful GPUs, which Nvidia supplies at scale.
Why exponential demand matters
AI models require vast amounts of processing power, especially during training phases. Each new generation of AI demands more compute, and Nvidia’s chips—like the H100 and Blackwell B200, are the preferred choice for data centers worldwide. This creates a feedback loop: more AI applications lead to more demand for Nvidia’s hardware, which in turn accelerates AI development.
Nvidia’s software moat: CUDA as a strategic advantage
While competitors like AMD and startups develop powerful chips, Nvidia’s real strength lies in its CUDA platform. Millions of developers have built AI and machine learning applications using CUDA, making it the industry standard. Switching to another platform would require massive retraining and code rewriting, which most companies avoid.
This software dominance means that even if another company builds a faster chip, adoption remains low without a mature ecosystem. Nvidia’s lead isn’t just in silicon, it’s in developer loyalty and infrastructure integration.
Geopolitical demand for sovereign computing
Nation-states are now major buyers of high-end computing infrastructure. Countries like Japan and Saudi Arabia are investing in domestic AI capabilities to avoid reliance on foreign technology. These sovereign data centers often rely on Nvidia’s hardware, turning the company into a critical player in national security and digital independence.
The result is a new kind of customer: governments treating GPU clusters like strategic assets, similar to energy or defense infrastructure. This shifts Nvidia from a tech supplier to a foundational layer of national capability.
Revenue beyond selling chips
To reach an $80 trillion valuation, Nvidia would need to evolve beyond selling physical hardware. The future lies in recurring revenue models, licensing software, powering cloud-based AI simulations, and enabling autonomous systems. Platforms like Omniverse could become the virtual testing grounds for robots, factories, and smart cities, with Nvidia collecting fees at each step.
Every robotic action in a factory or self-driving decision could generate micro-payments routed back to Nvidia’s infrastructure. When scaled globally, this creates a new kind of digital economy where compute becomes a continuous revenue stream.
Challenges to reaching such a valuation
An $80 trillion market cap exceeds the entire global GDP of 2024. No single company has ever come close, making this scenario more theoretical than practical. Physical limits, like power consumption, chip fabrication capacity, and geopolitical instability, could halt growth. Taiwan’s role in manufacturing Nvidia’s chips creates a supply chain vulnerability, especially given regional tensions.
Governments may intervene if one company becomes too dominant. Antitrust actions or forced breakups could limit Nvidia’s expansion, even if its technology remains essential. The path to such a valuation isn’t just technological, it’s economic and political.