Decoding the AI giant’s Crossroads: Should You Sell Your NVDA stock Now? (Part 1)
Right now, shareholders find themselves staring at a complex market matrix. With the stock retreating significantly from its record highs—pressured by shifting macroeconomic tides, export controls, and monumental corporate governance changes, the question on every investor's mind is no longer just about how high the ceiling is, but how firm the floor is. Should you lock in remaining gains, trim your position to manage risk, or hold firm against the storm? To answer this question objectively, we must look past the emotional noise and dissect the fundamental, operational, and structural realities shaping NVIDIA today.
The paradigm shift: Structural realities and Market sentiment
To evaluate whether it is time to part ways with your NVDA shares, you must first acknowledge the distinct phase transition the company is currently navigating. For a long time, NVIDIA’s narrative was simple: an insatiable global appetite for computing power met an unmatched technological monopoly, resulting in consecutive quarters of jaw-dropping financial growth.
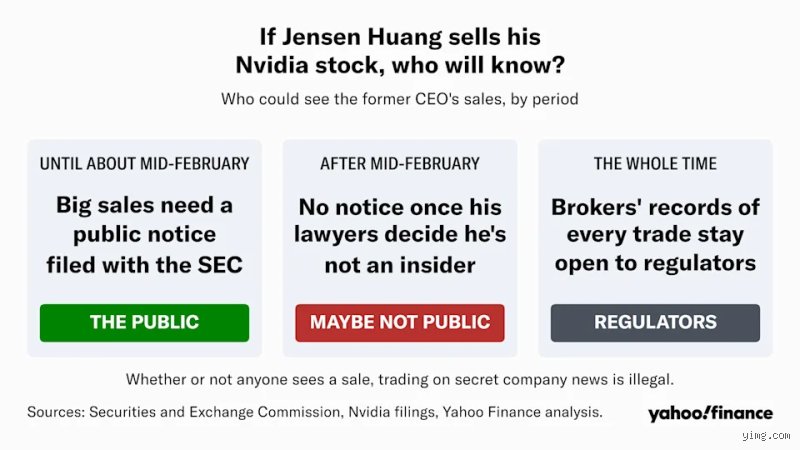
However, market dynamics change when a company reaches multi-trillion-dollar scale. At this magnitude, maintaining triple-digit percentage growth becomes exponentially more difficult, and the market's tolerance for disruption shrinks to near zero. Recent events have thrust NVIDIA into a new chapter of its corporate lifecycle. The sudden leadership transition, most notably the departure of longtime visionary CEO Jensen Huang and the stepping up of former# Navigating the Crossroads: Should You Sell Your NVDA Position Now?
Part 1: The Macro Environment, Market Dominance, and the Evolution of the AI Infrastructure Cycle
The question of whether to sell NVIDIA (NASDAQ: NVDA) is perhaps the most defining portfolio dilemma of the mid-2020s. For years, riding the wave of the generative artificial intelligence boom has been one of the most lucrative trades in financial history. NVIDIA transformed from a specialized gaming hardware manufacturer into the undisputed backbone of global computing infrastructure, commanding staggering market capitalizations and redefining what a semiconductor company could earn in a single fiscal year.
However, stellar past performance does not automatically guarantee future dominance, and intelligent investing requires continuous, rigorous re-evaluation. As we navigate through 2026, the macroeconomic landscape, competitive dynamics, and the lifecycle of enterprise AI spending are undergoing a subtle yet profound shift. Investors who bought early, or even those who bought during intermediate pullbacks, are sitting on monumental gains. This raises a classic, high-stakes portfolio management question: When does disciplined profit-taking outweigh the risk of missing out on the next leg of growth?
To answer whether you should sell your NVDA shares right now, we must break down the analysis into foundational pillars: the current macroeconomic and monetary backdrop, the evolution of NVIDIA’s technological moat, the shifting behavior of hyper-scaler customers, and the psychological realities of portfolio concentration.
1. The macroeconomic backdrop: Rates, liquidity, and Risk appetite
No equity exists in a vacuum. NVIDIA’s valuation has historically been sensitive to broader macroeconomic conditions, particularly interest rate trajectories, systemic liquidity, and market-wide risk appetite.
The cost of capital and growth valuations
During periods of aggressive monetary easing or stable, low interest rates, the present value of future cash flows for hyper-growth companies remains high. Investors are willing to pay lofty price-to-earnings (P/E) multiples because alternative risk-free assets (such as government bonds) offer lower yields. As the global macroeconomic environment stabilizes through 2026, capital markets have become increasingly discerning.
When evaluating NVIDIA today, you must ask yourself how your portfolio handles macro-induced volatility. High-multiple growth leaders are often the first assets institutional investors trim when they need to rebalance risk or lock in gains to meet annual return targets. If macro indicators point toward tightening liquidity or sector-wide rotation out of mega-cap technology, even a fundamentally flawless company like NVIDIA can experience sharp, multi-week drawdowns.
The broad Market context
NVIDIA’s immense weight in major indices like the S&P 500 and the Nasdaq 100 means its fortunes are closely intertwined with passive fund flows. When passive inflows remain robust, upward momentum feeds on itself. Conversely, if broader market sentiment shifts, prompted by geopolitical friction, labor market shifts, or fiscal policy changes, systematic selling can put downward pressure on the stock regardless of immediate quarterly earnings beats.
2. Analyzing the moat: Hardware Dominance meets Software stickiness
To understand whether to sell, you must first re-verify why you bought. NVIDIA's competitive advantage has never been solely about raw silicon performance; it is a comprehensive ecosystem play.
The CUDA Ecosystem and developer Lock-In
NVIDIA’s true genius was recognizing the importance of software decades before the generative AI boom. The Compute Unified Device Architecture (CUDA) platform created an insurmountable moat. Millions of developers, researchers, and enterprise engineers write their machine learning models directly for CUDA.
Switching away from NVIDIA hardware is rarely just a matter of buying a cheaper chip from a competitor; it involves rewriting entire software stacks, retraining models, and risking performance degradation or instability in mission-critical environments. This high switching cost creates extraordinary pricing power and gross margin resilience that few hardware companies in history have ever achieved.
Beyond the GPU: The Full-Stack strategy
As the market matures, NVIDIA has successfully transitioned from selling individual graphics processing units to delivering entire rack-scale systems, networking architecture (via InfiniBand and Quantum technologies), and proprietary enterprise software subscriptions (NVIDIA AI Enterprise). By providing the complete data center blueprint, from compute to networking to orchestration, NVIDIA ensures that its customers view it as an indispensable infrastructure partner rather than a simple commodity supplier.
However, a strong moat does not make a stock immune to cyclicality. The critical question for investors is not whether NVIDIA makes the best chips, it almost certainly does, but rather whether the rate of acceleration in demand for those chips can sustain past exponential growth rates.
3. The Hyper-Scaler capex Cycle: Transitioning from buildout to monetization
The primary engine behind NVIDIA’s meteoric rise has been the unprecedented capital expenditure (capex) cycle executed by the world's largest technology companies, often referred to as the hyper-scalers (such as Microsoft, Alphabet, Meta, Amazon, and major sovereign cloud providers).
The Phase 1 Infrastructure gold rush
Between 2023 and 2025, the tech giants engaged in a high-stakes arms race. Fear of missing out on the generative AI revolution meant that building massive GPU clusters was an existential necessity. Return on investment (ROI) calculations were secondary to establishing foundational computing capacity. NVIDIA was the primary beneficiary of this unconstrained spending spree, capturing an overwhelming share of every dollar allocated to AI data centers.
Entering Phase 2: The return on investment (ROI) scrutiny
As we move deeper into 2026, the market has transitioned into Phase 2 of the AI adoption cycle. Wall Street and corporate boards are no longer satisfied with general announcements of multi-billion-dollar data center investments. They are demanding clear, quantifiable evidence of monetization.
Are enterprise software subscriptions generating enough revenue to justify the capex?
Are consumer-facing AI features driving sustainable top-line growth or merely adding operational costs?
If hyper-scalers begin to see diminishing marginal returns on additional GPU clusters, or if they experience cash flow pressures from maintaining massive AI infrastructure without immediate, matching revenue streams, capital expenditure growth rates could moderate. A moderation in capex growth does not mean NVIDIA’s sales will collapse, but it does mean that the era of hyper-accelerated, beat-and-raise quarters may give way to a more normalized, cyclical growth pattern. For long-term holders, recognizing this transition is vital to adjusting return expectations.
4. The rise of custom silicon and competitive pressures
While NVIDIA remains the undisputed king of AI training and inference, no monopoly lasts forever in high-tech semiconductors. The sheer economic gravity of NVIDIA’s profit margins has mobilized formidable competitors across the landscape.
Internal custom accelerators (ASICs)
The very customers buying the most GPUs from NVIDIA, the hyper-scalers, are simultaneously designing their own Application-Specific Integrated Circuits (ASICs) optimized for their specific internal workloads (such as inference tasks for large language models). While these custom chips rarely match the general-purpose flexibility and raw power of NVIDIA's top-tier architecture, they capture a growing slice of predictable, high-volume workloads within those specific clouds. Over time, this insulates hyper-scalers from total reliance on any single hardware supplier and places a natural ceiling on how high NVIDIA can push its pricing without triggering accelerated internal silicon development.
Traditional competitors and emerging startups
Legacy semiconductor giants and heavily funded venture-backed startups continue to introduce alternative architectures designed to chip away at NVIDIA's market share, particularly in power-efficient edge computing and specialized inference deployments. While switching costs remain a formidable barrier, any meaningful execution misstep by NVIDIA or a sudden breakthrough by a competitor could alter the competitive equilibrium.
5. Portfolio Concentration Risk and psychological discipline
Beyond spreadsheets, valuation models, and macroeconomic forecasts, deciding whether to sell NVDA often comes down to personal portfolio construction and psychological risk tolerance.
The Danger of Over-Concentration
Many retail and institutional investors who bought NVIDIA years ago now find that a single stock represents an uncomfortably large percentage of their total net worth or portfolio value. When one asset grows exponentially, it distorts asset allocation.
If NVIDIA makes up 30%, 40%, or more of your portfolio, your financial well-being is tied to the cyclicality of a single industry and a single company. Even if you remain deeply bullish on NVIDIA’s ten-year outlook, holding an overly concentrated position exposes you to sharp, gut-wrenching volatility that can disrupt your broader financial plan.
Tax implications and opportunity cost
Selling a winning position also brings the reality of capital gains taxes and the challenge of capital redeployment. If you sell, where will that money go? Are there other asset classes, defensive sectors, or undervalued opportunities that offer a better risk-adjusted return profile for the coming years?
In Part 2 of this analysis, we will examine tactical exit strategies, portfolio rebalancing frameworks, tax-efficient profit-taking methods, and specific diagnostic questions you can ask yourself to determine your exact exit threshold.
Navigating the volatility: The fundamental reality
To understand whether you should sell your NVIDIA (NVDA) stock in the current market environment, we must separate short-term market psychology from structural enterprise reality. Over the past several weeks, the stock has experienced dramatic downward pressure, shifting from all-time highs near $240 down toward the $125–$135 range. This correction has been compounded by severe headline risk, including leadership transition uncertainty and broader macro anxieties across the technology sector.
However, panic-driven sell-offs frequently obscure underlying business fundamentals. Even amid compressed valuation multiples, with both trailing and forward price-to-earnings (P/E) ratios dropping to historically low levels near 13x to 15x, NVIDIA’s core revenue generation and cash-flow characteristics remain fundamentally distinct from typical cyclical downturns.
The bull case: Why holding makes sense
For long-term investors evaluating their positions, several powerful structural pillars support a "hold" or even an accumulation strategy:
Unprecedented Data Center Demand: Hyperscale cloud providers and enterprise buyers continue to spend heavily on artificial intelligence infrastructure. While growth rates naturally normalize from triple-digit expansion, absolute capital expenditures directed toward AI compute clusters remain exceptionally high.
The Vera Rubin Platform Transition: Following the immense commercial rollout of its architecture updates, next-generation platforms like Vera Rubin are capturing robust initial capital, demonstrating that technological leadership has not stalled.
Diversified Hardware and Software Ecosystem: NVIDIA is no longer merely a graphics card vendor. It operates an integrated ecosystem spanning GPUs, central processing units (CPUs), custom networking fabrics, and enterprise software suites that create high switching costs for major enterprise clients.
Attractive Valuation Compression: Because earnings growth has outpaced stock price appreciation over recent quarters, NVIDIA trades at valuation multiples significantly lower than its historical three-year averages. For value-oriented growth investors, this represents a major reset in entry price risk.
The bear case: Valid reasons to trim or Sell
Conversely, holding a concentrated mega-cap stock through acute volatility is not suitable for every investor. You should seriously consider trimming or exiting your position if:
Portfolio Concentration Risk: If NVDA represents an outsized percentage of your total net worth (e.g., over 20-30%), rebalancing to reduce single-stock risk is a prudent fiduciary step, regardless of how strong the company is.
Uncertainty in Executive Leadership: Changes at the top introduce strategic execution risks. If you lack the risk tolerance to ride out leadership transitions and macro headwinds, preserving capital may bring you greater peace of mind.
Macro and Regulatory Headwinds: Ongoing geopolitical dynamics, international trade restrictions, and potential tightening of export controls continue to pose unpredictable ceilings on international revenue segments.
Strategic framework: How to decide Your next move
The decision to sell should not be driven by emotional reactions to daily ticker fluctuations. Ask yourself three defining questions:
What was your original investment thesis? If you bought NVIDIA because you believed in the multi-year secular transformation toward accelerated computing and enterprise AI, and that thesis remains intact, short-term price drawdowns are simply part of the cost of admission.
Do you need the capital in the near term? Money needed within the next 3 to 5 years should never be exposed to high-beta equity volatility.
Are you panic-selling or rebalancing? Selling to lock in losses out of fear typically destroys long-term wealth, whereas selling to manage portfolio risk is disciplined asset management.
If your risk tolerance is aligned with technology sector volatility and your time horizon spans multiple years, maintaining your position or patient accumulation through weakness historically rewards disciplined investors. If, however, the price swings disrupt your sleep or break your risk parameters, scaling out incrementally allows you to rationalize your exposure safely.