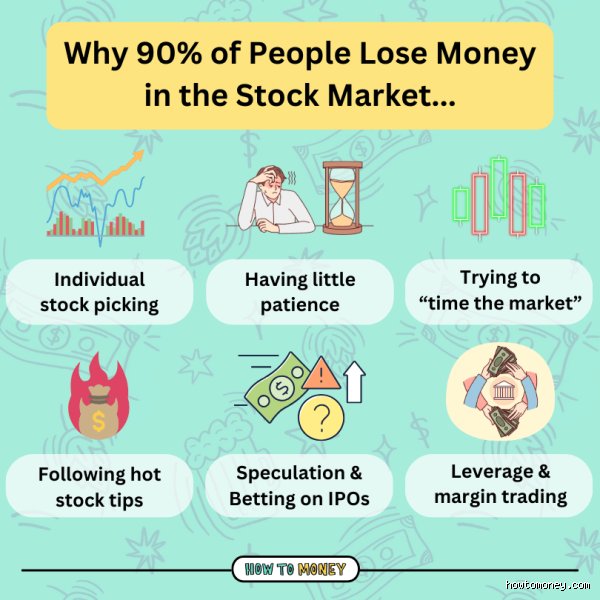
Decoding the myth and reality of stock market losses
This dichotomy raises a critical question for anyone looking at contemporary wealth-building: Are people actually losing a lot of money in the stock market? To answer this objectively, we must move past casual anecdotes and examine the structural, behavioral, and economic realities that govern modern equity participation.
The structural landscape: Who wins and who loses?
To understand how money moves in the stock market, it helps to view the ecosystem not as a friendly community of equal savers, but as an arena dominated by institutional giants—pension funds, sovereign wealth funds, insurance conglomerates, and algorithmic high-frequency trading firms.
Data compiled across global regulatory bodies consistently reveals a sobering statistic: between 70% and 80% (and often higher, depending on the asset class and leverage used) of retail traders operating through short-term vehicles like Contracts for Difference (CFDs), options, or aggressive day-trading accounts report net losses.
+------------------------------------------------------------+
| THE RETAIL PERFORMANCE GAP |
+------------------------------------------------------------+
| Institutional Layer: Deep capital, advanced data tools, |
| macro foresight, and patient multi-year horizons. |
+------------------------------------------------------------+
| Retail Trading Layer: High transaction frequency, |
| emotional exposure, leverage risk, and noise addiction. |
+------------------------------------------------------------+
When individual participants enter the market looking for quick capital gains, they frequently find themselves on the opposite side of transactions executed by institutional entities that possess dedicated research teams, macro-economic forecasting models, and deep liquidity buffers. Consequently, the perception that "people are losing money" is often accurate for those treating the market like a speculative casino, whereas long-term index investors experience entirely different outcomes.
Behavioral finance: The anatomy of Self-Inflicted losses
While macroeconomic downturns, geopolitical tensions, and sudden sector corrections (such as cyclical tech and energy shocks) trigger market-wide pullbacks, a significant portion of individual losses cannot be blamed on bad luck alone. Behavioral finance points to deeply ingrained psychological traps that sabotage investor portfolios.
1. The trap of chasing momentum (FOMO)
A classic error driving retail losses is buying into assets after they have already experienced parabolic price expansion. Spurred by viral social media discussions, sensationalized headlines, and the Fear of Missing Out (FOMO), everyday investors frequently purchase shares at peak valuations. By the time retail capital floods in, institutional players are often quietly distributing, selling their positions to locking in profits, leaving latecomers vulnerable to sharp corrections.
2. The asymmetry of Fear and greed
Human psychology is fundamentally unsuited for raw financial trading without strict discipline. Research into trading frequency famously conducted by academics like Brad Barber and Terrance Odean demonstrates that active individual traders systematically underperform the broader market, with net returns deteriorating in direct proportion to how often they trade. This underperformance stems from a toxic cycle:
Buying high out of overconfidence and greed during market peaks.
Panic selling low during routine volatility or market corrections out of terror.
A Little-Known aspect: The hidden erosion of transaction frictions and slippage
While dramatic crashes make newspaper headlines, a stealthier mechanism drains capital from active market participants every single day: friction costs.
Many retail investors focus exclusively on the purchase price of a stock versus its future value, completely ignoring the structural drag of:
Bid-Ask Spreads: The hidden gap between the price a buyer is willing to pay and what a seller is willing to accept.
Slippage: The execution difference between the expected price of a trade and the actual price at which it is filled during volatile market phases.
Commissions and Financing Costs: Particularly relevant for leveraged accounts, overnight holding fees and transaction commissions compound silently. Over dozens or hundreds of trades a year, these micro-losses accumulate, transforming a theoretically break-even strategy into a net-negative portfolio drain.
The evolution of Risk: Leverage and modern speculation
Another crucial development shaping modern losses is the democratization of advanced financial instruments. Decades ago, individual investors faced high barriers to entry, high commission fees, and limited access to complex derivatives. Today, smartphone apps grant retail users instant access to margin accounts, options contracts, and high-leverage products with a single tap.
When combined with an incomplete understanding of risk management, such as failing to set predetermined exit boundaries or mismanaging position sizes relative to account equity, this accessibility transforms minor market fluctuations into catastrophic account liquidations. The risk is no longer just that a company's stock drops by 10%; the risk is that a 5% adverse move on a heavily leveraged position wipes out 100% of the trader's capital.
What specific strategies or asset classes do you think pose the highest hidden risks for everyday market participants today?
Navigating the volatility: Who bears the brunt of market corrections?
To fully understand whether people are losing substantial sums of money in the stock market, one must look past headline index numbers and examine the micro-dynamics of investor behavior. While major benchmarks like the S&P 500 or the FTSE 100 often reflect long-term upward trajectories or mild annual corrections, aggregate numbers mask deep disparities. The reality of "losing money" is rarely distributed evenly; instead, it heavily concentrates among specific participant profiles driven by distinct psychological and tactical missteps.
The anatomy of Retail investor vulnerability
Institutional investors, such as pension funds, sovereign wealth funds, and large asset managers, operate with sophisticated risk-management frameworks, vast liquidity cushions, and multi-year time horizons. Consequently, they can weather sharp drawdowns without needing to liquidate assets at a bottom.
In contrast, individual retail investors frequently fall prey to structural and behavioral disadvantages:
The Seduction of High-Beta Sectors and Hype Cycles: During periods of rapid technological shifts, such as the massive capital injections into artificial intelligence, clean energy, or biotechnology, retail participation surges. Chasing parabolic gains often leads late-stage market entrants to buy near cyclical peaks. When sentiment shifts or valuations face gravity, these latecomers experience the steepest paper losses.
Overreliance on Leverage and Derivatives: The accessibility of modern trading apps has democratized access to options trading, margin accounts, and leveraged exchange-traded funds (ETFs). While these instruments amplify gains in a bull market, they accelerate total capital destruction during sudden market corrections. A single bad week in a high-beta sector can completely wipe out an unhedged leveraged portfolio.
Panic Selling and Emotional Cycling: Behavioral finance studies consistently show that individual investors underperform the very funds they hold. This performance gap is primarily driven by "prospect theory", the psychological reality that the pain of losing money is psychologically twice as intense as the joy of making it. Frightened by sudden double-digit pullbacks, retail traders frequently sell at the trough, locking in permanent losses rather than riding out the volatility.
The illusion of "paper losses" versus realized destruction
A critical distinction in evaluating market health is differentiating between unrealized losses (paper losses) and realized losses.
When a broad market index undergoes an interim drawdown, historically averaging a 14% to 16% peak-to-trough decline even in typical years, millions of portfolios technically register steep drops in value. However, for passive, long-term investors utilizing diversified index funds, these are merely temporary fluctuations. History demonstrates that diversified markets systematically recover and eventually eclipse previous highs, rendering paper losses temporary.
The true financial damage occurs when investors engage in forced or emotional realization:
Liquidity Crunches: If a market downturn coincides with macroeconomic pressures, such as rising interest rates, inflation spikes, or localized job insecurity, investors may be forced to sell equities at a loss to cover immediate living expenses.
Concentration Risk: Investors holding individual stocks rather than broad-index baskets face company-specific catastrophes. If a heavily weighted portfolio stock suffers structural business failure or regulatory crackdowns, the loss is permanent and irreversible.
Mitigating Risk: Lessons from market Cycles
Avoiding significant capital destruction in the stock market requires adherence to time-tested principles rather than timing the market perfectly. Financial experts universally emphasize several defensive strategies:
Asset Allocation and Diversification: Spreading capital across geographies, asset classes (such as fixed income and equities), and sectors cushions the blow when specific industries, such as technology or banking, undergo localized corrections.
Dollar-Cost Averaging (DCA): Systematically investing fixed amounts at regular intervals removes the emotional burden of finding the "perfect entry point." DCA naturally acquires more shares when prices are low and fewer when prices are high.
Maintaining an Emergency Fund: Keeping three to six months of living expenses in cash or liquid cash equivalents ensures that a sudden personal financial crunch will never force the liquidation of long-term investments during a market downturn.
Conclusion
So, are people losing a lot of money in the stock market? The answer is nuanced. Passive, disciplined, and diversified investors primarily experience temporary paper fluctuations that smooth out over long horizons. However, speculative traders, those relying on excessive leverage, and individuals who panic-sell during routine market drawdowns routinely suffer severe, permanent capital destruction. The stock market acts as a wealth transfer mechanism, shifting capital from the impatient, over-leveraged, and emotional participant to the patient, disciplined, and prepared long-term planner.