Decoding the Downturn: The Counterintuitive Economics of Recessions
When the macroeconomic machinery stutters and market capitalization evaporates, a collective panic grips Main Street and Wall Street alike. Conventional financial advice dictates a defensive crouch: hoard cash, liquidate high-risk assets, and wait out the storm. However, looking at history through the lens of pure survival misses a vital truth. I have watched countless investors freeze during downturns, failing to realize that contractions do not destroy capital; they merely relocate it.
To understand what actually makes the most money during a recession, you must unlearn the comforting myth that all businesses suffer equally when the gross domestic product dips. In truth, economic contractions operate like a massive corporate forest fire. They clear out the deadwood, choke off bloated competitors, and concentrate immense market share into the hands of a lethal few. We often assume that luxury brands or high-growth tech start-ups command the highest earnings, but during a systemic crunch, the most lucrative enterprises are those structured to profit from human anxiety, operational friction, and structural desperation.
The Death of Discretionary Spending and the Rise of "Trading Down"
When consumer confidence collapses, spending patterns undergo a predictable yet violent shift. You might think that retail entirely shuts down, but the money does not vanish; it migrates. This phenomenon is known as "trading down."
Consider an unexpected comparison: a luxury dining establishment and a discount dollar retailer. In a booming economy, the high-end steakhouse rakes in massive margins. Yet, the moment a recession bites, that same establishment bleeds cash as consumers cut non-essentials. Conversely, discount chains, pawnshops, and second-hand thrift ecosystems experience an aggressive surge in volume.
The Psychology of Tightening Wallets: Consumers refuse to stop consuming entirely, but they demand a lower price point for equivalent utility.
The Margin Transformation: High-volume, low-margin value stores suddenly capture the customer base of mid-tier competitors who failed to adapt.
Hence, businesses catering to absolute baseline necessities—discount groceries, generic pharmaceuticals, and budget-friendly household goods—frequently report record-breaking revenues while the broader market bleeds. They do not just survive the winter; they harvest the assets of the fallen.
Capitalizing on Distress: The Liquidity Paradox
Another persistent misconception is that cash is merely a safe pillow to rest on while asset prices plummet. In reality, concentrated liquidity during a recession functions as an apex predator. When credit markets freeze and banks pull back their lending lines, liquidity becomes the rarest and most expensive commodity on earth.
As a result: asset-rich, cash-poor companies find themselves cornered, forced to sell productive divisions at pennies on the dollar. Private equity firms, distressed-debt funds, and agile individual investors who maintain dry powder do not merely make money—they engineer generational wealth. They acquire cash-flowing infrastructure, commercial real estate, and intellectual property at deep structural discounts.
"In a recession, the person holding unencumbered cash is not just a participant; they are the architect of the recovery."
We must recognize that the most profitable maneuvers are rarely defensive maneuvers. While the retail investor panics over paper losses in volatile tech portfolios, institutional operators are quietly positioning themselves to buy the underlying infrastructure of tomorrow at a fraction of its replacement cost.
The Anatomy of Counter-Cyclical Powerhouses
To truly map out where the money flows, we have to look past general sectors like "healthcare" or "utilities" and examine counter-cyclical business models. These are entities whose operational demand actually accelerates when the economic engine reverses.
The Repair and Maintenance Economy: When capital expenditure slows down, consumers and corporations stop buying brand-new machinery, vehicles, and software integrations. Instead, they sweat their existing assets. Auto repair shops, HVAC technicians, and industrial maintenance providers experience massive spikes in utilization.
The Litigation and Restructuring Sector: Bankruptcy attorneys, corporate restructuring consultants, debt collection agencies, and forensic accountants print money during a downturn. When contracts fail and debt covenants are breached, the legal machinery required to untangle the mess becomes immensely lucrative.
Ultimately, making money during a recession requires a fundamental shift in perspective. You cannot win a contraction by playing the expansion playbook. By understanding where the forced migrations of capital occur, you position yourself to profit from the exact forces that ruin everyone else.
To explore how these principles translate into specific asset classes and actionable portfolio strategies for the upcoming market cycles, continue to the second part of this analysis.
This video provides a helpful visual breakdown of essential businesses and service sectors that maintain strong cash flows and profitability when consumer spending habits shift during economic downturns.
Defensive Sectors: The Utilities, Healthcare, and Consumer Staples Playbook
When macroeconomic indicators flash red and corporate earnings begin to contract, the broader stock market frequently undergoes a severe valuation contraction. However, capital does not simply vanish from the financial ecosystem during a downturn; rather, it rotates aggressively. Investors retreat from high-beta, growth-oriented equities—which rely heavily on future cash flows and loose monetary policy—and seek refuge in defensive sectors. These industries provide inelastic goods and services, meaning consumer demand remains largely stable regardless of economic velocity.
Utilities: The Regulated Yield Haven
Utilities represent the quintessential defensive asset class. Comprising electric, gas, water, and multi-utility providers, these corporations operate under heavily regulated monopolistic or oligopolistic frameworks. Because households and businesses require electricity and water irrespective of a recession, utility revenues exhibit remarkably low correlation with gross domestic product (GDP) cycles.
Cash Flow Predictability: Regulators typically guarantee these companies a fixed rate of return on their capital expenditures. This insulates their top-line earnings from cyclical shocks.
Dividend Yield Appeal: In low-rate or recessionary environments where central banks frequently cut interest rates to stimulate growth, the stable, high-yield dividends paid by utility giants (such as NextEra Energy, Duke Energy, or Consolidated Edison) become exceptionally attractive relative to fixed-income yields.
Healthcare: Secular Growth Independent of Economic Cycles
Healthcare is fundamentally decoupled from the macroeconomic cycle. Aging demographics, chronic disease management, and acute medical emergencies create a continuous, inelastic demand curve for pharmaceuticals, medical devices, biotechnology, and healthcare services.
Defensive Moats: Large-cap pharmaceutical firms (e.g., Johnson & Johnson, Pfizer) and major health insurers possess robust balance sheets, substantial cash reserves, and pricing power that shields them from inflationary cost pressures.
R&D Resilience: Even during severe contractions, spending on essential therapeutics and hospital care remains non-discretionary, maintaining institutional cash inflows.
Consumer Staples: The Essentials Economy
Consumer staples encompass everyday necessities: food, beverages, hygiene products, and household goods. Corporations like Procter & Gamble, Walmart, and PepsiCo thrive during recessions due to consumer behavior shifts. As discretionary budgets shrink, consumers substitute dining out for cooking at home and trade down from luxury brands to private-label or mass-market staples, directly benefiting mega-cap retailers and packaged-goods manufacturers.
Alternative Assets, Counter-Cyclical Plays, and Liquidity Arbitrage
Beyond traditional defensive equities, sophisticated market participants look toward alternative asset classes and specific business models that historically generate positive alpha or store value during systemic stress.
Discount Retailers and Off-Price Models
Economic contraction compresses middle- and lower-income household budgets, forcing a pervasive cost-consciousness across the retail landscape. Off-price apparel chains (such as TJX Companies) and extreme-value grocery or discount stores (such as Dollar General or Walmart) frequently experience volume surges during downturns. As consumers hunt for value, these enterprises capture market share from mid-tier department stores and specialty retailers.
Distressed Debt, Turnaround Private Equity, and Bankruptcy Investing
Recessions invariably trigger liquidity crises for over-leveraged corporations. This environment opens lucrative avenues for specialized alternative investment strategies:
Distressed Debt Funds: Investors with locked-up capital deploy dry powder to purchase corporate bonds and bank loans trading at deep discounts to par value, anticipating successful restructuring or asset liquidation recoveries.
Non-Performing Loan (NPL) Portfolios: Financial institutions looking to clean up balance sheets offload distressed real estate or consumer loan portfolios at distressed valuations, yielding high risk-adjusted returns for well-capitalized buyers.
Counter-Cyclical Hedging and Gold
While cash and short-term U.S. Treasury bills serve as ultimate liquidity instruments during acute panic phases, physical gold and gold mining equities often function as traditional safe-haven assets. When fiat currencies face devaluation pressures from aggressive monetary expansion or fiscal stimulus deployed to fight recessions, gold retains its purchasing power, drawing substantial institutional capital inflows.
Cash Flow Engineering and Strategic Positioning for Capital Deployment
Making money during a recession is not merely about owning the right defensive tickers; it is fundamentally about liquidity management, balance sheet strength, and dry powder readiness. Asset prices frequently overshoot to the downside during panic-driven liquidations, creating generational entry points for distressed or mispriced assets.
The Power of Liquidity and Optionality
In a liquidity crunch, cash is a high-yielding call option on future distressed assets. Investors who maintain low leverage and high cash allocations avoid forced selling. When credit markets freeze, cash-rich entities can acquire competitors at a fraction of their peak valuations, buy distressed real estate portfolios, or accumulate high-yielding equities while market capitalization multiples contract.
Strategic Capital Allocation Framework
To capitalize effectively on a recessionary environment without exposing yourself to undue systematic risk, execute a disciplined, phased accumulation strategy:
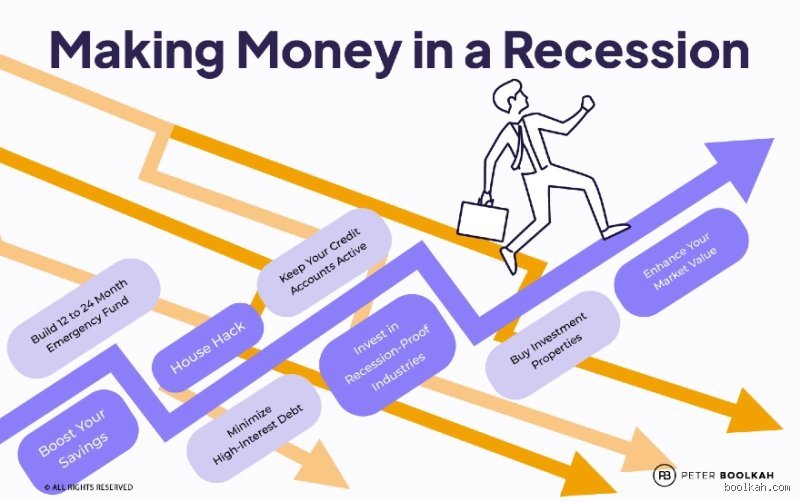
Audit and Fortress Your Personal Balance Sheet: Eliminate high-interest variable-rate debt immediately, as central bank rate cuts may lag behind individual cash flow distress. Establish a dedicated liquid cash reserve covering 6 to 12 months of essential living expenses in a high-yield savings vehicle.
Rotate into Defensive and Inelastic Sectors: Reallocate growth-heavy equity exposure toward cash-generative, dividend-paying companies within the utilities, healthcare, and consumer staples sectors that exhibit low beta and strong pricing power.
Build a Watchlist of High-Quality Cyclicals: Identify world-class cyclical corporations (in industrials, technology, or materials) whose stock prices will inevitably be dragged down indiscriminately during the broader market sell-off.
Execute Dollar-Cost Averaging (DCA) During Peak Pessimism: Rather than attempting to time the exact market bottom, deploy your accumulated liquidity in structured tranches as asset valuations hit historical support levels, ensuring long-term capital appreciation as the macroeconomic cycle eventually recovers.