Managing personal finances often feels like trying to navigate a dense maze without a map. Because life moves quickly, unexpected expenses and shifting priorities can easily derail even the best intentions. (Many people find that traditional, hyper-detailed budgeting methods cause more stress than they alleviate.) Finding a structured yet flexible approach to your income is essential for building long-term financial security without feeling constantly restricted.
What Is the 50/30/20 Budget Rule?
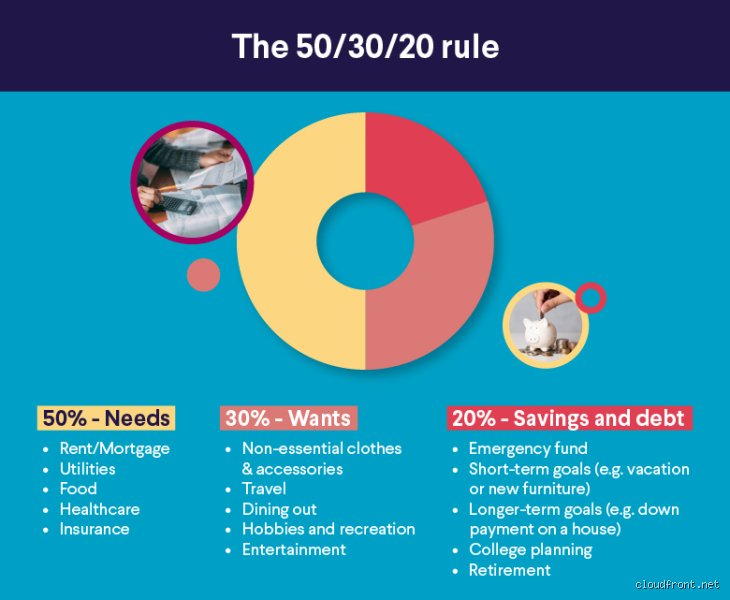
The 50/30/20 budget rule is a popular, straightforward framework designed to simplify how you allocate your after-tax income. Popularized by Senator Elizabeth Warren and her daughter Amelia Warren Tyagi in their book All Your Worth: The Ultimate Lifetime Money Plan, this framework divides your net monthly earnings into three distinct categories:
50% for Needs: Essential living expenses required for survival and basic functioning.
30% for Wants: Lifestyle choices, entertainment, and non-essential personal preferences.
20% for Savings and Debt Repayment: Financial goals that build future stability and reduce liabilities.
And because financial clarity begins with understanding where every dollar goes, let us break down each component of this framework in detail.
Category 1: The 50% Allocation for Needs
Your needs represent the absolute baseline of your cost of living. Because failing to pay these bills carries immediate legal, physical, or professional consequences, they take top priority in the 50/30/20 model.
Housing and Utilities: Rent or mortgage payments, electricity, water, gas, and internet services.
Groceries: Essential food items required for home cooking and daily nutrition (excluding dining out or luxury treats).
Transportation: Car payments, auto insurance, fuel, public transit passes, and routine vehicle maintenance.
Healthcare: Health insurance premiums, essential prescription medications, and recurring doctor visits.
Minimum Debt Payments: The bare minimum required to keep your credit cards, student loans, and other debts in good standing.
Category 2: The 30% Allocation for Wants
Once your survival essentials are fully covered, the 30% bucket gives you the freedom to enjoy your hard-earned money guilt-free. Wants are everything that makes life more enjoyable, even though you could technically live without them.
Entertainment: Streaming service subscriptions, concert tickets, movie nights, and video games.
Dining Out: Restaurant meals, coffee shop runs, takeout orders, and weekend brunches.
Shopping: Non-essential clothing, hobby supplies, electronics, and home decor upgrades.
Travel and Leisure: Vacations, weekend getaways, and membership fees for social clubs or gyms.
And while distinguishing a "need" from a "want" can sometimes feel tricky—such as debating whether a premium grocery store item or a basic gym membership qualifies—maintaining strict honesty with yourself is the key to making this percentage work.
Category 3: The 20% Allocation for Savings and Debt
The final 20% of your net income is dedicated entirely to your future financial health. Because wealth accumulation requires consistent, intentional action, this bucket acts as the engine of your long-term prosperity.
Emergency Fund Building: Setting aside cash in a high-yield savings account to cover three to six months of living expenses.
Retirement Accounts: Contributing to employer-sponsored plans like a 401(k) or individual retirement arrangements (IRAs).
Aggressive Debt Payoff: Paying more than the minimum balance on high-interest debts, such as credit cards or personal loans, to eliminate them faster.
Specific Financial Goals: Saving for a down payment on a home, funding higher education, or starting a business.
Why the 50/30/20 Rule Works
Traditional budgeting often fails because tracking every single penny across dozens of micro-categories becomes exhausting. But the 50/30/20 rule removes that mental fatigue by grouping expenses into macro-targets. Because you only have to monitor three primary numbers, maintaining consistency becomes vastly easier over time.
Step-by-Step Practical Application
To apply this rule to your own finances, follow these concrete steps to calculate your numbers and establish your baseline:
Calculate Your Net Monthly Income: Look at your bank statements and determine your exact take-home pay (after taxes, retirement deductions, and health insurance are automatically subtracted).
Multiply Your Net Income by 0.50, 0.30, and 0.20: For example, if your net monthly income is $4,000, your targets are:
Needs (50%): $2,000
Wants (30%): $1,200
Savings/Debt (20%): $800
Audit Your Last 30 Days of Spending: Categorize your recent transactions into the three buckets to see how your current habits compare to the ideal percentages.
Adjust Your Lifestyle Gradually: If your needs currently consume 70% of your income, do not panic; identify areas where you can trim expenses or increase your income to bridge the gap over the coming months.
Conclusion of Part 1
Understanding the mechanics of the 50/30/20 rule gives you a powerful lens through which to view your personal finances. In the next part of this guide, we will explore advanced strategies for adapting this rule to high-cost-of-living areas, managing irregular income streams, and overcoming common budgeting pitfalls.
Putting the 50/30/20 Rule into Practice: Step-by-Step Implementation
Transitioning from theory to practice is where true financial transformation happens. While understanding the mechanics of allocating your income into needs, wants, and savings is straightforward, maintaining consistency requires a structured approach. Implementing this framework effectively transforms abstract budgeting into an automatic, stress-free habit.
Step 1: Calculate Your Net Income
Your baseline is always your take-home pay—the money that actually hits your bank account after taxes, mandatory retirement contributions (like 401(k) or pension deductions), and health insurance premiums are deducted.
Avoid calculating percentages based on your gross salary. Using gross income creates an illusion of wealth, leaving you short on cash once taxes and deductions are stripped away.
If your income fluctuates (common for freelancers or commission-based workers), base your calculations on your lowest earning month over the past year to maintain a safety buffer.
Step 2: Audit and Categorize Your Spending
Before assigning numbers to your categories, you need a clear picture of where your money currently goes. Review your bank and credit card statements from the last three months.
Separate every expense into the three buckets: Needs, Wants, and Savings/Debt.
Be honest with yourself. For example, a streaming service might feel like a necessity, but it belongs firmly in the Wants category. True needs are strictly non-negotiable items required for survival and basic functioning.
Step 3: Automate Your Finances
Willpower alone is rarely enough to sustain long-term financial habits. Automation removes human friction and temptation from the equation.
Set up direct deposits or automatic transfers that trigger immediately on payday.
Send your 20% savings and debt allocation directly to your investment accounts, high-yield savings accounts, or loan servicers before you have a chance to spend it.
Direct your 50% needs into a primary checking account used strictly for bills, rent, and groceries. The remaining balance in your main account (or a designated spending account) becomes your 30% wants allocation.
Tailoring the Framework: Real-World Adjustments
No budgeting template fits every individual or life stage perfectly. The beauty of the 50/30/20 rule lies in its scalability and adaptability. Financial circumstances change, and your budget should evolve right along with them.
High-Cost-of-Living Areas
If you reside in a major metropolitan area where housing costs consume an exorbitant share of income, keeping your needs at or below 50% can feel mathematically impossible.
The Adjustment: Temporarily flex your percentages. You might need to shift to a 60/20/20 or 65/15/20 split by trimming down your wants category until your income increases or you relocate.
The Mindset: Recognize that this adjustment is a conscious trade-off, not a failure of the system.
Aggressive Debt Paydown
Carrying high-interest debt (such as credit cards or personal loans) acts as an anchor on your net worth.
The Adjustment: If you are buried in high-interest debt, consider temporarily boosting your savings/debt bucket to 30% or higher by squeezing your wants category down to 10% or 15%.
The Goal: Once high-interest liabilities are fully eliminated, redirect those funds back into long-term wealth building, investments, or retirement vehicles.
High Earners and Accelerating Wealth
If your income climbs significantly while your core lifestyle remains modest, your needs might drop to 30% or 40% of your take-home pay.
The Adjustment: Do not feel obligated to artificially inflate your needs or wants just to match the percentages. Instead, redirect the excess surplus straight into your savings and investment bucket, pushing that category well past 20%. This strategy dramatically accelerates your timeline toward financial independence.
Common Pitfalls and How to Avoid Them
Even with the best intentions, budgeters frequently run into predictable stumbling blocks. Recognizing these traps early ensures your financial plan stays on track.
Treating the Budget as a Prison: A rigid budget that eliminates all joy is unsustainable. If your wants category is starved completely, you are bound to experience financial burnout and severe impulse-spending binges. Always protect a reasonable portion of guilt-free spending for things that genuinely bring you happiness.
Failing to Account for Irregular Expenses: Annual expenses—such as car insurance premiums, holiday gifts, medical copays, and home maintenance—frequently derail monthly budgets. To prevent this, calculate your annual irregular expenses, divide by twelve, and treat that monthly figure as an essential need.
Neglecting Emergency Funds: Before aggressively investing surplus cash, prioritize building an emergency fund covering three to six months of essential living expenses. This buffer ensures that unexpected life events, such as car repairs or job transitions, do not force you back into high-interest debt.
Conclusion
Financial stability is rarely built on grand gestures; rather, it is forged through consistent, repeatable daily habits. The 50/30/20 budget rule provides a remarkably balanced, flexible foundation that eliminates the tedious number-crunching associated with traditional, hyper-detailed budgeting methods.
By categorizing your take-home pay into predictable buckets for your essentials, your personal enjoyments, and your future security, you regain total control over your financial destiny. Whether you are aiming to crush burdensome debt, buy your first home, or simply sleep easier knowing your bills are covered, this framework adapts to your unique journey.
Begin by auditing your current spending today, automate your transfers tomorrow, and watch how intentional resource allocation turns your long-term financial dreams into an achievable reality.