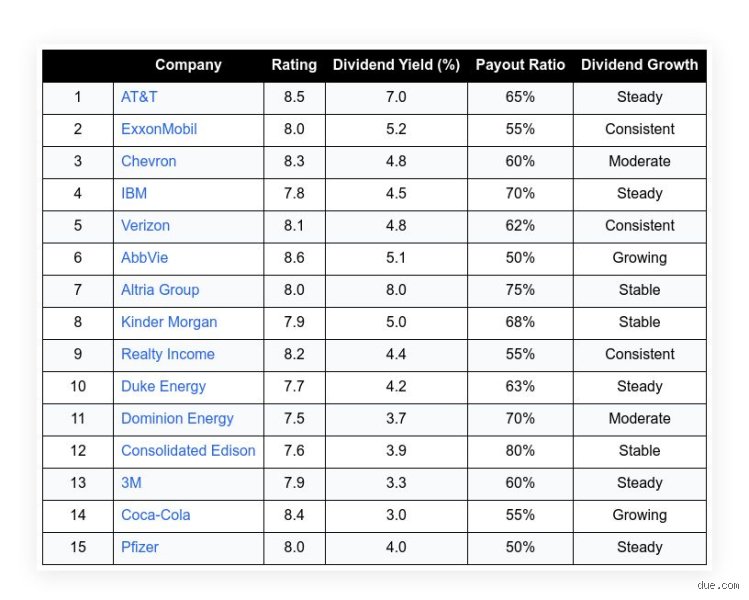
Navigating the volatile markets: Why Dividend stocks matter more than ever
How do Top-Tier Dividend portfolios outperform Growth-Only strategies?
The allure of high-yielding equities lies in their unique compounding mechanics. Rather than relying entirely on a rising share price to realize gains, shareholders receive regular cash distributions. Reinvesting these payouts through a Dividend Reinvestment Plan (DRIP) allows investors to accumulate more shares automatically over time, accelerating total portfolio growth.
The Power of Consistency: Companies capable of maintaining and growing dividend payouts for decades usually possess wide economic moats, pricing power, and disciplined management teams.
Inflation Hedge: Established corporations with robust cash flows often raise their dividends annually, frequently outpacing historical inflation rates.
Lower Volatility: Equities known for regular distributions typically experience less dramatic price swings compared to non-dividend tech or speculative startup ventures.
What separates a Sockets-Only trap from genuine Dividend Aristocrats?
Chasing the highest headline yield available on a stock screen is one of the most common mistakes novice investors make. A deceptively high yield is often a warning sign—known in financial circles as a "dividend trap"—where a plunging share price artificially inflates the yield percentage because the underlying business is deteriorating.
Why evaluating Payout ratios and free cash flow protects your capital
True investment safety comes from analyzing financial sustainability rather than raw yield numbers. A company funding its distribution entirely through sustainable free cash flow is far more reliable than one borrowing money to maintain payouts.
The Payout Ratio Benchmark: Healthy companies typically maintain a payout ratio, the proportion of earnings paid out as dividends, between 40% and 60%. Utilities and Real Estate Investment Trusts (REITs) can safely run higher ratios due to their regulated, contracted cash streams.
The Track Record Test: Organizations belonging to elite classifications like Dividend Aristocrats (minimum 25 consecutive years of increases) or Dividend Kings (50+ years) have successfully navigated recessions, high-interest-rate environments, and geopolitical shifts without breaking their streak.
Debt Load Management: Heavy corporate debt crowds out cash distributions when interest rates rise. Examining a company's balance sheet coverage ensures long-term payout survival.
Strategic portfolio construction: Building a Dividend growth engine
Selecting individual dividend stocks is only the first step; how you assemble them into a cohesive portfolio dictates your long-term success. A common pitfall for income-focused investors is chasing the highest current yield available in the market. High yields often act as a siren song, frequently signaling a "value trap", a company whose stock price has plummeted due to fundamental business deterioration, resulting in an artificially inflated yield that is ultimately unsustainable and prone to a dividend cut.
Instead of maximizing yield on day one, sophisticated investors prioritize dividend growth rate (DGR) and total return. A company yielding 2.5% that grows its payout by 10% annually will, through the magic of compounding, yield significantly more on your original cost basis in a decade than a stagnant 6% yielder. Companies capable of consistent double-digit dividend growth are typically robust, competitively advantaged businesses experiencing steady capital appreciation.
To construct a resilient dividend portfolio, consider the following allocation and management pillars:
1. Sector diversification and economic moats
Concentration risk is the silent killer of income portfolios. If your holdings are overly weighted toward a single sector, such as traditional utilities or financial institutions, an adverse regulatory shift or macroeconomic shock can devastate your cash flow. A well-rounded portfolio should span multiple defensive and cyclical sectors:
Consumer Staples & Healthcare: Provide inelastic demand, ensuring steady cash flows during recessions.
Financials & Industrials: Capture economic expansion and benefit from rising interest rate environments.
Information Technology & Communication Services: Offer lower initial yields but superior capital appreciation and dividend growth vectors.
2. The Power of Dividend Reinvestment (DRIP)
During the accumulation phase of your investment lifecycle, enabling a Dividend Reinvestment Plan (DRIP) is arguably the most powerful wealth-building tool at your disposal. By automatically routing your quarterly cash dividends back into fractional shares of the underlying equities, you harness dollar-cost averaging. When markets pull back, your dividends purchase more shares at discounted prices, exponentially accelerating your share accumulation and future income stream.
Common pitfalls to avoid in Dividend investing
Even seasoned investors occasionally fall prey to behavioral biases and analytical oversights when building income portfolios. Recognizing these traps can safeguard your capital and preserve your income stream:
Ignoring the Payout Ratio: Always examine how sustainable a dividend is by looking at the payout ratio (dividends per share divided by earnings per share). While capital-intensive businesses like REITs or utilities naturally have higher payout ratios (often 70% to 80%), a standard corporation with a payout ratio consistently exceeding 90% leaves zero margin for error should a macroeconomic downturn contract its earnings.
Neglecting Balance Sheet Health: A company can maintain a pristine dividend track record for decades while quietly accumulating a mountain of toxic debt. When debt maturities arrive in a high-interest-rate environment, servicing those liabilities will almost always take precedence over shareholder payouts, leading to sudden, devastating dividend suspensions. Always screen for manageable debt-to-equity ratios and solid investment-grade credit ratings.
Chasing Yield Over Quality: As previously emphasized, a double-digit yield is almost universally a warning sign, not a bargain. Prioritize companies with wide economic moats, predictable cash generation, and management teams explicitly committed to shareholder returns over flashy, short-term payouts.
Frequently asked questions
What is the difference between dividend yield and dividend growth?
Dividend yield measures the annual income a company pays relative to its current share price, expressed as a percentage. For example, a stock trading at $100 that pays $3 annually has a 3% yield. Dividend growth, on the other hand, measures the rate at which the company increases its dividend payment over time (e.g., raising the payout from $3.00 to $3.30, representing a 10% growth rate). While yield provides immediate income, dividend growth protects your purchasing power against inflation and typically correlates with superior long-term stock performance.
How often are dividends typically paid?
In the United States and many global markets, the vast majority of dividend-paying stocks distribute cash to shareholders on a quarterly basis (four times a year). However, a select group of companies, particularly Canadian equities, European multinationals, and certain Real Estate Investment Trusts (REITs), pay monthly dividends, which can be particularly attractive for retirees or investors seeking to match monthly living expenses.
Are dividends guaranteed?
Unlike bond coupons, which represent a legal obligation of the issuer backed by the full faith and credit of the corporation, dividends are entirely discretionary. They must be formally declared by a company’s Board of Directors each period. If a business experiences a severe liquidity crunch, regulatory penalty, or operational downturn, the Board can, and often must, reduce or completely eliminate the dividend to preserve corporate survival. This is why thorough fundamental analysis of cash flows and balance sheets is non-negotiable.
How are dividends taxed?
Taxation on dividends varies significantly depending on your jurisdiction and the type of account holding the assets. In the U.S., qualified dividends, those met by holding the underlying stock for more than 60 days during a specific window around the ex-dividend date, are taxed at preferential long-term capital gains tax rates (0%, 15%, or 20% depending on taxable income brackets). Conversely, unqualified or ordinary dividends are taxed at ordinary income tax rates. Utilizing tax-advantaged accounts such as IRAs, Roth IRAs, or 401(k)s can defer or entirely eliminate these tax burdens, maximizing the compounding velocity of your portfolio.