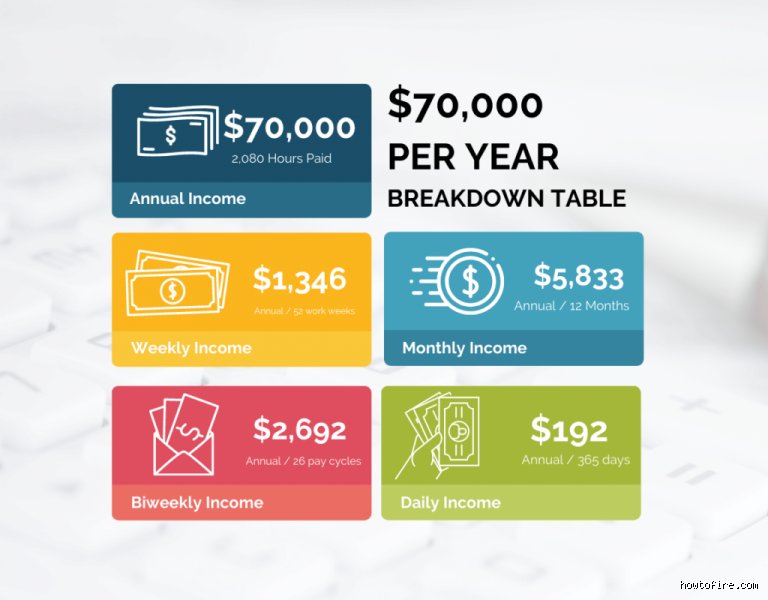
Breaking down the math: What does this number even mean?
The gross calculation is the easy part. You take seventy thousand, divide it by twelve, and you get the baseline figure we just mentioned. But your employer looks at that number as a line-item expense, whereas you have to look at it as a shrinking block of ice in the summer sun.
The disconnect between gross and net
Let’s be real here. Nobody walks away with five grand and change every single month, except perhaps in some tax-haven fantasy. The moment that money leaves the corporate accounting department, it gets chipped away by federal mandates, state obligations, and local levies. It's a psychological gut punch for many young professionals. I remember looking at my first major paycheck and genuinely wondering if there had been a banking glitch—there hadn't, of course, just the harsh reality of withholding status. That changes a lot about how you plan your life.
How pay frequency distorts your reality
The complication is how that annual figure gets chopped up over the calendar year. If you get paid twice a month, usually on the 15th and the 30th, your monthly income matches that $5,833 gross expectation perfectly. But what if your company utilizes a biweekly schedule? That means twenty-six paychecks. For ten months of the year, your monthly gross is actually lower—around $5,384, and then, twice a year, you get those magical "three-paycheck months" where you suddenly feel flush. It is a bizarre budgeting illusion that catches people off guard.
The taxman cometh: Shaving off the first layers
This is where your $70,000 annual salary takes its first major hit, and it's unclear why more high schools don't teach this specific mechanics before pushing kids into the workforce. Your take-home pay is entirely dependent on geography and your personal filing status.
Federal tax brackets and FICA deductions
First, the federal government takes its share through a progressive tax system. In 2026, a single filer earning seventy grand won't see their entire income taxed at one flat rate. Instead, the money moves through the 10%, 12%, and 22% brackets sequentially. On top of that, FICA takes a flat 6.2% for Social Security and 1.45% for Medicare. That is a mandatory 7.65% haircut right off the top before we even discuss where you live.
The massive geographic divide
Let's look at two specific examples to show how much your location dictates your financial freedom. If you are working a remote tech support job out of Austin, Texas, you enjoy zero state income tax. Your estimated monthly take-home pay after federal taxes and FICA hover around $4,720. Now, let’s move that exact same job to San Francisco, California. Suddenly, Sacramento wants its piece, and your monthly net drops closer to $4,310. That is a $410 monthly difference just for crossing state lines! It is the exact same labor, but a completely different standard of living.
The deductions you choose (and the ones you don't)
Once the government satisfies its appetite, your employer’s HR department steps in to deduct your chosen benefits. This is the second phase of the shrinking ice block, and it is highly customizable.
Health insurance and the medical premium tax
Medical benefits are a wild card. A single person opting for a high-deductible health plan might only pay $80 a month, yet a parent opting for a comprehensive family plan could easily see $450 vanished from their monthly income before the check hits their account. These are pre-tax deductions, which does provide a minor silver lining by lowering your overall taxable income. Yet, the issue remains: it is money you cannot spend on groceries or a car payment.
Retirement contributions: Future you vs. Present you
We are constantly bombarded with advice saying we must save 15% of our income for the future. If you put 10% of your seventy-thousand-dollar salary into a traditional 401(k), which is about $583 a month, you are doing great for your sixty-year-old self. But you are also reducing your current monthly cash flow significantly. Combined with taxes and insurance, that Austin resident who started with $5,833 in gross income is now looking at a disposable income of roughly $3,800 a month. We're far from that initial five-thousand-dollar figure now, aren't we?
How does a ,000 annual salary compare globally and domestically?
To understand if this is good money, we need context. Conventional wisdom says seventy grand is the sweet spot of American comfort, a narrative driven by outdated studies from over a decade ago.
Above the median, but below the hype
The current median household income in the United States floats somewhere around $75,000, meaning an individual earning seventy thousand on their own is doing remarkably well compared to the general population. You are out-earning a vast majority of workers worldwide. In many Midwestern towns, like Peoria, Illinois, this income allows you to buy a three-bedroom house, drive a reliable SUV, and take a nice vacation to Florida every summer without breaking a sweat. As a result, you feel rich.
The Cost-of-Living Equalizer
But try taking that exact same income to Manhattan or Seattle. In those environments, seventy thousand dollars places you uncomfortably close to the living-wage ceiling for a single person. Rent alone for a modest studio apartment can easily swallow $2,500 a month, which is over 60% of your actual net take-home pay if you are saving for retirement. Specialists don't agree on whether remote work will permanently fix this imbalance, but for now, the purchasing power of your monthly check is completely tethered to your zip code.
Common misconceptions when calculating your Take-Home pay
The "Divide by Twelve" Illusion
You cannot simply divide $70,000 by twelve and expect to find $5,833 waiting in your checking account every month. That is the quickest path to financial disappointment. The problem is that gross earnings and net liquidity belong to entirely different universes. Federal taxes, state levies, and local ordinances immediately claw back a massive portion of that sum before you ever see a dime. Depending on your zip code, that nominal figure shrinks by 20% to 30% instantly.
Ignoring the Three-Paycheck month phenomenon
Biweekly pay schedules throw a massive wrench into standard monthly budgeting. If your employer pays you every two weeks, you receive 26 paychecks a year rather than 24. Most months will contain exactly two paychecks, which explains why your regular monthly baseline feels artificially low. Twice a year, however, you will experience a "magic month" featuring three paychecks. Counting on that bonus cash for your regular January rent is a catastrophic error; those extra funds should be funneled straight into long-term savings instead.
Underestimating Pre-Tax deductions
Health insurance premiums, dental plans, and 401k contributions drastically erode your nominal compensation. A standard 4% retirement match takes $233 out of your monthly rotation immediately. When you layer family medical coverage on top of that, your liquid cash flow drops even further. Many workers calculate their housing allowance based on their gross contractual offer. Do not make this mistake, or you will find yourself drowning in fixed costs.
The Inflation-Adjusted reality of a k salary
The purchasing power disparity
The geographic location where you cash your paycheck dictates its actual velocity. In a high-cost metropolis like San Francisco or New York, a $70,000 annual income provides a lifestyle that feels remarkably close to paycheck-to-paycheck survival. Conversely, that exact same compensation package allows for unprecedented lifestyle flexibility in cities like Cleveland or Indianapolis. Inflation has eroded the baseline comfort this specific bracket used to guarantee. Yet, we must acknowledge that a single person can still live quite comfortably on this amount if they master the art of aggressive prioritization. The real issue is that societal expectations often outpace real wage growth, forcing mid-tier earners into uncomfortable compromises. You might need to sacrifice trendy dinners to fund your investment accounts, which is the harsh reality of modern middle-class economics.Frequently asked questions
Is ,000 a year considered a good salary for a single person?
Yes, this amount sits comfortably above the median individual income in the United States, granting a single worker solid financial stability. A single earner can easily cover standard necessities while simultaneously maintaining a healthy emergency fund of $15,000 or more. The situation shifts dramatically if you support dependents or carry massive student loan obligations over $50,000. For a solo individual living in a mid-sized market, however, this wage provides an excellent foundation for wealth accumulation and comfortable living.How much can I afford to spend on rent making k annually?
Using the traditional 30% rule of thumb, an individual earning this wage should cap their monthly housing expenses at roughly $1,750. However, because your actual monthly take-home pay lands closer to $4,200 after standard payroll deductions, spending that much on rent might leave your budget feeling incredibly tight. Aiming for a monthly rent payment between $1,200 and $1,400 provides much-needed breathing room for your other financial goals. Did you really enter the workforce just to hand your entire paycheck over to a landlord?
What is the hourly rate for someone earning ,000 per year?
Assuming a standard 40-hour work week across 52 weeks a year, this annual compensation translates directly to an hourly wage of exactly $33.65. This calculation changes slightly if your position grants you paid time off, though the baseline value of your labor remains identical. Salaried employees often work closer to 45 or 50 hours during peak operational seasons, which subtly dilutes that hourly valuation down to roughly $28.00 per hour. Understanding this conversion helps you evaluate whether freelance opportunities or overtime shifts are genuinely worth your time.