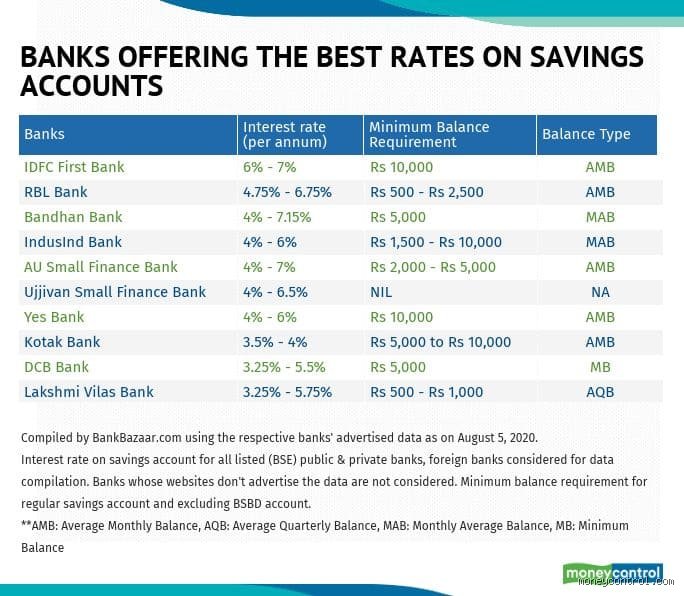
Decoding the 7% interest landscape: Myth, reality, and specialized Accounts
The short answer is nuanced: Yes, accounts offering 7% interest do exist, but they are rarely traditional, unlimited high-yield savings vehicles. Instead, these headline-grabbing rates are almost always found within tightly structured product categories, such as monthly regular saver accounts with strict deposit limits, reward checking accounts with specific transaction hurdles, or temporary promotional incentives.
Understanding how these rates work requires peeling back the marketing layers to examine the mechanics, restrictions, and fine print governing high-yield banking products.
The anatomy of High-Yield discrepancies: Why 7% is rare
To understand where a 7% interest rate comes from, you must first understand how banks manage the cost of capital. Banks make money by lending out deposits at higher rates than they pay to account holders. When central bank interest rates fluctuate, institutions adjust what they are willing to pay for consumer liquidity.
While standard online high-yield savings accounts (HYSAs) typically max out in the 3.5% to 5.0% range depending on current market trends, financial institutions occasionally push past 6% or 7% as a loss-leader or acquisition strategy. However, to protect themselves from paying massive interest expenses on large sums of capital, banks apply specific structural limitations:
Balance Caps: A bank might proudly advertise 7% interest, but restrict that rate to the first $500, $1,000, or $3,000 of your balance. Any amount saved above that ceiling usually earns a dramatically lower standard variable rate (sometimes close to 0.10% or 0.50%).
Monthly Contribution Limits: Regular savings products (frequently structured as 12-month fixed saver accounts) limit how much new cash you can inject monthly, often capping deposits at £250 to £300 per month. This prevents you from dumping a large lump sum of $50,000 into the account to reap a 7% return on the total.
Activity Hurdles: Many "rewards checking" or high-tier hybrid accounts require you to jump through operational hoops. This can include maintaining a recurring monthly direct deposit threshold, executing 10 to 30 debit card transactions per month, or opting exclusively for electronic statements. Failing to meet just one criterion for a single statement cycle can instantly forfeit your high interest rate for that month.
Regular Saver Accounts vs. Unlimited HYSAs
When navigating the search for top-tier yields, it is vital to distinguish between the two primary formats that approach or hit the 7% threshold:
+-----------------------------------+-----------------------------------+
| Regular Saver Accounts | Reward Checking & Hybrid Accounts |
+-----------------------------------+-----------------------------------+
| • Fixed or variable rate for 12 | • High yields tied to active debit|
| months | card usage or direct deposits. |
| • Strict monthly deposit caps | • Strict balance caps (e.g., max |
| (e.g., $200–$300/mo)| $500 to $15,000). |
| • Ideal for disciplined, gradual | • Ideal for everyday transactional|
| wealth-building. | users who meet requirements. |
+-----------------------------------+-----------------------------------+
1. Regular Saver Accounts
Popularized heavily in international retail banking markets (such as the UK market offerings from institutions like First Direct or Co-operative Bank), regular savers specifically target disciplined, incremental savers. They reward you with a fixed 7.00% AER/Gross rate over a 12-month term, but because you can only feed the account small amounts monthly (e.g., a maximum of £300 a month), your total interest earned at the end of the year is mathematically bound. Depositing the maximum allowance consistently results in a modest total cash payout rather than a massive windfall, even though the rate printed on the label is high.
2. Reward Checking and Hybrid Accounts
In the United States and other digital banking sectors, credit unions and niche online banks use high-yield reward checking accounts to capture primary customer relationships. Accounts like those from select credit unions may offer up to 7.50% APY, but strictly apply this rate to balances under a low ceiling (such as the first $500).
Evaluating the opportunity cost
Before chasing a 7% headline rate, smart savers calculate the effective yield relative to the effort required.
Consider an account offering 7% interest capped at a $1,000 balance versus a standard high-yield savings account offering 4.5% with no balance cap. If you have $20,000 in liquid emergency savings:
Placing that $20,000 into the 7% capped account means only $1,000 earns 7% ($70/year), while the remaining $19,000 earns close to 0% ($0).
Placing that same $20,000 into a straightforward 4.5% unlimited HYSA yields roughly $900 for the year.
Therefore, ultra-high headline rates are exceptionally lucrative only if your savings profile matches the structural limitations of the product.
Introduction
The quest for a 7% interest rate on a savings account often feels like searching for a financial mirage. In standard macroeconomic environments, benchmark interest rates set by central banks dictate that high-yield savings accounts (HYSAs) hover well below this threshold. Yet, headlines frequently tout institutions offering 7%, 8%, or even double-digit returns.
Dissecting these offers reveals a crucial truth: while banks offering a flat, unrestricted 7% return on unlimited liquid balances are virtually non-existent, a select tier of financial institutions achieves this yield through specialized vehicles like Regular Saver accounts, tiered reward checking structures, or geographic promotional limits. Understanding how to navigate these products is essential for maximizing capital growth without falling prey to restrictive fine print.
The details
Achieving a true 7% return requires looking closely at the mechanics of how banks structure high-yield products. Financial institutions rarely offer high rates out of altruism; they use them as loss leaders to capture primary customer relationships or cross-sell profitable credit products.
+-----------------------------------------------------------------+
MECHANICS OF 7% YIELD PRODUCTS
+-----------------------------------------------------------------+
[Regular Saver] -------------> Strict monthly deposit caps (e.g., $300/mo)
[Reward Checking] -----------> Activity hurdles (debit swipes, direct deposit)
[Geographic/Tiered] ---------> Rate applies only to initial balance tier ($500-$1,000)
+-----------------------------------------------------------------+
Regular Saver Accounts: Prominent institutions (such as First Direct or the Co-operative Bank in the UK market) offer dedicated regular saver accounts yielding 7.00% AER fixed. However, the catch lies in the contribution architecture. Savers cannot deposit a lump sum of capital; instead, they are restricted to monthly contributions capped typically between $250 and $300. Consequently, the effective interest earned applies strictly to a gradually accumulating balance over a 12-month fixed term.
Reward Checking and Credit Unions: Certain credit unions and digital banks provide checking tiers yielding up to 7% to 8% APY. These accounts mandate rigorous behavioral criteria, such as a minimum number of monthly debit card transactions, electronic statement enrollment, and recurring direct deposits. These high rates frequently apply only to low balances (e.g., the first $500 or $1,000), with any excess balance dropping to a nominal nominal rate near zero.
Little-Known aspect: The Internal Rate of Return (IRR) trap
When consumers see a "7% interest rate," they mistakenly assume their total annual balance compounds at 7%. The reality of dollar-weighted return tells a different story, especially for regular saver products.
If you deposit $300 every month into a 7% regular saver account over 12 months, your total deposits reach $3,600. Because your money enters incrementally rather than sitting in the account for the full year, the actual interest earned is closer to half of the headline rate applied to the full aggregate. Understanding the Internal Rate of Return (IRR) ensures savers do not overestimate their projected year-end cash flow.
The short version
Evaluating whether a 7% savings vehicle fits your broader financial portfolio requires balancing administrative friction against total yield. If you possess a large lump sum, such as a $50,000 inheritance or house down payment, placing it into a 7% regular saver or tiered checking account is mathematically inefficient due to strict monthly contribution caps and low balance ceilings. For large sums, a standard high-yield savings account or money market fund offering competitive baseline rates across all liquid balances remains the superior choice.
Conversely, if you are a disciplined saver looking to build an initial emergency fund while automating monthly allocations, maximizing a capped 7% product provides a risk-free return that outperforms almost any conventional asset class.
Final Verdict
| Strategy / Account Type | Headline Rate | Principal Constraint | Best Suited For |
|---|---|---|---|
| Regular Saver Accounts | 7.00% AER | Strict monthly deposit caps ($250–$300/mo) | Habitual savers building capital incrementally |
| Reward Checking Accounts | 7.00% – 8.00% APY | Low balance caps ($500–$1,000 max tier) | Active users meeting automated transaction hurdles |
| Standard High-Yield Savings | Market benchmark | None (unlimited liquidity & balance) | Large lump sums and flexible emergency funds |
A 7% savings account is real, but it is rarely a vehicle for massive wealth accumulation. Treat these products as tactical portfolio enhancements rather than universal solutions for liquid cash management.