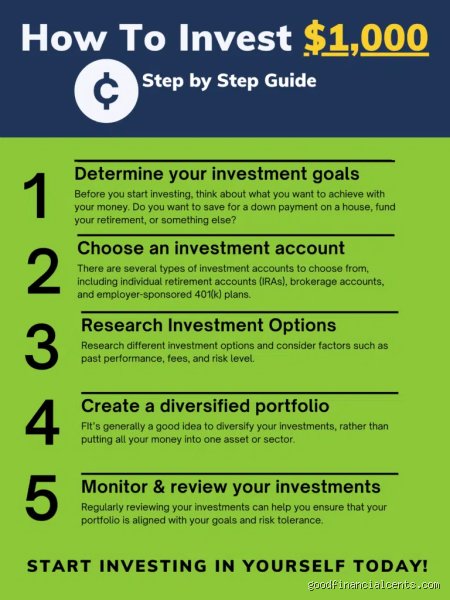
Maximizing your initial capital: Portfolio deployment and growth strategies
When you are ready to deploy your initial $1,000, asset allocation becomes your primary vehicle for building long-term wealth. Rather than concentrating your funds into a single high-risk asset, dividing your capital across diversified financial instruments minimizes vulnerability while maximizing exposure to consistent market growth. A practical approach for a beginning investor involves utilizing exchange-traded funds (ETFs) that track major market indexes. For instance, allocating a portion of your funds toward a broad-market S&P 500 fund anchors your portfolio with historical stability, while layering in a growth-oriented technology sector fund or a dividend-focused fund captures targeted momentum.
To implement this effectively without high transaction costs, look for brokerages offering fractional shares and zero-commission trading. This allows your entire $1,000 to be put to work immediately, ensuring that every dollar contributes to your financial goals. Setting up an automatic dividend reinvestment plan (DRIP) enables your distributions to purchase additional fractional shares automatically, fueling the engine of compound growth over extended time horizons.
The Little-Known aspect of Micro-Rebalancing and tax efficiency
Many novice resources emphasize the initial purchase, but few discuss the nuanced mechanics of maintaining a small portfolio over time. A critical, lesser-known aspect of managing a modest $1,000 portfolio is avoiding the trap of premature portfolio rebalancing. When dealing with smaller sums, manual trades or frequent adjustments can trigger unnecessary administrative friction or minor fees that erode your capital base. Instead, practice behavioral dormancy during your first year, allowing your asset mix to find its natural rhythm.
Understanding the tax efficiency of your chosen vehicle matters immensely. Utilizing tax-advantaged accounts—such as a custodial Roth IRA if eligible, or a standard taxable brokerage account with low-turnover index funds—ensures that capital gains and distributions are not prematurely decimated by short-term taxes. By minimizing portfolio turnover, you retain a higher percentage of your returns, letting the mathematics of compounding work uninterrupted.
Common mistakes to avoid when investing your first ,000
Navigating the financial markets for the first time brings psychological and tactical hurdles. Recognizing common pitfalls helps safeguard your principal and prevents emotional decision-making from derailing your progress.
Chasing quick returns and speculative hype
One of the most dangerous traps for new investors is the temptation of speculative assets promising overnight riches. Meme stocks, speculative crypto tokens, and day-trading schemes often behave more like lottery tickets than sound investments. When you start with a modest sum, preserving your capital and aiming for steady, reliable expansion through dollar-cost averaging yields far better long-term results than gambling on volatile trends.
Neglecting hidden fees and expense ratios
New investors frequently overlook the silent wealth-killers known as expense ratios and account maintenance fees. Even a seemingly small annual management fee of 0.50% or 1.00% can compound negatively over decades, siphoning away hundreds or thousands of dollars of potential earnings. Always audit the underlying costs of any fund you choose, prioritizing low-cost passive index products that keep operational expenses to an absolute minimum.
Over-Checking and emotional reactivity
Logging into your brokerage app multiple times a day to monitor minute-by-minute market fluctuations invites anxiety and impulsive behavior. Short-term volatility is a normal characteristic of healthy economic cycles. Succumbing to panic during a market downturn and selling at a loss locks in your deficits, whereas maintaining a disciplined, long-term outlook historically rewards patience and consistency.