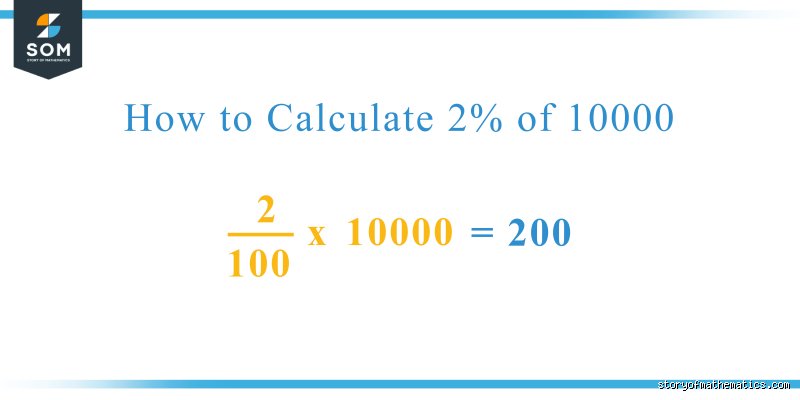
It looks like you forgot to include the topic for the article! What subject would you like me to write about using this HTML structure and style?
Deconstructing the Math: The Formula Behind the Figures
While arriving at the final figure of $200 for two percent of ten thousand dollars is fundamentally straightforward, understanding the underlying mathematical mechanics empowers you to scale these calculations infinitely. At its core, calculating a percentage is a proportional exercise. The word "percent" itself stems from the Latin per centum, meaning "by the hundred." Therefore, any percentage is essentially a fraction with a denominator of 100, or a decimal fraction where the whole is represented as 1.00.
When we look at 2%, we are looking at 2 parts out of 100. Converted into a decimal, this is 0.02. When applied to a total sum—in this case, $10,000—the operation is a simple multiplication of the whole by the decimal rate:
Alternatively, this can be solved through fractional division. Since 2% is equivalent to the fraction 2/100 (which simplifies to 1/50), dividing $10,000 by 50 yields the exact same result:
Mastering these alternate pathways—whether you prefer decimals, fractions, or mental math shortcuts (such as finding 1% by moving the decimal two places to the left, yielding $100, and then doubling it)—ensures you can verify calculations quickly across any professional or personal scenario.
Real-World Applications: Where Does a 2% Allocation Matter?
Knowing how to calculate 2% of $10,000 is only the first step; the true value lies in knowing what that $200 represents across various financial, economic, and professional landscapes.
1. Personal Finance and Savings Buffers
In personal budgeting, a $200 allocation from a $10,000 baseline can represent several critical milestones:
Monthly Savings Contributions: If you maintain a liquid pool of $10,000, channeling 2% ($200) monthly or annually into targeted growth vehicles can compound over time.
Emergency Fund Interest Estimates: If your $10,000 is sitting in a High-Yield Savings Account (HYSA) yielding a 2% annual percentage yield (APY), that exact calculation tells you that your money will generate $200 in passive interest over the course of a year.
2. Investment Portfolios and Risk Management
In professional trading and portfolio management, the 2% rule is a famous risk-management guideline. Many seasoned investors and traders adhere to a rule stating they should never risk more than 2% of their total capital on a single trade or investment position.
If your total portfolio value is $10,000, risking 2% means your maximum allowable loss on any single asset or trade is capped strictly at $200.
This disciplined boundary protects your core capital from catastrophic drawdowns, ensuring that a single bad decision cannot wipe out your entire financial standing.
3. Business Expenses, Commissions, and Fees
In corporate finance and small business operations, percentage-based deductions are ubiquitous:
Payment Processing Fees: Many credit card processors charge around 2% per transaction. On $10,000 in monthly sales revenue, a 2% fee amounts to $200 going toward merchant services.
Sales Commissions: If an independent sales representative earns a 2% commission rate for closing a $10,000 contract, their earned payout for that deal is $200.
Strategic Financial Planning with Percentages
Looking at percentages through this multi-faceted lens shifts our perspective from rote arithmetic to strategic resource allocation. When managing capital, understanding how small percentage increments scale against larger lump sums is what separates reactive spenders from proactive financial planners. Whether you are evaluating a fee schedule, assessing investment risk, or projecting returns, that $200 figure serves as a tangible benchmark for how percentages translate into real-world purchasing power and risk exposure.
Conclusion: Turning Basic Math into Financial Literacy
Calculating 2% of $10,000 is much more than a routine arithmetic exercise—it is a gateway into practical financial literacy. By breaking down the formula (), we uncover a reliable tool that applies directly to savings growth, risk mitigation, business accounting, and everyday consumer decisions.
As you navigate your financial journey, remember that mastery over numbers gives you control over your resources. Every percentage point, whether earned as interest, paid as a fee, or risked in an investment, tells a story about your financial health.
What specific financial scenario or budgeting goal are you currently working on that inspired this calculation?