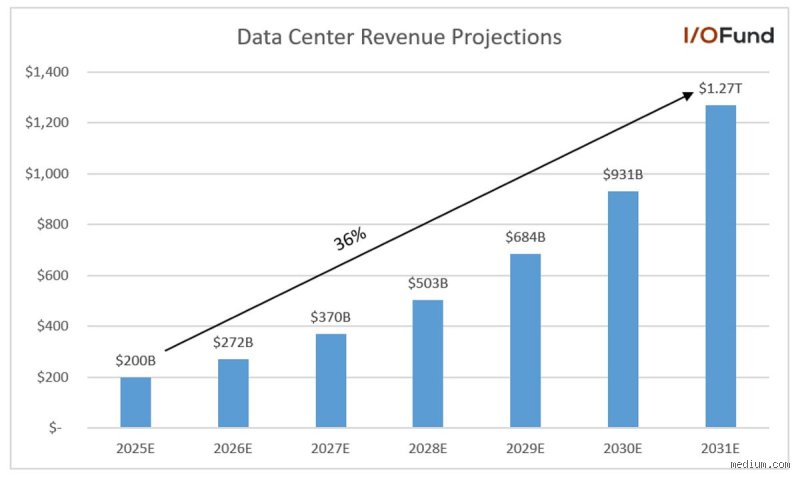
Financial institutions and independent market researchers project a wide spectrum of outcomes for the equity price by 2030. Conservative models point toward a base-case valuation driven by steady enterprise software integration and annualized earnings per share growth sitting comfortably in the mid-teens, translating to share prices in the upper hundreds. Conversely, aggressive bull-case scenarios driven by aggressive enterprise automation and agentic artificial intelligence deployment model multi-trillion-dollar market capitalizations that challenge historical precedents for any single enterprise. Understanding these projections demands a rigorous examination of the underlying drivers rather than reliance on short-term market sentiment.
The primary catalyst sustaining top-line growth is the continuous evolution of data center compute density. Traditional central processing units have reached physical scaling limits dictated by thermal dissipation and the breakdown of classical Dennard scaling. Accelerated computing has permanently replaced legacy architectures as the foundation for enterprise workloads. Corporations across finance, healthcare, logistics, and national defense no longer view artificial intelligence as an experimental line item. Instead, compute infrastructure has become a core balance-sheet asset analogous to real estate or electricity generation facilities.
This structural shift manifests in multi-year capital deployment plans forged between silicon designers and major cloud service providers. Hyperscale operators continue to expand data center footprints with electricity grid constraints acting as the primary bottleneck rather than customer demand. To bypass grid limitations, ecosystem leaders are actively financing nuclear, geothermal, and advanced solar integration directly tied to massive cluster deployments. Consequently, the addressable market for accelerated hardware extends far beyond traditional desktop graphics cards or simple cloud server rentals into sovereign artificial intelligence initiatives where entire nation-states procure domestic supercomputing clusters to safeguard digital sovereignty.
Software monetization represents the second pillar of long-term valuation expansion. Hardware sales alone provide cyclical volatility, but recurring software streams provide valuation stability. By packaging proprietary frameworks, domain-specific libraries, and enterprise management platforms into subscription bundles, margins experience structural tailwinds. Developing alternative software stacks requires immense capital and engineering hours, leaving enterprise developers deeply anchored within the existing ecosystem. This high barrier to entry protects gross margins even as competing hardware vendors attempt to underbid on raw silicon pricing.
Hardware iteration cycles further dictate the velocity of financial expansion. The transition from legacy architectures to advanced multi-die systems demonstrates that engineering cadence remains unmatched in the semiconductor industry. By compressing product release cycles, companies accelerate the depreciation schedules of existing data center fleets owned by major buyers, forcing continuous upgrade cycles. Customers cannot afford to run outdated hardware when competing entities utilize platforms offering exponentially higher tokens per watt. This dynamic transforms capital expenditures from optional discretionary budgets into mandatory operational survival requirements.
Geopolitical realities and supply chain dynamics introduce complex variables into any long-term valuation model. Semiconductor manufacturing remains concentrated within specific geographic corridors, exposing international technology supply chains to regulatory shifts, trade restrictions, and diplomatic friction. Adapting to shifting export controls requires continuous redesigns of product specifications for specific regional markets, altering cost structures and shifting competitive landscapes. Market participants must weigh the friction of international trade against the sheer velocity of technological demand when forecasting enterprise earnings power out to the end of the decade.
Evaluating the ultimate destination of the equity price requires synthesizing projected non-GAAP earnings per share with forward price-to-earnings multiples typical of mature, high-margin technology monopolies. If sustained execution matches executive projections, the enterprise value by 2030 will reflect an economy deeply restructured around automated intelligence. The ensuing sections will dissect the exact financial models, capital expenditure commitments, and architectural milestones required to support these historic valuations.
Navigating the Software Moat: CUDA and enterprise stickiness
Beyond physical hardware architecture, NVIDIA’s valuation trajectory toward the end of the decade relies heavily on the durability of its software ecosystem. The CUDA programming model, established nearly two decades ago, functions as an invisible gravity well for developer talent and machine learning frameworks. Researchers write algorithms directly against its libraries, and enterprise software stacks are optimized specifically for its instruction sets. This deep integration creates formidable switching costs. Even if a rival hardware manufacturer introduces an accelerator with comparable raw floating-point performance, the friction of rewriting proprietary codebases, debugging migration errors, and retraining engineering teams discourages widespread enterprise migration.
Software monetization is also shifting from a complimentary hardware accessory to an independent recurring revenue stream. Enterprise software suites, specialized simulation packages, and cloud-managed AI toolkits are expanding the company’s addressable market beyond simple chip sales. Capturing billions in high-margin software ARR (annual recurring revenue) changes the financial profile of the corporation, cushioning margins even if hardware unit pricing experiences cyclical normalization.
Hyperscaler CapEx cycles and custom silicon pressures
The primary risk factor challenging long-term bullish projections involves the capital expenditure plans of major cloud service providers, commonly known as hyperscalers. Corporations such as Amazon, Microsoft, and Google represent a massive portion of total data center GPU consumption. These companies possess the financial resources and engineering talent to design custom application-specific integrated circuits optimized for their internal workloads.
As proprietary silicon matures, hyperscalers can offload predictable, stable inference workloads onto in-house chips, reserving NVIDIA accelerators exclusively for cutting-edge model training and complex reasoning tasks. This structural shift does not necessarily eliminate demand, but it introduces margin pressure and caps unit growth. If cloud providers successfully lower their dependence on merchant silicon, NVIDIA’s pricing power could face headwinds, forcing a compression of gross margins from historical peaks near seventy-five percent down toward more traditional high-tech benchmarks.
Geopolitical friction and global supply chain realities
Manufacturing resilience remains another critical variable determining## The Software Moat and Ecosystem Lock-In
While hardware processing speed captures immediate headlines, NVIDIA’s true long-term defense mechanism lies deep within its software ecosystem. The CUDA platform, established nearly two decades ago, created an entrenched developer base that extends far beyond simple chip manufacturing. Programmers building artificial intelligence models, complex simulations, and scientific computing frameworks write directly in CUDA libraries. Switching away from this architecture requires rewriting vast codebases, an operational hurdle that deters enterprise customers from migrating to alternative hardware platforms.
This software dominance resembles the early days of personal computing operating systems. Developers gravitate toward the environment with the richest set of pre-built tools, debugging utilities, and optimization packages. NVIDIA systematically reinforced this advantage by acquiring specialized software startups, expanding into healthcare analytics, automotive toolchains, and industrial robotics simulation. By bundling proprietary software frameworks with high-performance computing clusters, the company transformed itself from a discrete component vendor into an indispensable infrastructure provider. Consequently, corporate clients purchase entire systems rather than isolated processing units, securing recurring enterprise software licensing revenue alongside massive hardware transactions.
Supply chain and advanced packaging dependencies
Manufacturing complexity represents a critical variable influencing the long-term outlook. Production relies heavily on advanced semiconductor fabrication facilities, particularly specialized foundry partners capable of producing ultra-dense microchips. Packaging innovations, such as chip-on-wafer-on-substrate technologies, are essential for integrating high-bandwidth memory directly alongside primary processing dies. Any disruption within these specialized manufacturing nodes can create severe supply bottlenecks, temporarily restricting delivery volumes regardless of end-market demand.
Managing these operational risks requires multi-year capacity reservations and close collaboration with foundry suppliers. Diversifying manufacturing footprints across international geographies will likely become an operational necessity to navigate regulatory shifts and geopolitical friction. Maintaining a resilient supply chain ensures that production scaling matches the aggressive delivery timelines demanded by enterprise clientele through the decade.
The competitive threat landscape
Market dominance inevitably attracts aggressive competition. Major technology conglomerates—often referred to as hyperscalers—spend billions of dollars designing proprietary application-specific integrated circuits, commonly known as custom ASICs. These tech giants aim to reduce reliance on merchant silicon, lowering internal data center operational costs while mitigating supply chain dependencies. AMD and Intel similarly pour capital into competing graphics processing units and accelerators, attempting to carve out meaningful market share in enterprise data centers.
Despite these challenges, architectural velocity works in NVIDIA’s favor. The engineering cadence involves rapid generational shifts, moving from one platform architecture to the next within tight timeframes. Competitors struggle to match this relentless product cycle while maintaining software compatibility across older and newer generations. Custom silicon excels at specific, narrow workloads, but enterprise customers running rapidly evolving foundational models require the extreme flexibility that general-purpose accelerated computing provides. Until custom alternatives match both raw throughput and comprehensive software support, NVIDIA maintains a substantial performance lead.
Edge computing, robotics, and autonomous systems
Looking toward the tail end of the decade, enterprise revenue streams will increasingly diversify beyond massive cloud data centers. Edge computing represents a massive frontier. Industrial automation, smart factories, autonomous vehicles, and surgical robotics demand real-time data processing capabilities at the physical edge where internet connectivity latency creates operational bottlenecks.
NVIDIA positions its miniaturized computing modules directly into autonomous machinery and commercial fleets. These systems process sensor fusion data, combining high-resolution cameras, lidar, and radar inputs, instantly executing safety-critical decisions without cloud reliance. As industrial automation accelerates globally over the next several years, physical machinery upgrades will create secondary demand vectors running parallel to enterprise cloud infrastructure spending. This dual exposure, enterprise cloud training on one side and physical edge inference on the other, significantly broadens the addressable market by 2030.
Financial projections and valuation scenarios for 2030
Projecting share price targets and market capitalization numbers through 2030 requires analyzing multiple operating scenarios based on revenue growth rates, gross margin sustainability, and earnings multiples compression.
The bull case scenario
Under an aggressive expansion thesis, global artificial intelligence adoption accelerates across every major industry vertical, finance, pharmaceuticals, manufacturing, and national defense. Cloud service providers continue multi-year capital expenditure cycles, continuously upgrading data centers with next-generation architectures. Simultaneously, sovereign artificial intelligence initiatives emerge worldwide, with national governments purchasing domestic supercomputing clusters to secure technological independence.
If annual revenue compounds at an elevated rate through the rest of the decade, annual enterprise revenue could scale significantly. Assuming net profit margins remain resilient near historical highs due to high-value software integration, earnings per share would expand exponentially. Under a normalized price-to-earnings multiple typical of mature technology monopolies, the company's total market capitalization could push well past prior historical peaks, translating into substantial share price appreciation from current baseline levels.
The bear case scenario
Conversely, a conservative or downside scenario must account for potential cyclical downturns, capital expenditure exhaustion among major hyperscalers, and regulatory headwinds. If cloud infrastructure providers achieve saturation in data center capacity, capital spending growth rates could decelerate sharply. Geopolitical trade restrictions regarding advanced semiconductor exports to key international markets could permanently cap international sales volumes.
If earnings growth normalizes and valuation multiples compress toward broader technology sector averages, stock appreciation would moderate significantly. Margin compression driven by rising manufacturing costs at advanced foundry nodes would further temper bottom-line expansion. Even under this constrained environment, the company would remain a cash-generative enterprise, but equity returns would look considerably more modest compared to the explosive growth phase experienced during the early stages of the generative artificial intelligence boom.
Final market synthesis
Evaluating NVIDIA's trajectory toward 2030 reveals a company anchored by a profound technological moat combining advanced hardware engineering with entrenched software ecosystems. While cyclical spending corrections, rising supply chain complexities, and determined competitors present continuous hurdles, the broader structural shift toward accelerated computing remains firmly underway. Success through the remainder of the decade depends less on short-term market sentiment and more on the sustained execution of platform diversification, bridging massive cloud intelligence with physical edge autonomy.