Why the Insurance industry needed a new language
Historically, insurers around the world used a patchwork of local, domestic accounting rules—often cobbled together under an interim standard known as IFRS 4. Because every country had its own playbook, comparing the financial performance of an insurer in London with one in Tokyo or Toronto was virtually impossible. Some companies recognized profits the exact day an insurance policy was signed, while others tucked away provisions using decades-old historical data that ignored current interest rates or inflation.
Enter IFRS 17 (International Financial Reporting Standard 17: Insurance Contracts). Implemented to bring consistency, transparency, and comparability to the global insurance sector, IFRS 17 represents the most monumental shift in insurance accounting in modern history.
While the standard sounds technical and dry, its core concepts can be broken down logically. This first part of our comprehensive guide explores why IFRS 17 was created, the profound problems it fixes, and the fundamental building blocks that every analyst, stakeholder, and curious observer needs to understand.
1. The core problem with the old way (IFRS 4)
To appreciate what IFRS 17 achieves, we must first understand why the old framework was broken. Under IFRS 4, companies were largely permitted to keep using their legacy, local GAAP (Generally Accepted Accounting Principles). This created several major loopholes and distortions:
Inconsistent Revenue Recognition: In many standard industries, revenue is recognized as goods or services are delivered. Under old insurance rules, however, the entire cash amount collected from a policyholder was often treated immediately as top-line revenue—even though the company’s actual obligation to provide coverage stretched across 10, 20, or 30 years.
Hidden Liabilities: Many insurers measured their long-term liabilities using "locked-in" interest rates from the day the contract was originally written. If interest rates plummeted years later, the balance sheet might still pretend those liabilities were worth far less than what it would actually cost to settle them in the present day.
The "Black Box" of Profitability: Investors had a difficult time telling whether an insurer’s profits came from brilliant underwriting (writing good policies) or simply from favorable shifts in financial markets.
The International Accounting Standards Board (IASB) designed IFRS 17 to tear down these discrepancies. The new standard ensures that all insurance companies globally speak the exact same financial language, measuring obligations at current value and unlocking transparency around where profits actually originate.
2. What actually counts as an Insurance contract?
Before applying the rules, an organization must determine what falls under the scope of IFRS 17. At its heart, an insurance contract is defined as a contract under which one party (the issuer) accepts significant insurance risk from another party (the policyholder) by agreeing to compensate them if a specified uncertain future event adversely affects them.
The key phrase here is significant insurance risk. If a contract transfers very little risk, such as certain basic financial lending agreements, it falls under other standards, like IFRS 9 (Financial Instruments).
IFRS 17 forces companies to look inside bundled contracts. Many modern financial products combine investment components (like a savings plan) with insurance protection (like life coverage). IFRS 17 requires insurers to untangle these elements where possible, ensuring that pure savings deposits are not falsely reported as ordinary insurance revenue.
3. The modern foundation: Current Measurement and Building blocks
The cornerstone of IFRS 17 is its mandate that insurance liabilities must not be frozen in the past. Instead, they must be continuously updated using current, forward-looking estimates.
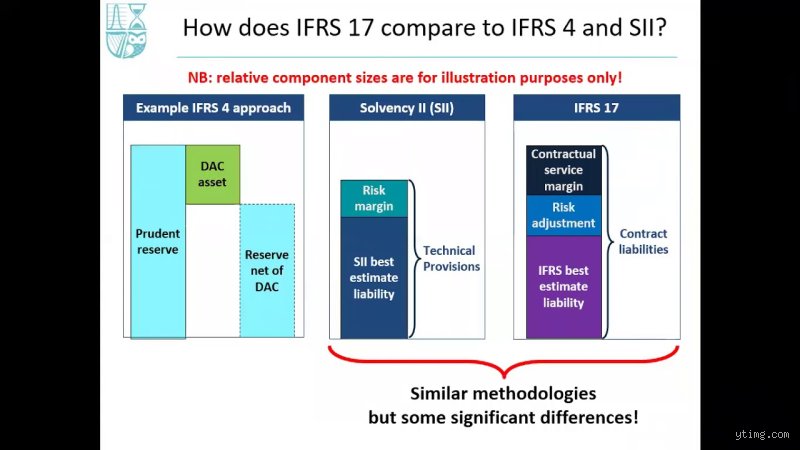
When an insurance contract is evaluated, the general measurement model (often called the Building Block Approach or General Measurement Model) breaks the liability down into distinct components:
Estimates of Future Cash Flows: The insurer projects all future cash inflows (like incoming premiums) and outflows (like future claims, payouts, and maintenance expenses) required to service the contract.
The Time Value of Money (Discounting): Because a dollar tomorrow is worth less than a dollar today, these projected future cash flows are discounted to reflect current interest rates. This ensures the balance sheet reflects market realities rather than outdated historical figures.
Risk Adjustment for Non-Financial Risk: Insurance inherently involves uncertainty, claims might happen sooner, or be larger than expected. IFRS 17 requires an explicit buffer representing the compensation the company demands for bearing that uncertainty.
The Contractual Service Margin (CSM): This is perhaps the most famous and revolutionary concept introduced by the standard.
4. Unlocking the secret of the Contractual Service Margin (CSM)
Under older rules, an insurance company writing a multi-year policy might log an upfront "paper profit" the moment the contract was signed, even though they had barely begun providing the service. If things went wrong years later, massive corrections had to be made.
IFRS 17 eliminates upfront profit recognition through the Contractual Service Margin (CSM).
What is the CSM? Think of the CSM as a pool of unearned future profit.
How does it work at inception? When an insurance contract is first written, if the expected incoming premiums exceed the total expected cost of fulfilling the contract (plus risk adjustments), that net positive difference is labeled as the CSM.
How is it released? Crucially, the insurer cannot pocket this profit immediately. Instead, the CSM is locked away on the balance sheet as a liability. It is only systematically recognized as revenue (and real profit) over time, as the company actually delivers the insurance coverage service block-by-block across the life of the policy.
If a contract is projected to be loss-making right from day one (known as an onerous contract), there is no CSM. Instead, the expected loss is recognized immediately on the income statement. This prevents insurers from sweeping bad news under the rug.
Looking ahead to part 2
By shifting the accounting paradigm from historical tracking to dynamic, current-value measurement, IFRS 17 fundamentally alters how insurance companies manage capital, design products, and report earnings to the public.
In the second part of this guide, we will examine the different measurement models available under the standard (such as the Premium Allocation Approach for short-term policies), how financial statements and income statements are visually transformed, and what these changes mean for everyday investors and the broader financial markets.
Navigating the three Measurement models of IFRS 17
To truly understand how IFRS 17 transforms insurance accounting, one must dive into the mechanics of its measurement models. Under the legacy standard (IFRS 4), insurers used a patchwork of local, domestic accounting practices, making it nearly impossible for investors to compare a life insurance company in London with one in Tokyo or Toronto. IFRS 17 sweeps away that ambiguity by introducing a unified framework built on current estimates of future cash flows.
However, because insurance products vary wildly, ranging from short-term motor policies to multi-decade savings-linked life insurance and complex annuities, a single "one-size-fits-all" approach would fail. Consequently, IFRS 17 establishes three distinct measurement models:
The General Measurement Model (GMM), also known as the Building Block Approach (BBA).
The Premium Allocation Approach (PAA).
The Variable Fee Approach (VFA).
Let's explore how each model operates, how they dictate profit recognition, and why they matter to stakeholders.
Model 1: The General Measurement Model (GMM) – the default engine
The General Measurement Model is the baseline standard from which the other models deviate. It applies primarily to long-term insurance contracts, such as traditional term life insurance, disability insurance, and reinsurance contracts held.
When an insurer writes a group of policies under the GMM, the liability on the balance sheet is constructed from four core building blocks:
Fulfilment Cash Flows (FCF): This component represents the present value of future cash inflows (such as incoming premiums) minus future cash outflows (such as expected claim payouts, benefit distributions, and maintenance expenses). Crucially, these cash flows are discounted to reflect the time value of money and financial risks using current, market-consistent interest rates rather than historical locked-in rates.
Risk Adjustment for Non-Financial Risk: Because future claims are uncertain in both timing and magnitude, insurers must hold a buffer. The risk adjustment is the compensation the insurer requires for bearing the uncertainty about the amount and timing of cash flows arising from non-financial risk.
The Contractual Service Margin (CSM): This is perhaps the most famous and revolutionary innovation in IFRS 17. The CSM represents the unearned profit that the insurer expects to reap as it fulfills the contract over time.
The "no Day-One profit" rule
Under older accounting regimes, some insurers would recognize the entire estimated profit of a long-term policy the moment the contract was signed (known as "day-one gain recognition"). IFRS 17 strictly forbids this.
If a newly formed group of contracts is expected to be profitable, the initial calculation will yield a net positive inflow representing unearned profit. This amount is locked inside the Contractual Service Margin (CSM). Because the CSM sits on the balance sheet as a liability, zero profit is recognized on day one.
Instead, this profit is systematically released into the statement of profit or loss as insurance contract services are delivered over the life of the coverage period. If assumptions change, for instance, if medical inflation spikes or mortality rates turn out worse than expected, the fulfilment cash flows worsen. If these adverse changes outstrip the remaining CSM, the group of contracts becomes onerous (loss-making), and the insurer must immediately recognize a loss in the income statement rather than smoothing it away.
Model 2: The Premium Allocation Approach (PAA) – the Short-Term shortcut
While the GMM is thorough, applying full discounted cash flow projections and tracking individual CSM balances for millions of short-term policies, like a three-month travel insurance policy or a standard one-year auto insurance policy, would create an insurmountable administrative and computational burden.
To solve this, IFRS 17 introduces the Premium Allocation Approach (PAA). The PAA is an optional, simplified measurement model that closely resembles legacy unearned premium income accounting.
Eligibility for PAA
An insurer is permitted to use the PAA only if it meets specific criteria:
The coverage period of each contract in the group is one year or less.
Alternatively, for contracts longer than one year, the insurer must reasonably expect that the resulting measurement would not differ materially from the full General Measurement Model.
How PAA works in practice
Under the PAA, the liability for remaining coverage is initialized simply as the premiums received at inception, minus any insurance acquisition cash flows. As time passes, this liability is recognized as revenue over the coverage period on a straight-line basis (or based on the expected timing of incurred insurance service expenses).
While it looks simpler on the surface, insurers using PAA must still evaluate whether groups of short-term contracts are onerous. If facts and circumstances indicate that a group of PAA contracts will suffer an underwriting loss, the insurer must calculate a loss component and recognize the deficit immediately, ensuring that bad news cannot be hidden behind simplified accounting mechanics.
Model 3: The Variable Fee Approach (VFA) – capturing Unit-Linked and participating products
Many modern insurance and wealth-management products blur the line between insurance protection and investment funds. Examples include unit-linked insurance plans, universal life policies, and "with-profits" contracts where policyholders share in the returns of a specific pool of underlying investment assets.
If an insurer applied the standard GMM to these products, market fluctuations in the underlying investments would cause wild, artificial swings in the insurer's profit and loss statement, because the CSM would remain locked while asset values bounced around daily.
To fix this distortion, IFRS 17 mandates the Variable Fee Approach (VFA) for contracts with direct participation features.
The core mechanics of VFA
The VFA is a modified version of the GMM designed for contracts that are substantially investment-related service contracts. Under the VFA, the contract is viewed as an arrangement where the insurer promises an investment return based on underlying items, acting essentially as an asset manager charging a fee.
The defining characteristic of the VFA is how it treats the Contractual Service Margin (CSM):
Unlike the GMM, where the CSM only absorbs changes in non-financial assumptions, under the VFA, the CSM absorbs changes in the entity’s share of the fair value of the underlying items.
When the investment portfolio performs well, the policyholders' account values rise, and the insurer's variable fee (and thus future profit margin) increases. This positive market movement is captured directly inside the CSM rather than flowing immediately through the income statement.
This mechanism neutralizes artificial financial volatility in the insurer's earnings report, providing a much truer picture of economic reality.
Grouping and portfolio management: The Building blocks of comparison
A common misunderstanding of IFRS 17 is that insurers account for policies strictly on an individual, policy-by-policy basis. In reality, IFRS 17 mandates a strict hierarchical grouping structure:
Portfolios: Insurers first group insurance contracts that are subject to similar risks and managed together as a single pool.
Profitability Buckets: Each portfolio is then split into at least three categories:
Contracts that are onerous (loss-making) at initial recognition.
Contracts that have no significant possibility of becoming onerous (highly profitable).
Remaining contracts in the portfolio.
Annual Cohorts: Crucially, IFRS 17 requires insurers to divide these groups further by annual cohorts, meaning contracts issued more than one year apart cannot be grouped together.
This annual cohort rule prevents insurers from using future profits from newly minted policies to mask losses or cross-subsidize older, underperforming legacy blocks of business. Every vintage year must stand on its own financial merits.
Financial statement presentation and transition impact
The ultimate goal of IFRS 17 is complete transparency across the balance sheet and income statement. Under the hood, the presentation changes are profound:
Separation of Revenue and Finance Income: Insurance revenue no longer equals gross written premiums collected. Instead, insurance revenue represents the consideration earned for the service provided during the period (the release of the CSM, risk adjustment, and expected claims). Financing expenses (the cost of discounting liabilities over time) are separated entirely from insurance service results, giving analysts a clean view of underwriting performance versus investment performance.
Balance Sheet Clarity: Insurance liabilities are no longer buried under opaque local headings. They are presented explicitly as the sum of fulfilment cash flows and the unearned profit margin (CSM).
The Transition Challenge
Because IFRS 17 requires historical retrospective application, meaning insurers had to recalculate their balance sheets and open comparative data as if IFRS 17 had always been in effect, implementation required monumental data engineering and actuarial restructuring.
While the transition required massive upfront investments in technology, data architecture, and cross-functional coordination between finance and actuarial teams, the long-term payoff is monumental. By replacing fragmented local rules with a uniform, globally comparable standard, IFRS 17 ensures that insurance companies speak a universal financial language. Investors can now peer inside insurance balance sheets with absolute confidence, accurately evaluating risk, profitability, and capital strength across international borders.