Understanding the true nature of financial risk
Why capital preservation is not enough
Protection of principal sounds great on paper. Yet, except that inflation quietly devours your cash while you sleep. The trouble is that holding paper currency under your mattress guarantees a 100 percent loss of purchasing power over decades. In 2022, inflation in the US peaked at 9.1 percent, a harsh wake-up call for conservative savers who thought their high-yield savings accounts were bulletproof. The upshot: your money needs to work, even when you aim for zero volatility.
The illusion of zero volatility
That's the reason nominal safety can be deceptive. A certificate of deposit yielding 5.0 percent in 2026 feels secure, but if living costs surge by 6.0 percent, you are actually going backward. I have watched too many retirees park everything in cash equivalents, terrified of market corrections, only to run out of funds by age eighty. It is unclear whether traditional safety nets will even survive the next major economic shift.
Evaluating sovereign debt and government bonds
Mechanics of Treasury bills and notes
Government-backed securities represent the bedrock of modern finance. When you buy a 3-month T-bill yielding roughly 5.2 percent, default risk approaches zero because the issuing government can theoretically print currency to pay its debts. Because of that, institutional investors use these instruments as collateral across global banking systems. But the complication is duration risk; buying a 30-year bond when rates are rising can trap your capital at sub-optimal yields for decades.
Historical context of sovereign defaults
History teaches us that no asset is entirely immune to systemic shocks. Even AAA-rated nations face downgrades, like Standard & Poor's stripping the US of its top tier back in August 2011. Because global markets panicked momentarily, yields actually dropped due to a massive flight to liquidity. But what if the geopolitical landscape shifts dramatically by 2030? There's no consensus on whether sovereign debt remains the ultimate anchor.
Alternative safe havens and hard assets
The paradox of gold in modern portfolios
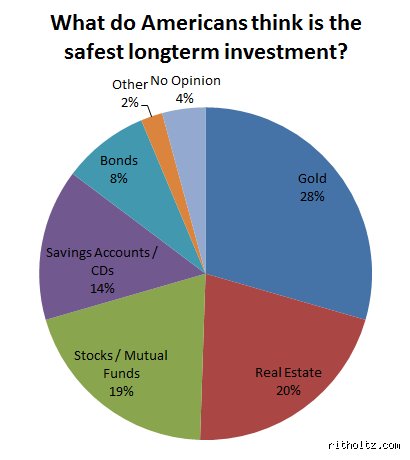
Precious metals have glittered as a store of value since the Lydian stater minted around 600 BC. Gold acts as an insurance policy against currency debasement, surging past 2,400 dollars per ounce during recent global supply chain crunches. But unlike corporate equities, it generates zero cash flow. You are simply betting that someone else will pay a higher price for a shiny yellow rock in the future.
Mistakes people make
Chasing historical returns blindly
People often look backward when allocating capital, assuming that whatever won last year will repeat its performance. Safest investment vehicles do not operate on recent hype. Yet, novice participants pour money into overheated sectors. The problem is that markets cycle continuously. (Past performance guarantees nothing.) That's the reason chasing trends destroys wealth.
Ignoring inflation completely
Many believe stuffing cash under a mattress guarantees absolute security. As a result, purchasing power melts away silently every single day. . A nominal zero-risk asset is actually a guaranteed loser against rising prices. Data shows that holding pure cash over thirty years destroys roughly 50 percent of its real value. You cannot defend your future by ignoring economic realities.
Confusing volatility with permanent loss
Fear makes individuals panic at the slightest market dip. But price swings are just the admission ticket to long-term growth. Because temporary fluctuations frighten amateur traders, they sell at the absolute bottom. The safest investment strategy accounts for this psychological trap by maintaining adequate liquidity. In short, emotional discipline matters more than picking the exact right asset class.
One thing people overlook
The hidden power of duration matching
Professional treasury managers use specialized techniques to neutralize interest rate risk entirely. You can apply this same institutional logic to your personal portfolio. By matching the maturity of fixed-income instruments with your exact timeline of cash needs, price volatility becomes irrelevant. According to Vanguard studies, holding high-grade municipal bonds to their maturity date results in a greater than 99 percent historical return of principal. But most retail investors trade too frequently to capture this stability.
Frequently asked questions
What percentage of a portfolio should go into the safest investment options?
Financial planners generally recommend keeping an emergency fund equal to three to six months of living expenses in ultra-secure vehicles like high-yield savings accounts. Beyond that immediate cushion, the exact allocation depends heavily on your specific age and risk tolerance. For instance, a common rule of thumb suggests subtracting your age from 110 to determine your equity exposure, leaving the remainder in secure bonds. Historical data from Morningstar indicates that portfolios maintaining at least 20 percent in conservative fixed-income assets experience significantly lower maximum drawdowns during recessions. You must balance peace of mind against the silent threat of long-term inflation.
Are Treasury bills safer than high-yield savings accounts?
Short-term United States Treasury bills are backed by the full faith and credit of the federal government, making them mathematically default-free. High-yield savings accounts rely on Federal Deposit Insurance Corporation coverage, which protects deposits up to two hundred fifty thousand dollars per institution. While both options offer exceptional security, T-bills frequently yield a higher return during periods of elevated interest rates. Recent market data shows three-month Treasury yields hovering near 5.2 percent, often outpacing average retail bank offerings. Therefore, direct government debt holds a slight edge for absolute institutional safety.
Does a zero-risk asset actually exist in modern finance?
Pure nominal safety exists through short-term sovereign debt, but absolute purchasing power safety is an illusion. Every single financial instrument carries some hidden vulnerability, whether through taxation, currency devaluation, or macroeconomic shifts. Economic research demonstrates that even the most secure government bonds lose real value when inflation spikes unexpectedly. We must accept that risk can only be managed, never completely eliminated from any financial system. Recognizing this truth transforms how you build a resilient long-term wealth plan.
Where this leaves you
True financial security is never found by hiding from the world inside a vault of stagnant cash. Safest investment choices are simply tools designed to protect your purchasing power while letting compound interest do the heavy lifting over decades. Wealth preservation requires a pragmatic blend of sovereign debt, disciplined budgeting, and a clear understanding of inflation. . Perfection does not exist in markets, but intelligent preparation makes unexpected shocks completely manageable. You hold the ultimate responsibility for balancing your desire for tranquility against the necessity of growth. Stop searching for a magical shield and start building a resilient portfolio.