Introduction: The Anatomy of Modern Super-Wealth
When we contemplate the upper echelons of global financial hierarchy, our minds naturally drift toward the staggering figures flashing across morning financial tickers or the glossy Forbes billionaire lists published annually. Yet, beneath the sensationalized headlines regarding net worth fluctuations lies a more sophisticated and deeply systemic question: Who is the richest stockholder?
To answer this question accurately, one must look past the simple calculation of paper wealth derived from real estate, art collections, or private equity. We must peer directly into the beating heart of global capitalism—public equities. Stock ownership is the primary engine driving modern wealth generation. It transforms founders into corporate titans, passive investors into institutional powerhouses, and astute capital allocators into generational legends.
However, defining the single "richest stockholder" is far from a straightforward task. It requires navigating a complex labyrinth of legal definitions, regulatory disclosures, holding structures, and fluctuating market capitalizations. Is the richest stockholder the visionary founder who retains a massive insider stake in the very company they built from a garage? Is it the institutional fiduciary managing trillions of dollars on behalf of millions of everyday workers? Or is it the stealthy, long-term value investor who quietly accumulated massive equity blocks across dozens of the world’s most dominant multinational corporations?
In this comprehensive, multi-part expert analysis, we will deconstruct the mechanics of equity wealth, examine the undisputed heavyweights of modern stock ownership, explore the regulatory and structural frameworks that govern their holdings, and ultimately reveal the identity and strategies of the individuals and entities sitting atop the global equity pyramid.
Part I: The Methodology of Measuring Equity Wealth
Before crowning any individual or entity as the richest stockholder, we must first establish a rigorous methodological framework. Measuring equity wealth is not merely a matter of multiplying the number of shares owned by the current share price—though that forms the baseline calculation. True analysis requires accounting for several dynamic variables:
Level 1: Direct Insider Ownership vs. Beneficial Ownership. Public companies are legally mandated to report significant insider holdings. In the United States, for instance, Section 16 of the Securities Exchange Act requires officers, directors, and beneficial owners of more than 10% of a registered class of equity securities to report their transactions. However, wealth is frequently obfuscated behind multi-layered corporate structures, family offices, trusts, foundations, and shell companies.
Level 2: Dual-Class Share Structures and Voting Power vs. Economic Interest. Many modern technology and industrial conglomerates utilize dual-class stock architectures. In these setups, founders or insiders hold Class B shares carrying disproportionate voting rights (often 10 votes per share) compared to the Class A shares traded publicly on exchanges. Consequently, an individual’s control over corporate equity does not always mirror their exact economic ownership percentage, though both contribute to their overall financial standing.
Level 3: Liquidity, Encumbrances, and Derivatives. A vast stock portfolio is rarely entirely liquid. Large blocks of shares are frequently subject to lock-up agreements, regulatory trading windows, insider trading blackouts, or pledged as collateral against personal loans and margin lines. Furthermore, sophisticated holders utilize derivatives—such as collars, prepaid variable forward contracts, and options—to hedge risk or monetize positions without triggering immediate taxable events.
Level 4: Volatility and Market Sensitivity. Because public equities fluctuate in real-time based on macroeconomic indicators, interest rate shifts, geopolitical events, and quarterly earnings reports, the title of "richest stockholder" is fluid, shifting by billions of dollars with every single trading session on Wall Street.
By applying these rigorous standards, we can separate ephemeral paper gains from entrenched, structural equity dominance.
Part II: The Founders and Insiders — Monopolizing the Cap Table
Historically, the individuals who command the highest concentrations of single-stock wealth are the visionaries, engineers, and entrepreneurs who founded the world's most valuable publicly traded enterprises. Unlike traditional investors who buy shares on the open market, founders acquire their initial equity positions at the inception stage, watching those stakes compound exponentially as their enterprises scale to global dominance.
To understand the pinnacle of single-stock ownership, we must examine the titans of the technology and retail sectors, where scalable business models allow for unprecedented accumulation of equity value.
The Titans of Big Tech
Over the past two decades, the Information Technology sector has eclipsed traditional industries—such as energy, manufacturing, and finance—in minting the world's largest equity fortunes.
The Amazon Ecosystem: At the forefront of retail and cloud computing, Jeff Bezos has long commanded massive equity ownership. Even following his historic multi-billion-dollar divestments and his high-profile divorce settlement, Bezos remains the single largest individual shareholder of Amazon (AMZN). His fortune is inextricably linked to the performance of Amazon's e-commerce logistics and Amazon Web Services (AWS). Every fractional movement in Amazon's stock price translates to a swing of hundreds of millions of dollars in his personal net worth.
The Tesla and SpaceX Empire: Elon Musk represents a unique paradigm of equity concentration. While Musk’s wealth spans multiple entities—including SpaceX and X (formerly Twitter)—his massive stake in Tesla (TSLA) serves as the primary anchor of his public equity wealth. Tesla’s meteoric rise from a niche electric vehicle startup to a global manufacturing and energy behemoth propelled Musk to the apex of the global wealth rankings. His holdings include both direct common stock and lucrative stock options awarded under historical performance-based compensation packages.
The Microsoft Legacy: While Bill Gates has systematically diversified his wealth over decades through his philanthropic foundation and private investment vehicle (Cascade Investment), his foundational equity holdings in Microsoft (MSFT)—the company he co-founded in 1975—established the modern blueprint for tech-driven stock accumulation. Though he no longer holds a controlling majority, the residual effects of his early equity retention continue to reverberate through global capital markets.
The Meta Platforms Dynasty: Mark Zuckerberg’s wealth is heavily centralized in Meta Platforms (META). Due to Meta's dual-class share structure, Zuckerberg retains firm operational control and economic ownership of a massive block of Class A and Class B shares. His equity position directly mirrors the valuation of the global social media ecosystem encompassing Facebook, Instagram, WhatsApp, and Reality Labs.
The Conglomerate King: Berkshire Hathaway
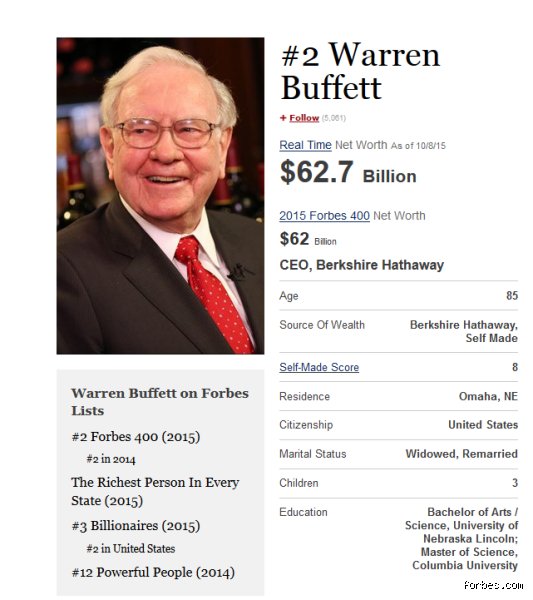
Moving away from Silicon Valley, we encounter a completely different style of stock accumulation embodied by Warren Buffett. As the Chairman and CEO of Berkshire Hathaway (BRK.A / BRK.B), Buffett is arguably the most famous stock picker in human history.
However, Buffett’s status as a colossal stockholder operates on two distinct levels:
Personal Holdings: Buffett owns a massive block of Berkshire Hathaway Class A shares, which he has been systematically distributing to philanthropic causes in recent years. Despite these historic donations, his remaining equity stake represents one of the largest single-stock concentrations held by an individual.
Corporate Portfolio Management: Through Berkshire Hathaway, Buffett manages an equity portfolio worth hundreds of billion dollars, holding significant blocks of blue-chip stocks such as Apple (AAPL), American Express (AXP), Coca-Cola (KO), and Bank of America (BAC). While these shares belong to Berkshire's shareholders rather than Buffett personally in a direct sense, his authority over their deployment makes him the ultimate proxy holder of corporate America's crown jewels.
Part III: The Institutional Giants — The Invisible Overlords
While individual founders capture public imagination, they represent only one side of the equity coin. In the modern era of financial capitalism, the true heavyweights dominating global stock registers are not individual humans, but massive institutional asset managers.
If we define the "richest stockholder" not by individual ego, but by aggregate voting power and total assets under management (AUM), the crown shifts decisively to the "Big Three" index fund managers:
BlackRock, Inc.: Led by Larry Fink, BlackRock manages over $10 trillion in assets. Through its ubiquitous iShares exchange-traded funds (ETFs) and institutional index funds, BlackRock frequently appears as the single largest institutional shareholder in virtually every major publicly traded corporation included in the S&P 500 and Russell indices.
The Vanguard Group: Founded by indexing pioneer Jack Bogle, Vanguard operates on a unique client-owned structure where the fund owners own the company. Vanguard commands trillions of dollars in equity investments, making it a collective powerhouse that holds multi-percent stakes in almost every significant public company globally.
State Street Global Advisors (SSGA): As the asset management division of State Street Corporation, SSGA manages trillions in equity assets and is famously known for originating the SPDR S&P 500 ETF Trust (SPY), the world’s first and most heavily traded exchange-traded fund.
These institutional titans do not own the stock for their own personal enrichment in the traditional sense; rather, they act as fiduciary custodians holding shares on behalf of tens of millions of retail retirement accounts, pension funds, endowments, and sovereign wealth entities. Nonetheless, their collective sway over corporate boardrooms, proxy voting, and capital allocation makes them the most powerful collective stockholders on Earth.
Part IV: Sovereign Wealth Funds — State-Backed Equity Dominance
In addition to individual entrepreneurs and Wall Street asset managers, a profound shift has occurred over the past three decades with the rise of Sovereign Wealth Funds (SWFs). Funded by national surpluses—predominantly generated through commodity exports like crude oil and natural gas, or massive manufacturing trade surpluses—these state-backed entities wield staggering pools of capital to acquire equity stakes in foreign and domestic public companies.
Key state-backed equity holders include:
The Government Pension Fund Global (Norway): Often referred to simply as the Norwegian Oil Fund, this fund is financed by the surplus revenues of the Norwegian petroleum sector. It owns roughly 1.5% of all the world’s listed companies, making it one of the single largest global stock market investors in existence.
The Public Investment Fund (PIF) of Saudi Arabia: A primary vehicle for Saudi Arabia's Vision 2030 economic diversification initiative, the PIF holds massive equity positions in global tech giants, entertainment conglomerates, and industrial leaders, alongside deep controlling stakes in domestic publicly traded champions like Saudi Aramco.
Temasek Holdings and GIC Private Limited (Singapore): These state-owned investment companies manage Singapore’s reserves, holding extensive domestic and international public equity portfolios designed to generate long-term sustainable returns for the island nation.
When analyzing who holds the ultimate economic claim on global corporate profits, these sovereign entities rival—and in some cases surpass—the largest private fortunes on the planet.
Summary of Part I
As we have established in this foundational exploration, the question of who is the richest stockholder cannot be answered with a single name without proper context. We must distinguish between:
Insiders and Founders (such as Jeff Bezos and Elon Musk) who dominate single-company cap tables through concentrated equity ownership.
Value Investors and Allocators (such as Warren Buffett) who leverage decades of strategic asset acquisition.
Institutional Fiduciaries and Sovereign Wealth Funds (such as BlackRock, Vanguard, and Norway's Government Pension Fund Global) that command systemic, multi-trillion-dollar equity footprints across the entire global economy.
In the subsequent sections of this expert analysis, we will dive deeper into quantitative comparisons, regulatory disclosure filings (such as SEC Form 4 and Form 13F), the historic evolution of equity concentration, and the precise net worth calculations that separate the contenders for the ultimate title of the world's richest stockholder.
The Architecture of Equity: Deconstructing Individual vs. Institutional Dominance
When analyzing equity concentration at the apex of global wealth, a fundamental dichotomy emerges: the contrast between individual founder-shareholders and institutional asset managers. While individuals like Elon Musk, Jeff Bezos, and Larry Page dominate public perception—and headline indices—as the wealthiest single stock holders due to outsized stakes in companies they engineered, the structural baseline of global equity markets tells a deeply intertwined story of institutional stewardship.
Understanding who truly holds the levers of the stock market requires looking past individual ticker symbols to examine how individual fortunes scale through concentrated equity, and how institutional blockholders control the broader corporate ecosystem.
Part I: The Titans of Individual Stock Ownership
At the absolute peak of individual net worth, wealth is rarely diversified; instead, it is hyper-concentrated in single-equity positions. The modern billionaire hierarchy is inextricably linked to platform capitalism, where founding a dominant technology or retail infrastructure firm yields unprecedented equity leverage.
The Scale of Founder Stakes: Figures such as Elon Musk (with substantial equity blocks across Tesla and SpaceX), Jeff Bezos (Amazon), and Mark Zuckerberg (Meta) illustrate the immense compounding power of retaining large insider percentages after taking a company public.
Unlike traditional investors who buy shares on the open market, these primary stakeholders hold founding blocks protected by multi-class share structures or massive private valuations. The Voting Power vs. Economic Interest Dynamic: Many modern tech titans protect their long-term corporate vision through dual-class stock systems. By holding Class B shares that carry superior voting rights (often 10 to 1 votes relative to public Class A shares), individuals like Mark Zuckerberg maintain absolute strategic control over corporate governance even if their direct economic percentage of the total outstanding stock shifts over time.
Part II: The Invisible Giants—Institutional Blockholders
While single-name billionaires capture public fascination, the structural backbone of global stock ownership belongs to institutional asset management monoliths. Firms such as Vanguard, BlackRock, and State Street Global Advisors (collectively known as the "Big Three") hold passive and active stakes across virtually every major publicly traded corporation in the S&P 500 and global indices.
+-------------------------------------------------------------------------+
| GLOBAL EQUITY OWNERSHIP ECOSYSTEM |
| |
| [ Founder / Insider Blocks ] ----> Direct Control & Vision |
| [ Institutional Giants ] ----> Index Funds, ETFs, & Market Liquidity |
| [ Retail Shareholders ] ----> Fractional & Direct Public Access |
+-------------------------------------------------------------------------+
The Index Fund Revolution: The rise of passive investing has concentrated unprecedented proxy voting power into the hands of a few asset managers. Because index funds pool capital from millions of retail and institutional participants to buy broad market baskets, entities like BlackRock and Vanguard frequently rank among the top institutional shareholders for nearly every Fortune 500 company.
Stewardship and Governance: Unlike individual founders whose wealth is tied to personal identity and operational leadership, institutional stock holders approach equity through risk management, ESG compliance, and long-term portfolio diversification. Their influence is exercised behind closed doors through corporate governance votes and shareholder resolutions rather than day-to-day management.
Part III: Market Impact, Liquidity, and Wealth Volatility
The concentration of stock ownership—whether held by a single visionary billionaire or massive institutional funds—profoundly shapes market mechanics and asset liquidity.
Insider Lock-Ups and Float Dynamics: When a massive portion of a company's stock is locked up by insiders or founding shareholders, the remaining "free float" available for public trading shrinks. This structural scarcity can amplify price volatility during high-volume market events.
The Liquidation Paradox: For the world's richest stock holders, net worth figures on paper can be deceptive. Because individuals like Musk or Bezos own percentages of companies that dwarf daily trading volumes, liquidating even a fraction of their holdings requires carefully managed secondary offerings or pre-scheduled trading plans (such as SEC Rule 10b5-1 plans) to avoid triggering downward price spirals.
Systemic Concentration Risks: As passive indexing funnels trillions of dollars into a handful of mega-cap technology and consumer discretionary stocks, market breadth narrows. The top institutional holders effectively dictate capital allocation trends across global markets, creating an environment where corporate valuations are increasingly tied to systemic index flows rather than isolated fundamental performance.
Conclusion: The Future of Global Equity Leadership
Ultimately, the question of who holds the most stock reveals a shifting paradigm in modern economics. On one hand, individual entrepreneurs continue to leverage disruptive technologies to build historic personal fortunes anchored in single-company equity. On the other, the quiet, systemic accumulation of shares by institutional giants ensures that collective, pooled capital remains the ultimate arbiter of corporate destiny.
As automated investing, cross-border capital flows, and private-to-public market dynamics continue to evolve, the boundary between individual vision and institutional scale will remain the defining frontier of global wealth distribution.