The danger of financial fiction
Open any financial blog, watch a personal finance video, or flip through a retirement planning brochure, and you will almost certainly encounter a ubiquitous magic number: 10%.
For decades, financial advisors, educators, and fintech apps have anchored consumer expectations to the historical performance of the U.S. stock market—specifically, the S&P 500 index. The prevailing narrative is deceptively simple: put your money into a broad-market index fund, sit back, and watch it compound at roughly 10% per year. By this logic, wealth accumulation is merely a function of time and discipline. If you invest $500 a month for thirty years at a 10% annual return, you will cross the million-dollar threshold with room to spare.
While this math is technically correct on a spreadsheet, relying on a flat 10% expectation in the real world is one of the most dangerous psychological traps an investor can fall into.
The stock market does not move in a straight line. It does not pay out a predictable 10% dividend like a corporate bond coupon on New Year's Eve. Instead, it is a volatile, sentiment-driven engine of economic activity that delivers its long-term average through violent expansions, brutal contractions, and long stretches of stagnation. A "nominal" return of 10% does not mean you get to keep 10% purchasing power after the silent tax of inflation takes its cut.
To build a genuinely resilient financial plan—whether you are investing for early retirement, a child’s education, or long-term wealth preservation, you must look past the headline numbers.
1. The Historical Baseline: Nominal vs. Real returns
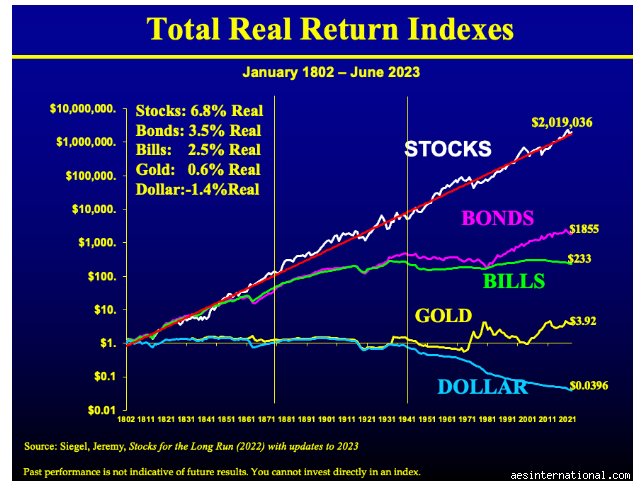
To understand what is realistic, we must first look at what has actually happened over long horizons. Over the past century, the U.S. stock market, proxied by broad indices like the S&P 500 and its historical precursors, has delivered a compound annual growth rate (CAGR) of roughly 9.5% to 10% in nominal terms (before adjusting for inflation, but including reinvested dividends).
However, focusing solely on nominal returns is a critical error. Money is only valuable for what it can buy.
The Inflation Drag
Inflation is the constant, structural erosion of purchasing power driven by money supply expansion, rising wages, and increasing production costs. If the stock market returns 10% in a given year, but inflation runs at 3.5%, your actual increase in buying power is not 10%.
Historically, inflation in developed economies has averaged roughly 3% per year over the long haul, though it has experienced sharper spikes in recent years. When you adjust the historical 10% nominal stock return for inflation using the Fisher equation, the real return drops to approximately 6% to 7%.
To put this into perspective:
Nominal Return (~10%): The raw percentage growth of your portfolio balance on a computer screen.
Real Return (~6.5%): The actual expansion of goods, services, and lifestyle you can command with those dollars in the future.
If your financial plan assumes a flat 10% real return, you are severely overestimating your future purchasing power. Compounding $10,000 at 10% nominal over 30 years yields roughly $174,000. But if inflation averages 3%, that ending balance has the purchasing power of only about $72,000 in today's money. Recognizing this gap is the first step toward realistic wealth planning.
2. Arithmetic mean vs. Geometric mean (the Math of Volatility)
One of the most profound misconceptions among retail investors is the difference between an average return (the arithmetic mean) and a compounded return (the geometric mean). Financial marketers love to quote arithmetic averages because they make past performance look smoother and higher than it actually was for an investor holding through the ups and downs.
Imagine a simple two-year investment cycle:
Year 1: Your portfolio gains +50%. A $10,000 investment becomes $15,000.
Year 2: Your portfolio loses -50%. Your $15,000 drops by half, leaving you with $7,500.
What was your average annual return? If you add +50% and -50% together and divide by two, the arithmetic mean is 0%.
Now look at what actually happened to your money: you started with $10,000 and ended with $7,500. You lost 25% of your capital over two years, resulting in a negative compound annual growth rate (geometric mean).
Volatility Drag
This mathematical reality is known as volatility drag (or variance drain). The greater the swings in your portfolio, the higher the peaks and the deeper the troughs, the wider the gap between the arithmetic average and the actual wealth accumulated by your portfolio.
A stock that drops 50% requires a 100% gain just to get back to even.
A portfolio characterized by massive double-digit swings year after year will systematically underperform a steady, low-volatility asset compounding at a modest, consistent rate, even if both share the same nominal "average."
When institutional forecasters project a 7% or 8% future return for equities, they are accounting for this volatility drag. They know that even if individual years feature +25% booms and -20% busts, the geometric compounding effect will net out to a lower, more realistic figure over long horizons.
3. The myth of the straight line: Decade-by-Decade variance
When people hear that the stock market returns 10% per year, they often mentally model it like a high-yield savings account that pays out a steady 10% every December. Reality is radically different. The stock market is episodic; it delivers its returns in concentrated bursts separated by long periods of flat performance or gut-wrenching drawdowns.
History demonstrates that the stock market rarely delivers an "average" year:
The Lost Decades: There have been extended multi-year periods where the stock market delivered a negative or flat real return. For instance, an investor who bought the S&P 500 at the peak of the dot-com bubble in March 2000 experienced a deeply frustrating decade through 2009, where nominal returns were effectively zero, and real returns were deeply negative after accounting for inflation and dividends.
The Surge Decades: Conversely, the decade following the 2008 global financial crisis (2010–2019) saw a relentless bull market driven by ultra-low interest rates, technological disruption, and massive corporate earnings expansion, pushing annualized returns well above historical norms (closer to 13–14% nominal).
Why this matters for planning
Because returns are clustered, sequence of returns risk becomes the defining variable for anyone approaching or in retirement. If you retire right before a multi-year bear market, withdrawing funds while your portfolio is down can permanently impair your wealth, even if the market eventually recovers. Expecting a smooth 10% linear growth path leaves investors dangerously unprepared for the reality of cyclical market corrections.
4. What actually drives stock returns?
To evaluate whether future stock market returns will mirror the past, we must understand the fundamental machinery that generates stock returns in the first place. Over the long term, a stock's return is driven by three primary pillars:
Dividend Yield: The cash dividends paid directly to shareholders. Historically, dividends accounted for nearly 40–50% of total stock market returns over the 20th century. While dividend yields have compressed in modern growth-heavy markets, they remain a vital baseline component of total return.
Earnings Growth: The growth rate of corporate profits. Companies grow their earnings by expanding revenues, improving operational efficiency, innovating, and capturing market share. Over long periods, stock prices track earnings growth because a share of stock is fundamentally a fractional claim on a corporation's future cash flows.
Valuation Changes (Multiple Expansion/Contraction): How much investors are willing to pay for every dollar of corporate earnings (measured by metrics like the P/E ratio). When sentiment is euphoric, valuations expand, boosting returns temporarily. When sentiment sours or interest rates rise, valuations contract, dragging down returns even if corporate earnings remain relatively stable.
When valuations start from historically high levels, as they frequently do in modern equity markets due to concentrated capital flows into mega-cap technology companies, future expected returns over the subsequent decade tend to be lower. This is because high starting prices naturally borrow expected returns from the future.
Looking ahead to Part 2
As we have established, the idea of a guaranteed, smooth 10% annual return is a financial myth that obscures the realities of inflation, volatility drag, and cyclical valuation shifts. A realistic baseline expectation for broad-market equities moving forward requires factoring in economic growth constraints, interest rate environments, and starting valuations.
In Part 2 of this expert analysis, we will examine forward-looking return models, how macroeconomic factors like interest rates and productivity growth shape future expectations, and how investors can build robust portfolios that succeed even if the stock market delivers below-average returns over the next decade.
Navigating the Volatility: Sequence-of-Returns risk and Real-World wealth accumulation
Understanding historical averages and forward-looking institutional forecasts is only half the battle. For the everyday investor, the true challenge lies in how these returns manifest over a human lifetime. The stock market does not deliver its long-term average in smooth, predictable increments. Instead, it lurches forward in aggressive bull runs punctuated by sharp, anxiety-inducing corrections and bear markets.
This reality introduces sequence-of-returns risk, the danger that the timing of your market entry or exit will drastically alter your financial outcome, even if the long-term arithmetic average matches expectations. For example, encountering a major 30% market downturn right as you transition into retirement can permanently impair a portfolio's longevity, forcing you to sell depressed assets to cover living expenses. Conversely, experiencing a prolonged bull market in your early accumulation years builds a resilient cushion of compounding wealth that can weather subsequent macroeconomic storms.
Tactical strategies for realistic financial planning
When constructing a robust retirement or wealth-building model, financial planners universally advise against plugging a nominal 10% or 11% return straight into your spreadsheets. Doing so introduces a dangerous margin of error that can leave you severely underfunded.
To bridge the gap between academic history and prudent personal finance, consider the following implementation strategies:
Adopt a Conservative Real Return Baseline: Model your long-term plans using an inflation-adjusted (real) return of 5% to 6% for a diversified, equity-heavy portfolio. If your investments ultimately outperform this benchmark, you will enjoy a pleasant surplus rather than a stressful shortfall.
Account for Friction Costs: Remember that gross market returns do not land directly in your brokerage account. Factor in expense ratios of low-cost index funds, advisory fees (if applicable), and, crucially, tax drag. Holding investments in tax-advantaged accounts like IRAs, 401(k)s, or equivalents prevents capital gains and dividend taxes from quietly eroding your compounding velocity.
Embrace Dynamic Asset Allocation: As you approach your financial goals or retirement horizon, systematically rebalance your portfolio to include uncorrelated asset classes, such as high-grade bonds or cash equivalents. While these assets typically yield lower returns than equities, they dampen portfolio volatility and protect you from being forced to liquidate stocks during a localized market crash.
The Ultimate takeaway
A realistic stock market return is not a fixed destination, but a moving target shaped by valuation cycles, economic shifts, and global monetary policy. While the U.S. and global stock markets have historically rewarded patient, disciplined investors with impressive nominal gains of roughly 9% to 10%, a disciplined realist plans for a post-inflation return closer to 6%. By respecting market volatility, minimizing investment friction, and keeping a long-term horizon, you turn the stock market's erratic temperament into a powerful engine for lasting financial security.