What is the topic or text you would like me to write about or rewrite? Let me know the details, and I'll get right on it.
Navigating the Complexities: Measurement Models, Transition Approaches, and Operational Impact
Introduction to Core Measurement Frameworks
To truly understand how IFRS 17 governs modern insurance accounting, one must examine its three core measurement models.
The General Measurement Model (GMM): Built upon the four core blocks (discounted fulfilment cash flows, risk adjustments, and the contractual service margin), GMM dictates the baseline for long-term and non-participating insurance contracts.
It tracks groups of contracts from initial recognition through their entire life cycle, strictly segregating unearned profit from claims experience. The Variable Fee Approach (VFA): Designed specifically for contracts with direct participation features (such as unit-linked or traditional whole-life savings products), VFA recognizes that the insurer's obligation is inextricably linked to underlying items. Under VFA, the Contractual Service Margin (CSM) is adjusted not only for unearned profit delivery but also to reflect the insurer’s share of changes in the fair value of underlying assets.
This mechanism prevents artificial volatility from distorting an insurer's net income statement. The Premium Allocation Approach (PAA): Serving as a simplified, optional alternative, PAA is tailored for short-duration contracts—typically property, casualty, and short-term health insurance. It closely mirrors traditional unearned premium reserve methods, provided that the liability for remaining coverage does not differ materially from the GMM outcome, thereby easing administrative friction for high-volume, low-duration lines of business.
Transition Approaches and Historical Data Challenges
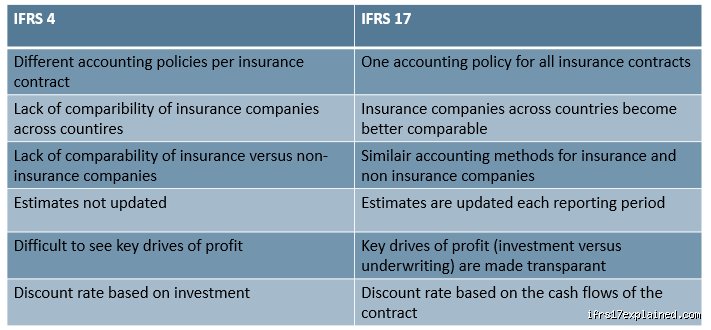
For most insurers, moving from the patchwork rules of IFRS 4 to the rigorous demands of IFRS 17 required looking backward to look forward. Because contracts can span decades, calculating the CSM retrospectively from the inception date of every active policy is a formidable mathematical puzzle.
To solve this, the standard outlines three distinct transition pathways:
The Full Retrospective Approach (FRA): Insurers treat IFRS 17 as though it had always been in effect, reconstructing historic cash flows, discount rates, and risk adjustments from day one.
While providing the highest level of comparative accuracy, FRA is frequently impractical due to data limitations of legacy systems. The Modified Retrospective Approach (MRA): When full data is missing, MRA allows approximations using reasonable and supportable information available to the entity, aiming to achieve the closest possible outcome to FRA without requiring impossible data excavations.
The Fair Value Approach (FVA): Serving as the fallback when neither FRA nor MRA is feasible, FVA determines the CSM at the transition date based on the fair value of the insurance contract liabilities.
This method relies heavily on current market metrics rather than historic cost tracking, significantly cutting down data burdens while resetting baseline profitability metrics.
Operational, Strategic, and Cultural Transformation
The introduction of IFRS 17 is much more than a compliance check or a superficial accounting overhaul; it represents a deep operational transformation for insurance institutions worldwide.
+-----------------------------------------------------------------+
| THE IFRS 17 VALUE CHAIN |
+-----------------------------------+-----------------------------+
 |
 +----------------------------+----------------------------+
 | |
 v v
+------------------------------+ +------------------------------+
| Actuarial Modeling | | Financial Reporting |
| (Cash flows, risk margins, | <------> | (Balance sheets, income |
| discount curves, CSM tracks)| | statements, disclosures) |
+------------------------------+ +------------------------------+
 | |
 +----------------------------+----------------------------+
 |
 v
 +----------------------------------+
 | Strategic Product Redesign |
 | (Margin optimization, pricing |
 | strategies, portfolio mix) |
 +----------------------------------+
1. Integration of Finance and Actuarial Functions
Historically, actuarial pricing teams and financial reporting accountants operated in relative isolation, maintaining distinct models and divergent terminology. IFRS 17 bridges this gap entirely. Because balance sheet figures rely directly on granular actuarial cash-flow projections and discount curves, both departments must align their methodologies, data pipelines, and reporting calendars.
2. Upgrading Data Architecture and Legacy Systems
Legacy IT infrastructure across the insurance sector was rarely built to store or compute data at the granular level required by IFRS 17 (such as tracking contract groups by profitability cohort issued within the same year).
3. Redesigning Product Strategies and Pricing
Because the CSM exposes the true, lifetime profitability of a policy structure right from inception, lines of business that once looked lucrative under older accounting methods may reveal hidden capital strains or volatility under IFRS 17. Consequently, carriers are actively fine-tuning product features, shifting away from excessively risky guarantees, and optimizing product portfolios to secure sustainable, predictable margins.
4. Managing Stakeholder Communications and KPIs
Traditional Key Performance Indicators (KPIs) like top-line gross written premium growth no longer paint the full picture of an insurer's financial health. Instead, markets now focus on metrics like insurance revenue, the evolution of the CSM, and risk adjustments.
Conclusion: A New Baseline for Global Insurance
Ultimately, IFRS 17 has reshaped the financial landscape of the insurance industry.
Key Takeaway: IFRS 17 transforms insurance accounting from a patchwork of opaque, local rules into a synchronized, transparent science. By linking liabilities directly to current market values and isolating unearned profits within the CSM, the standard provides stakeholders with a clear, dependable view of long-term financial health.
How would you like to use this content, or would you like to explore a specific aspect of IFRS 17 like the Contractual Service Margin (CSM) calculations in greater detail?