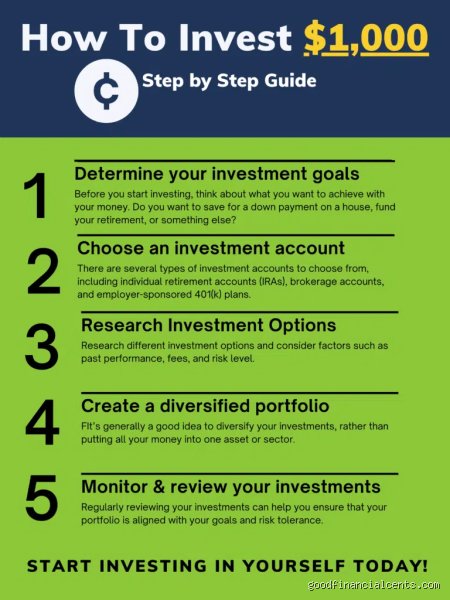
What is the best way to invest 00? A comprehensive foundation for modern wealth building
Before diving headfirst into ticker symbols, charting tools, or high-flying market trends, it is crucial to establish a strategic framework. The best way to invest $1,000 is not a secret shortcut or a speculative gamble on a trending meme asset; rather, it is a disciplined process of foundation-building, cost minimization, and intelligent asset allocation tailored to your personal timeline and risk appetite.
Step 1: Secure your financial baseline
Before a single dollar of your $1,000 touches the stock market, you must run a quick diagnostic on your broader financial health. Pumping money into investments while ignoring high-interest liabilities or vulnerabilities is like trying to fill a bucket that has gaping holes in the bottom.
The High-Interest Debt Trap: If you are carrying credit card debt or personal loans charging 15% to 25% annual interest, paying off that debt is mathematically equivalent to achieving a guaranteed, tax-free return equal to that interest rate. No stock market index consistently beats high-interest consumer debt over the long run. If toxic debt looms over your balance sheet, allocate your $1,000 (or a portion of it) to wiping it out first.
The Micro Emergency Buffer: Markets are volatile, and life is unpredictable. If an unexpected car repair or medical bill would force you to liquidate your investments at an inopportune time—or worse, force you back into high-interest debt—you need a safety cushion. While a full emergency fund covers three to six months of living expenses, even setting aside a couple of hundred dollars of your thousand-dollar pool into a high-yield savings account as an untouchable buffer can protect your long-term strategy.
Once your baseline is secure and your capital is genuinely free to work for you, you can direct your focus toward active market growth.
Step 2: Choose the right investment vehicle
To buy investments, you need an account. Fortunately, modern financial technology has completely democratized retail investing, removing the steep minimum deposit requirements and hefty broker commissions of the past. For a $1,000 starting budget, you generally have two primary pathways:
Self-Directed Online Brokerage Accounts: Platforms like Fidelity, Vanguard, Charles Schwab, or modern app-based brokers allow you to open an account with zero minimums and execute trades with zero commissions. This path gives you total control to pick your own funds, stocks, or bonds.
Robo-Advisors: Services like Betterment or Wealthfront use automated algorithms to build and manage a diversified portfolio for you based on your answers to a brief risk-tolerance questionnaire. They typically charge a very small management fee (around 0.25% of assets annually) in exchange for hands-free rebalancing and portfolio optimization.
For those eager to learn the mechanics of the market, a self-directed brokerage account paired with low-cost exchange-traded funds (ETFs) offers an exceptional educational journey paired with maximum cost-efficiency.
Step 3: Master the power of diversification and low costs
When investing a modest sum like $1,000, rookie investors often make the mistake of spreading their money too thin across ten different individual stocks, or conversely, concentrating the entire amount into a single speculative company hoping it will double overnight. Both approaches are dangerous. Spreading $5 across 200 different stocks racks up tracking friction, while putting all $1,000 into one company exposes you to total loss if that specific business falters.
The solution is instant diversification through index funds or broad-market ETFs. An ETF tracking an index like the S&P 500 pools your money alongside millions of other investors, automatically buying fractional shares of hundreds of top-tier corporations (such as technology innovators, healthcare giants, and consumer staples) in a single transaction.
You must guard your returns against invisible enemies: fees and expense ratios. A mutual fund or managed product that charges a 1% or 2% annual management fee might sound harmless, but over a multi-decade investing horizon, high fees can devour tens of thousands of dollars in compounding potential. Sticking to ultra-low-cost passive index funds, where expense ratios often hover below 0.05%, ensures that nearly every penny of growth stays in your portfolio.
...By prioritizing low-cost, broad-market index exposure over speculative stock picks, you protect yourself against the emotional traps that derail most new investors. But choosing the right vehicle is only half the battle; the framework you wrap your $1,000 in dictates how much of those returns you actually get to keep.
Optimizing account structures and tax efficiency
Once you have selected your asset allocation, whether through a diversified ETF like the Vanguard S&P 500 ETF (VOO) or a balanced multi-asset fund, the next critical decision is where you hold that money.
Utilize Tax-Advantaged Accounts: If you are eligible, deploying your $1,000 into a Roth IRA can dramatically alter your long-term outcome. Because contributions are made with after-tax dollars, every penny of growth compounds tax-free, and qualified withdrawals in retirement cost you nothing in taxes.
Leverage Workplace Retirement Plans: If your employer offers a 401(k) match, prioritize capturing that match before directing discretionary capital elsewhere. An employer match represents an immediate, risk-free 100% return on your contribution up to the matching limit, a return no stock market index can rival.
Taxable Brokerage Accounts: If your retirement accounts are already optimized or you need access to the funds before retirement age, a standard taxable brokerage account with a zero-commission, low-fee provider is the right choice. Stick to buy-and-hold index strategies here as well to minimize taxable capital gains events.
Common pitfalls to avoid with your first ,000
When starting out with a four-figure sum, certain psychological and tactical errors frequently trap beginners. Avoiding these pitfalls will save you both capital and frustration:
Chasing Short-Term Trends: Buying a volatile asset simply because it surged last week introduces unnecessary risk. True wealth building is quiet, systematic, and boring.
Over-Diversifying Too Early: Spreading $1,000 across twenty different individual stocks or narrow thematic ETFs generates excessive transaction overhead and dilutes your returns. One or two broad-market funds achieve cleaner diversification.
Failing to Automate: The greatest advantage a retail investor has is discipline. Setting up automatic recurring investments, even small weekly or monthly additions beyond your initial $1,000, removes emotion from the process.
Tracking your Long-Term growth trajectory
To visualize how your initial $1,000 can compound over time when combined with consistent monthly contributions and a moderate long-term growth rate, review the simulation model below.
Was this visual helpful?
Final Thoughts
Investing your first $1,000 is less about uncovering a secret market anomaly and more about establishing lifelong financial habits. By clearing high-interest debt, securing your emergency foundation, selecting low-cost broad-market index vehicles, and utilizing tax-advantaged structures, you build a robust engine for long-term wealth. Stay consistent, keep fees minimal, and let the mathematics of compounding work in your favor.