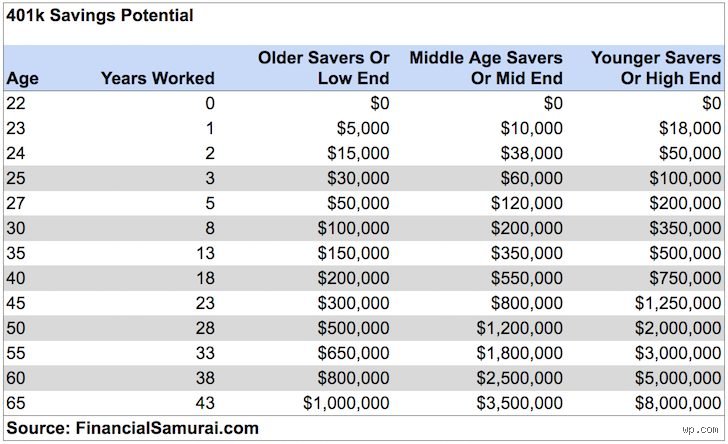
To answer this accurately, we must look past generalized financial myths and analyze hard economic data from authoritative national datasets, including the Federal Reserve’s Survey of Consumer Finances (SCF) and proprietary recordkeeping metrics from major financial institutions like Fidelity and Vanguard. What the data reveals is both reassuring for some and a stark wake-up call for many: a massive chasm separates the "average" from the "median," and standard benchmarks often demand far more than what the typical American household has managed to sock away.
1. The numbers: Averages vs. Medians in your 60s
When evaluating retirement account balances—which typically encompass 401(k)s, 403(b)s, traditional IRAs, and Roth IRAs—financial reports frequently throw around two distinct statistical metrics: the mean (average) and the median. Understanding the difference is vital because a handful of multi-millionaire accounts can heavily skew an average upward, masking what a truly typical 60-year-old possesses.
The Average Balance: According to comprehensive Federal Reserve and institutional data tracking Americans aged 55 to 64, the average household retirement account balance sits between $440,000 and $670,000, while broader wealth-tracking dashboards that aggregate self-selected investors (such as Empower) place average totals for those in their 60s closer to $570,000 to $1.2 million.
The Median Balance: Providing a much clearer reflection of the middle-class reality, the median retirement savings for households aged 55 to 64 sits significantly lower, hovering between $133,000 and $239,000. This means half of all American households in this pre-retirement bracket have managed to save more than that figure, while the other half have saved less, or nothing at all.
Breakdown of Savings by Source and metric
| Data Source / Focus Area | Average Balance (Ages 55–64) | Median Balance (Ages 55–64) | Key Context |
|---|---|---|---|
| Federal Reserve (SCF) | ~$537,560 | ~$185,000 | Encompasses total retirement accounts (IRAs + DC plans) across all U.S. households. |
| Fidelity Investments | ~$257,400 (401k only, ages 60–64) | Not listed explicitly | Active corporate defined contribution plan participants. |
| Empower Dashboard | ~$581,696 (401k only, ages 60s) | ~$189,745 (401k only, ages 60s) | Self-selected digital dashboard users tracking active and former accounts. |
As these figures illustrate, while having $200,000 saved by age 60 places a household right around the national median for retirement accounts, it is far short of the conventional rule-of-thumb benchmarks suggested by fiduciary advisors.
2. Total net worth vs. Pure retirement accounts
Looking exclusively at 401(k) or IRA statements provides an incomplete picture of a 60-year-old's financial readiness. Most Americans do not store 100% of their lifetime wealth in liquid tax-advantaged vehicles. Total net worth at age 60 typically incorporates several major pillars:
Home Equity: For the 55-to-64 demographic, the average home equity stands at roughly $504,000, with a median of about $350,000. While home equity cannot easily buy groceries without downsizing, a paid-off mortgage drastically reduces monthly living expenses in retirement.
Other Financial Assets: Taxable brokerage accounts, cash savings, certificates of deposit (CDs), and savings bonds add an average of $150,000 (median around $67,700) to household balance sheets.
Defined Benefit Pensions: Though less common in the private sector than they were decades ago, public sector employees, union workers, and older corporate veterans often possess traditional pensions that provide guaranteed monthly income, acting as an invisible asset that lowers the necessary size of a nest egg.
When combining retirement accounts, taxable investments, and primary real estate equity, the total net worth for the average American household aged 55 to 64 climbs to a mean of $1.56 million, though the median net worth is substantially lower at roughly $364,000.
3. How age 60 Savings compare to professional benchmarks
Traditional financial planning guidelines suggest that by age 60, a worker should aim to have accumulated between 6x and 11x their current annual salary. For someone earning a median salary of $75,000 a year, this benchmark implies a target retirement savings balance between $450,000 and $825,000 strictly dedicated to post-work life.
Comparing these ideal multipliers against the national median of roughly $185,000 to $239,000 reveals a noticeable coverage gap. Why does this gap exist?
Stagnant Early-Career Savings: Compounding interest requires time. Many workers fail to maximize contributions in their 20s and 30s due to student loans, buying a first home, and raising children.
Healthcare and Life Interruptions: Job losses, corporate downsizing, unexpected medical bills, or caring for aging parents frequently force early withdrawals or temporary cessations of retirement contributions.
The Shift to Defined Contribution Plans: The historic transition from secure company pensions to employee-managed 401(k)s placed the entire burden of market timing, asset allocation, and longevity risk squarely on the individual worker.
Fortunately, turning 60 does not mean the window of opportunity is closed. In fact, tax laws are specifically designed to accelerate savings during this critical decade through elevated contribution thresholds.
As you approach the milestone decade of your sixties, the question of whether your retirement account balances are "normal", or more importantly, sufficient, takes center stage. While the first half of an expert discussion on this topic typically sets up the demographic definitions, national averages, and the profound split between mean and median figures, the critical work lies in the continuation and end of that narrative: analyzing what those numbers actually mean for your lifestyle, how to interpret the psychological weight of the data, and what actionable steps can be taken if you find yourself trailing or leading the pack.
Beyond the numbers: The reality of the Median vs. Average
When evaluating how much the average 60-year-old retires with, aggregate financial data often paints a misleading picture. According to the Federal Reserve’s Survey of Consumer Finances, families headed by individuals aged 55 to 64 hold an average retirement account balance (including 401(k)s, 403(b)s, and IRAs) of roughly $670,250. At first glance, this figure looks reassuring, perhaps even generous.
However, averages are heavily distorted by high-net-worth outliers. The median retirement savings for this same age cohort, the true midpoint where half have more and half have less, stands much closer to $239,000. Platform-specific institutional metrics, such as those from Vanguard and Fidelity, place individual defined-contribution plan averages for late career workers anywhere from $250,000 to $270,000, with individual medians hovering between $95,000 and $100,000.
What does this profound gap tell us? It reveals that a vast majority of Americans reaching age 60 are entering their final decade of labor with substantially less saved than traditional wealth-accumulation formulas prescribe.
+-------------------------------------------------------------+
| AGE 55–64 RETIREMENT SAVINGS GAP |
+-------------------------------------------------------------+
| |
| Mean (Average) Balance: ~$670,250 |
| [==================================================] |
| |
| Median Balance (Midpoint): ~$239,000 |
| [================== ] |
| |
+-------------------------------------------------------------+
Evaluating your position against Income-Based benchmarks
Comparing your bank statement to a national average is rarely helpful because savings needs are inextricably tied to pre-retirement income. Financial planners typically suggest that by age 60, you should have accumulated between 6 to 10.5 times your current annual salary, depending on your household structure and lifestyle expectations.
If your household income is $80,000 per year, this benchmark dictates a target portfolio of roughly $480,000 to $840,000.
Meeting this target requires evaluating more than just tax-advantaged accounts. A comprehensive picture of a 60-year-old's readiness must factor in:
Home Equity: For many Americans, the primary repository of wealth outside of retirement accounts is real estate. The median home equity for households aged 55–64 exceeds $350,000, though tapping into it requires downsizing, reverse mortgages, or relocation strategies.
Defined-Benefit Pensions: While increasingly rare in the private sector, public sector employees, union workers, and educators often rely on steady pension streams that drastically lower the required size of their liquid nest eggs.
Social Security Optimization: Delaying Social Security benefits past age 62 up to age 70 can dramatically increase guaranteed monthly inflation-adjusted income, serving as a powerful offset to smaller investment balances.
The "comeback decade": Maximizing your sixties
Finding yourself behind the recommended benchmarks at age 60 is a common stressor, but your sixties represent a uniquely powerful window for acceleration. Federal tax policy explicitly recognizes this crunch time by offering enhanced savings vehicles:
Aggressive Catch-Up Contributions: Workers aged 50 and older are permitted to make standard catch-up contributions to employer plans and IRAs. Provisions for savers aged 60 through 63 introduce even higher super-catch-up limits, allowing individuals to funnel tens of thousands of dollars annually into tax-sheltered accounts.
Peak Earning Years: For many professionals, mortgage payments are shrinking or finished, children have completed their education, and career earnings have reached their historical peak. This alignment allows for a savings rate that was mathematically impossible during your thirties or forties.
Sequence of Returns Risk Mitigation: As you transition from accumulation to preservation, shifting asset allocations away from hyper-volatile growth stocks toward a balanced, income-generating portfolio protects your principal from a sudden market downturn right before or during early retirement.
Crafting your personal path forward
The question "How much money does the average 60-year-old retire with?" matters far less than your personal alignment between anticipated expenses and guaranteed income streams. Whether your portfolio sits at the median of $239,000, surpasses the national average, or requires an intentional course correction, retirement is not a single rigid cliff, it is a managed transition.
By accurately auditing your expected post-retirement lifestyle, maximizing catch-up contributions, and strategically timing your exit from the workforce, you can turn your final pre-retirement decade into your most financially potent era.