In practice, accounting reports are divided into two broad functional categories: financial accounting reports and managerial accounting reports. Financial reports are standardized, retrospective, and outward-facing, governed by strict frameworks such as Generally Accepted Accounting Principles (GAAP) or International Financial Reporting Standards (IFRS). Managerial reports, conversely, are customized, forward-looking, and inward-facing, designed to help leadership allocate resources, price products, and control operational costs.
The Core Financial statements
At the foundation of every business’s reporting architecture lies a trio of primary financial statements. Together, they provide a holistic view of an enterprise's economic reality, as each statement addresses a distinct financial question while remaining mathematically interlocked with the others.
1. The Income Statement (Profit and Loss Statement)
The Income Statement measures a company’s financial performance over a defined accounting period, such as a month, quarter, or fiscal year. Often referred to as the Profit and Loss (P&L) statement, it answers the fundamental question: Did the business generate a profit or incur a loss during this timeframe?
The report operates on the accrual basis of accounting for most medium-to-large enterprises, meaning revenues are recognized when earned and expenses when incurred, regardless of when cash actually changes hands. Structurally, it follows a top-down waterfall format:
Revenue (Top Line): The gross inflow of economic benefits arising from ordinary operating activities, such as product sales or service fees.
Cost of Goods Sold (COGS): The direct costs attributable to the production of the goods sold or the direct labor required to deliver a service. Subtracting COGS from revenue yields Gross Profit, a critical indicator of core production efficiency and pricing power.
Operating Expenses (OpEx): Indirect costs required to run the business that are not tied directly to production. These are typically segmented into Selling, General, and Administrative (SG&A) expenses, research and development (R&D), and depreciation and amortization. Subtracting OpEx from gross profit reveals Operating Income (often closely aligned with Earnings Before Interest and Taxes, or EBIT).
Non-Operating Items and Taxes: Financial activities peripheral to core operations, such as interest income, interest expense on debt, and one-time gains or losses from asset sales, are accounted for next, followed by income tax provisions.
Net Income (Bottom Line): The residual profit remaining after all expenses and taxes have been deducted from total revenues.
2. The Balance Sheet (Statement of Financial position)
While the Income Statement captures performance over a period of time, the Balance Sheet acts as a financial photograph taken at a single, specific moment, such as December 31 at midnight. It answers the question: What does the company own, what does it owe, and what is the residual value belonging to its owners?
The entire report is governed by the fundamental accounting equation:
Assets=Liabilities+Shareholders’ Equity ext{Assets} = ext{Liabilities} + ext{Shareholders' Equity}Assets=Liabilities+Shareholders’ Equity
To provide clarity on liquidity and solvency, items on the Balance Sheet are rigorously classified by time horizon:
Assets: Economic resources controlled by the entity expected to yield future benefits. Current assets (cash, marketable securities, accounts receivable, inventory) are expected to be converted to cash or consumed within one year. Non-current assets (property, plant, and equipment; intangible assets like patents and goodwill; long-term investments) provide utility over multiple years.
Liabilities: Present obligations arising from past events that will require an outflow of resources. Current liabilities (accounts payable, short-term debt, accrued payroll, unearned revenue) are due within twelve months. Long-term liabilities (corporate bonds, multi-year bank loans, lease obligations, deferred tax liabilities) extend beyond a single operating cycle.
Shareholders' Equity: The residual interest in the assets of the entity after deducting all liabilities. This section includes contributed capital (common and preferred stock issued to investors) and retained earnings (the cumulative net income kept within the business rather than distributed as dividends).
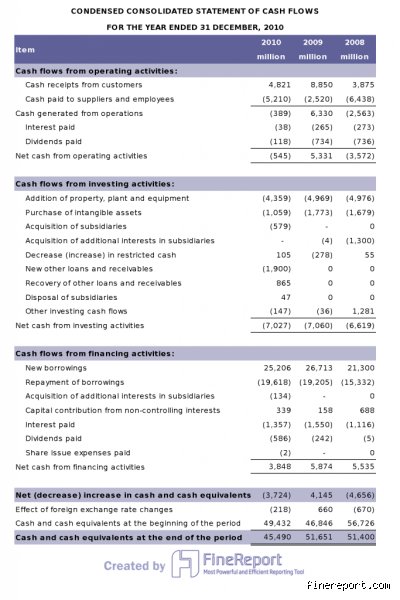
3. The Cash Flow Statement (Statement of Cash Flows)
Profitability on an Income Statement does not guarantee liquidity. A rapidly growing company can report high net income while simultaneously running out of cash due to slow-paying customers or heavy inventory purchases. The Cash Flow Statement bridges this gap by stripping away non-cash accounting conventions (such as depreciation and credit sales) to show the exact movement of cash into and out of the business during a specific period.
The report categorizes cash movements into three distinct operational pillars:
Cash Flows from Operating Activities (CFO): Cash generated or consumed by core business operations. Under the widely used indirect method, this section begins with Net Income and adjusts for non-cash expenses and changes in working capital (increases or decreases in receivables, inventory, and payables).
Cash Flows from Investing Activities (CFI): Cash spent on or received from long-term capital assets and investments. Purchasing new manufacturing equipment or acquiring a subsidiary registers as a cash outflow, whereas selling off obsolete machinery or maturing securities appears as an inflow.
Cash Flows from Financing Activities (CFF): Cash transactions between the company and its owners or creditors. Issuing new equity, borrowing funds, repaying loan principal, repurchasing company shares, and paying cash dividends are all recorded here.
The sum of these three sections equals the net change in cash for the period, which reconciles the beginning cash balance to the ending cash balance reported on the Balance Sheet.
The Statement of Shareholders' Equity
Often included alongside the primary trio as the fourth pillar of external financial reporting, the Statement of Shareholders' Equity (or Statement of Changes in Equity) details the movements in owners' equity over an accounting period. While the Balance Sheet shows the ending equity balances, this report explains why those numbers changed.
It tracks line-by-line reconciliations for each component of equity, including:
Issuance of New Shares: Capital raised through public offerings or employee stock option exercises.
Net Income or Loss: The transfer of bottom-line results from the Income Statement into retained earnings.
Dividends Declared: Distributions of profit to shareholders, which directly reduce retained earnings.
Share Repurchases (Treasury Stock): The cost of buying back the company's own shares from the open market.
Other Comprehensive Income (OCI): Unrealized gains and losses that bypass the Income Statement under accounting rules, such as foreign currency translation adjustments or unrealized fluctuations in certain investment portfolios.
Core Financial statements at a glance
To summarize how these foundational reports complement one another in practice, consider their distinct structural parameters:
| Report Name | Time Horizon | Primary Accounting Basis | Core Question Answered | Primary External Audience |
|---|---|---|---|---|
| Income Statement | Period of time (Month, Quarter, Year) | Accrual Basis | Is the business operationally profitable? | Investors, Analysts, Tax Authorities |
| Balance Sheet | Point in time (Specific date) | Accrual Basis | What is the company's net worth and liquidity position? | Creditors, Lenders, Investors |
| Cash Flow Statement | Period of time (Month, Quarter, Year) | Cash Basis (reconciled from Accrual) | How is the business generating and spending actual cash? | Lenders, Institutional Investors, Auditors |
| Statement of Equity | Period of time (Quarter, Year) | Accrual Basis | How did ownership stakes and retained profits change? | Shareholders, Regulatory Bodies |
Specialized Operational & working capital Reports
Beyond high-level financial statements intended for external stakeholders, accounting teams generate granular, operational reports on a weekly or monthly basis to manage day-to-day liquidity and working capital. These reports expose the underlying mechanics driving the numbers on the Balance Sheet and Income Statement.
4. Accounts Receivable (A/R) Aging Report
When a business sells goods or services on credit, those unpaid invoices sit on the Balance Sheet as Accounts Receivable. However, a single aggregate receivable figure hides critical credit risk. An A/R Aging Report categorizes all unpaid customer invoices by the length of time they have been outstanding, typically grouped into standardized time buckets:
Current (0–30 days)
31–60 days past due
61–90 days past due
Over 90 days past due
This report serves multiple vital functions. First, it directs the collections team toward delinquent accounts before they become uncollectible. Second, it reveals whether specific customers are experiencing financial distress, allowing management to tighten credit terms proactively. Third, accountants use the aging buckets to estimate the Allowance for Doubtful Accounts, a contra-asset reserve required under GAAP and IFRS to ensure receivables are not overstated on the Balance Sheet.
5. Accounts Payable (A/P) Aging Report
Mirroring the A/R Aging Report on the liability side of the ledger, the Accounts Payable Aging Report lists every unpaid bill the company owes to its suppliers, vendors, and service providers, organized by due date and days past due.
Effective use of the A/P Aging Report is central to cash management. By reviewing upcoming obligations, finance teams can schedule payment runs to preserve cash for as long as contractually permissible without incurring late fees or damaging supplier relationships. Conversely, the report highlights opportunities to capture early payment discounts (such as "2/10, Net 30" terms, where paying within 10 days yields a 2% discount on the invoice), which often represent an exceptionally high annualized return on deployed cash.
Managerial and Operational Accounting Reports
While financial statements like the balance sheet, income statement, and cash flow statement satisfy external stakeholders, banks, and tax authorities, they rarely provide the granular, forward-looking insights required to run a business day to day. Managerial accounting reports bridge this gap. Prepared exclusively for internal leadership, department heads, and operational managers, these documents dissect performance by product line, geography, cost center, and operational efficiency.
Budget vs. Actual Variance Report
A budget vs. actual variance report compares projected financial performance against real-world outcomes over a specific period, typically monthly or quarterly. Rather than simply displaying raw totals, this report isolates the precise dollar and percentage differences, known as variances, between what leadership planned to spend or earn and what actually occurred.
Variances are categorized as either favorable (higher revenue or lower expenses than budgeted) or unfavorable (lower revenue or higher expenses than budgeted). Crucially, an unfavorable variance is not automatically a sign of poor management; for example, a sudden spike in raw material costs might directly correlate with an unexpected surge in customer orders. By pairing quantitative variances with narrative explanations from department managers, executives can distinguish between operational inefficiencies that require immediate intervention and strategic investments that are driving growth.
Accounts Receivable (AR) Aging Report
Cash flow can stall even in highly profitable companies if customers fail to pay their invoices on time. The accounts receivable aging report categorizes unpaid customer invoices by the length of time they have been outstanding, typically grouped into standardized time buckets:
Current (0–30 days): Invoices within standard payment terms.
31–60 days past due: Early-stage delinquencies requiring automated reminders or account manager outreach.
61–90 days past due: High-risk receivables that may indicate customer liquidity issues or billing disputes.
90+ days past due: Severely delinquent accounts that often require formal collections intervention or write-offs as bad debt expense.
Beyond guiding collections teams on where to focus their efforts, the AR aging report informs credit policy decisions. If a single client repeatedly drifts into the 60-day bucket, finance teams can tighten their credit limits or require upfront deposits before fulfilling future orders.
Accounts Payable (AP) Aging Report
Mirroring the AR aging report, the accounts payable aging report tracks what the business owes to its suppliers, vendors, and contractors, sorted by invoice due dates. Effective use of an AP aging report allows finance leaders to optimize working capital without damaging vendor relationships.
By analyzing upcoming obligations across 30-, 60-, and 90-day windows, controllers can time outgoing payments strategically, taking advantage of early-payment discounts (such as "2/10, net 30," which offers a 2% discount if paid within 10 days) when cash reserves are strong, or holding cash until the exact due date during tighter liquidity cycles. It also prevents accidental late fees and highlights potential duplicate invoices before funds leave the company's bank accounts.
Job Costing and Project profitability Report
For businesses operating in construction, manufacturing, software development, or professional consulting, aggregate company profitability can hide underperforming contracts. A job costing report tracks every direct and indirect expense associated with a specific project, client engagement, or production batch against the revenue it generates.
This report consolidates direct labor hours, raw materials, subcontractor fees, and allocated overhead (such as equipment depreciation or facility utilities). By reviewing job costing reports in real time rather than waiting until a project concludes, project managers can identify scope creep, adjust resource allocation, and recalibrate pricing models for future bids.
Inventory valuation and turnover Report
For retail, e-commerce, and manufacturing enterprises, inventory often represents the largest single asset on the balance sheet, and the greatest source of tied-up capital. An inventory valuation report calculates the total monetary value of stock on hand using established accounting methodologies such as First-In, First-Out (FIFO) or Weighted Average Cost.
When paired with inventory turnover metrics, this report reveals how rapidly specific Stock Keeping Units (SKUs) convert into sales. Fast-moving items highlight opportunities for bulk purchasing discounts, while slow-moving or obsolete inventory alerts leadership to liquidate dead stock before storage costs and markdowns erode net margins.
Tax, Compliance, and Audit-Specific Reports
Beyond internal management and investor relations, accounting systems must generate specialized reports designed to satisfy regulatory bodies, auditors, and tax authorities. Accuracy in these reports is non-negotiable, as discrepancies can trigger costly audits, statutory penalties, or legal exposure.
General Ledger (GL) Detail Report
The general ledger detail report serves as the foundational audit trail of an organization's entire financial history. While summary statements condense thousands of entries into a handful of line items, the GL detail report lists every individual debit and credit posted to every account, from petty cash and prepaid insurance to accrued payroll and retained earnings, within a given timeframe.
External auditors rely heavily on the general ledger detail report to verify the integrity of financial statements. By tracing specific transactions back to source documents like bank statements, purchase orders, and receipts, auditors confirm that revenue is recognized in the proper period and that expenses are legitimately classified.
Payroll summary and Tax liability Report
Payroll represents one of the most complex and heavily regulated expense categories for any employer. A payroll summary report breaks down gross wages, overtime, bonuses, pre-tax benefit deductions (such as health insurance and retirement contributions), and net pay across departments or pay periods.
Alongside employee compensation, the accompanying payroll tax liability report details statutory withholdings, including federal and state income taxes, Social Security, Medicare, and unemployment insurance, alongside the employer's matching tax obligations. Finance teams use these reports to ensure timely tax remittances to government agencies and to reconcile year-end W-2 and 1099 filings.
Sales Tax liability Report
Businesses selling taxable goods or services across multiple jurisdictions face a labyrinth of state, county, and municipal tax rates. A sales tax liability report aggregates gross sales, exempt sales, and taxable sales by jurisdiction, calculating the exact amount of sales tax collected from customers and owed to each taxing authority. This report eliminates manual calculation errors during monthly or quarterly filing deadlines and provides clear documentation in the event of a state revenue audit.
Summary comparison of Core Accounting Reports
To clarify how these distinct documents fit together within a comprehensive financial reporting ecosystem, the table below summarizes their primary functions, audiences, and reporting frequencies.
| Report Name | Category | Primary Purpose | Target Audience | Typical Frequency |
|---|---|---|---|---|
| Income Statement (P&L) | Core Financial | Measures revenue, expenses, and net profitability over a set period. | Executives, Investors, Lenders | Monthly, Quarterly, Annually |
| Balance Sheet | Core Financial | Captures assets, liabilities, and equity at a single point in time. | Executives, Investors, Lenders | Monthly, Quarterly, Annually |
| Cash Flow Statement | Core Financial | Tracks actual cash inflows and outflows across operations, investing, and financing. | Executives, Investors, Treasury | Monthly, Quarterly, Annually |
| Budget vs. Actual Variance | Managerial | Compares planned financial targets against actual performance to isolate variances. | Department Heads, CFO, Board | Monthly, Quarterly |
| AR / AP Aging Reports | Operational | Tracks overdue customer receivables and upcoming vendor payment obligations. | Controllers, Credit & AP Teams | Weekly, Bi-weekly, Monthly |
| Job Costing Report | Managerial | Evaluates direct costs, overhead, and profit margins on individual projects. | Project Managers, Operations | Weekly, Per Milestone |
| General Ledger Detail | Compliance / Audit | Provides a complete, transaction-by-transaction record of all account activity. | Internal & External Auditors | Monthly, Annually, On-Demand |
| Sales & Payroll Tax Reports | Compliance / Tax | Calculates statutory tax withholdings and sales tax owed to government agencies. | Tax Authorities, Payroll/Tax Teams | Bi-weekly, Monthly, Quarterly |
Turning Financial data into strategic action
Accounting reports are far more than backward-looking compliance exercises or bureaucratic paperwork. When structured thoughtfully and reviewed on a consistent cadence, they function as an organization's central nervous system. Financial statements establish credibility with external capital providers; managerial and aging reports protect daily liquidity and operational margins; and compliance reports safeguard the enterprise against regulatory risk. By selecting the right combination of reports, and translating their figures into disciplined operational adjustments, business leaders transform raw ledger entries into a durable competitive advantage.